
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Northern Grown is stocked at 77 licensed dispensaries across Massachusetts, Maine, and Colorado, 47 of them in Massachusetts, with the deepest coverage in Blackstone, Boston, Brockton, Fairhaven, and Fall River. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
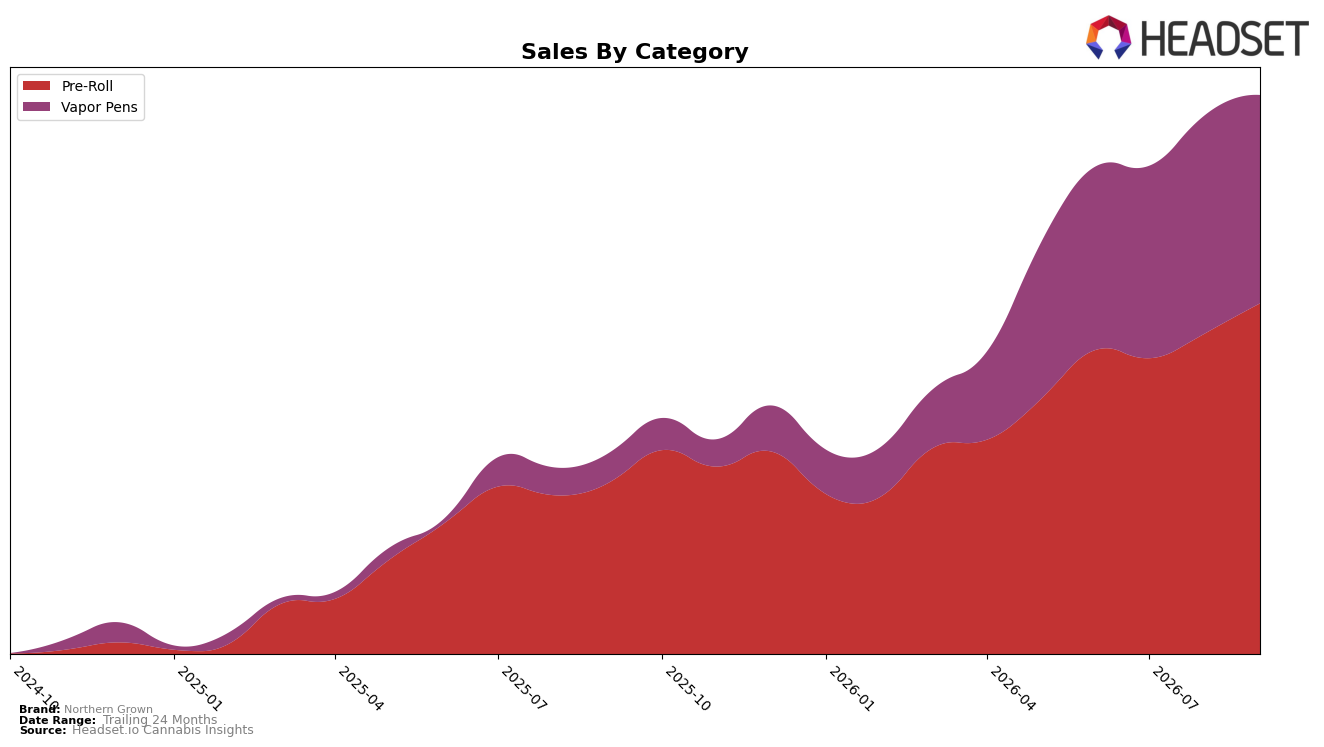
In September 2026, Northern Grown concentrated 62.68% of sales in Pre-Roll with 103.97% year-over-year growth and 9.40% month-over-month expansion, while Vapor Pens held 37.32% share with 575.37% year-over-year growth but a -4.51% month-over-month decline; the average price rose 14.65% year over year to $14.21 across the portfolio. Within Pre-Roll, Northern Grown is ranked 5th in Massachusetts, indicating scale in its lead category even as Vapor Pens’ rapid year-over-year expansion outpaces Pre-Roll’s rate; this split implies a portfolio leaning on Pre-Roll volume for near-term momentum while Vapor Pens drives longer-term mix shift.
The mix indicates an elasticity and positioning trade-off: Pre-Roll’s lower average price of $10.05 supports share stability and month-over-month growth of 9.40%, whereas Vapor Pens at $46.49 carry premium pricing but negative month-over-month momentum of -4.51% despite 575.37% year-over-year growth; ranking 5th in Massachusetts Pre-Roll suggests the brand competes on breadth and accessibility. This pattern implies that sustaining Pre-Roll’s rank and share at 62.68% underpins cash-flow reliability, while converting Vapor Pens’ outsized year-over-year gains into positive month-over-month trajectory would rebalance the mix toward higher average price points without eroding the Pre-Roll base.
Competitive Landscape
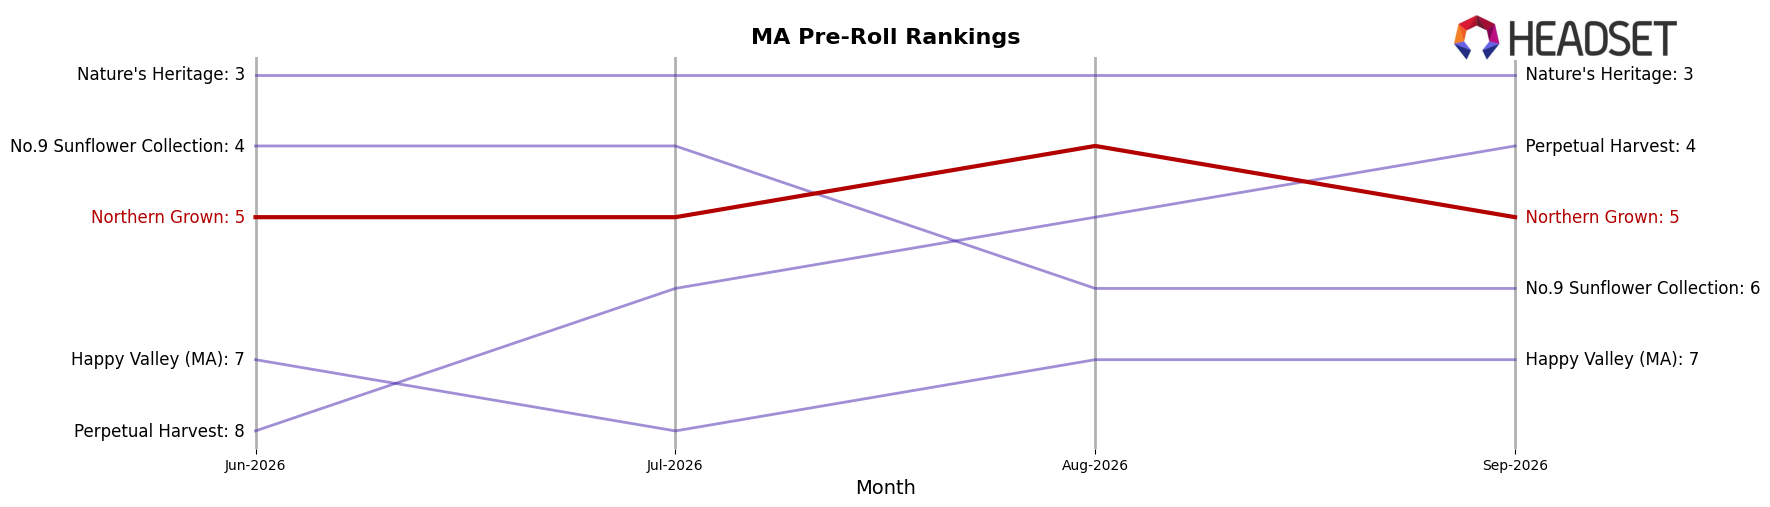
Northern Grown sits at rank #5 in MA Pre-Roll in September 2026 after a year-over-year climb of 5 positions from #10, with a 0-place change since June 2026 and a slip of 1 position from its peak rank #4 reached in August 2026; in contrast, Jeeter held #1 with 25.6% YoY sales growth while Cali-Blaze stayed at #2 alongside 110.7% YoY growth, and Perpetual Harvest moved up from #5 to #4 with 52.0% YoY growth, indicating Northern Grown’s rank trajectory implies stabilization just outside the top four and a need to outpace faster-growing rivals to re-enter its August 2026 peak tier.
Notable Products
Fog Cutter - Blue Dream Infused Pre-Roll 2-Pack (1g) posted the steepest shift in September 2026 with a -37.7% month-over-month drop and slid to rank 8, while Fog Cutter - Purple Grape Wreck Infused Pre-Roll 2-Pack (1g) also contracted by -14.5% at rank 10; this divergence implies a pruning of underperforming flavor profiles even within top-10 placement. Offsetting the declines, Fog Cutter - Yellow Kiwi Kush Infused Pre-Roll 2-Pack (1g) climbed +30.7% MoM to rank 3 and Fog Cutter - Rich's Italian Ice Infused Pre-Roll 2-Pack (1g) rose +16.0% at rank 1, indicating mix-shift momentum toward the fastest-cycling SKUs; with eight of the top ten in the same Pre-Roll family, concentration is high and $77,313 on the category leader suggests depth can fund selective rotation. The pattern implies Northern Grown is consolidating around a concentrated infused Pre-Roll core while cycling out slower flavors, pointing commercial focus toward high-velocity variants that can hold ranks 1–3 even as weaker SKUs retreat.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

