

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
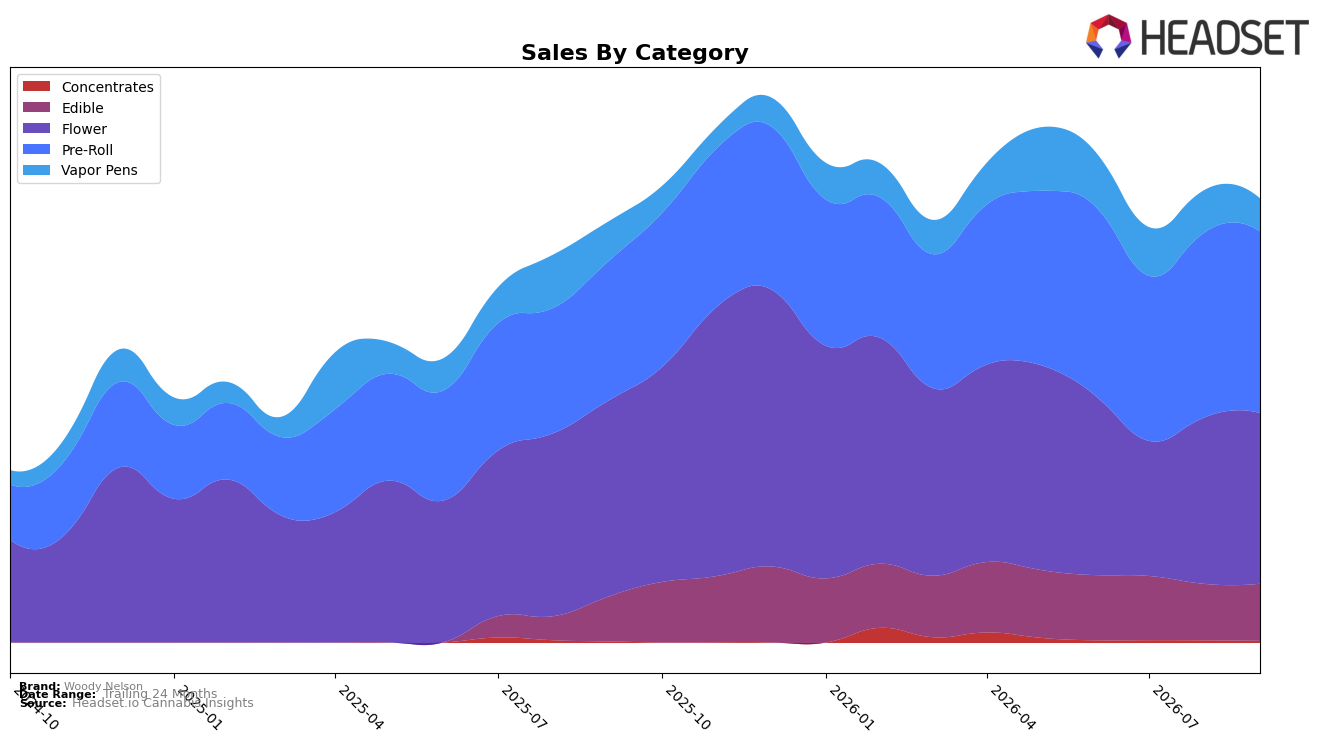
In September 2026, Woody Nelson’s mix tilted toward Pre-Roll at 40.9% share with 30.5% year-over-year growth but a 1.8% month-over-month dip, while Flower held 38.5% share with a 12.8% year-over-year decline yet a 2.6% month-over-month uptick. Edible expanded to 12.8% share with 27.7% year-over-year and 1.1% month-over-month growth, contrasting with Vapor Pens at 7.4% share posting a 17.5% year-over-year drop and a 22.5% month-over-month slide. Concentrates remained a niche at 0.4% share despite a 44.6% year-over-year rise and a 21.0% month-over-month pullback. The brand’s overall September 2026 average price fell 17.0% year-over-year to $27.83, and its top category placement in Pre-Roll aligns with a Ontario rank of 24, implying price-led mix defense anchored in Pre-Roll while Flower stabilizes sequentially.
The shift toward value-accessible inhalables suggests a repositioning: Pre-Roll’s 30.5% year-over-year gain alongside a 1.8% month-over-month dip indicates volume resilience but near-term saturation risk, while Flower’s 2.6% month-over-month rise against a 12.8% year-over-year decline signals selective recovery at higher price points. Edible’s 27.7% year-over-year growth with a 1.1% month-over-month increase broadens the entry funnel as Vapor Pens’ 22.5% month-over-month and 17.5% year-over-year declines compress the premium portable segment, shifting the brand’s center of gravity toward format simplicity. With a 17.0% year-over-year price reduction and a Pre-Roll rank of 24 in Ontario, the pattern implies Woody Nelson is trading margin for share in core inhalables while using Edibles as a secondary growth vector to hedge volatility in Vapor Pens.
Competitive Landscape
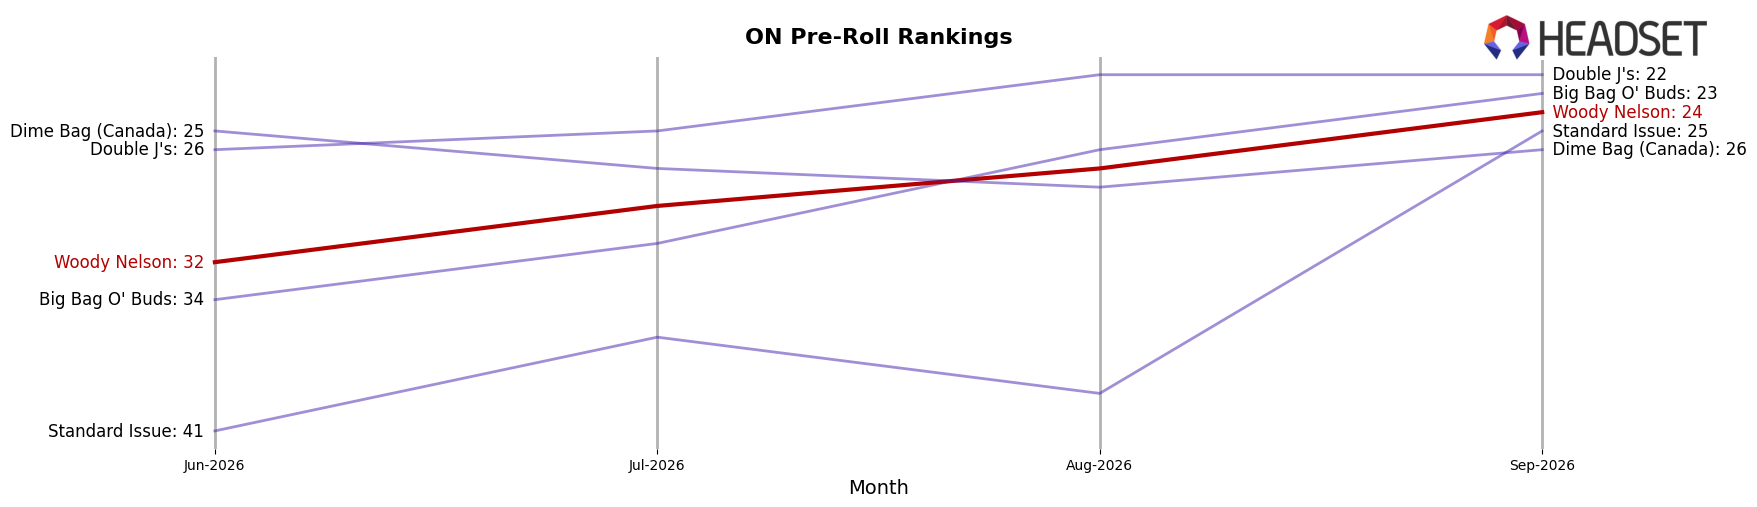
Woody Nelson sits at rank #24 in ON Pre-Roll for September 2026, improving 8 positions year over year from #32, and climbing 8 spots versus June 2026 where it also stood at #32; this coincides with hitting a peak rank of #24 in September 2026 while competitors re-ordered, as Back Forty / Back 40 Cannabis moved up from #2 to #1 and expanded sales by 46.6%, whereas General Admission slipped from #1 to #2 with a 38.2% sales decline; alongside these shifts, Spinach surged from #17 to #4 with 141.2% growth, outpacing category momentum and intensifying the climb needed for further share gains. The pattern implies Woody Nelson’s rank recovery is timing with competitor churn at the top rather than broad category uplift, so sustaining the ascent from #32 to #24 will require outgrowing fast risers while converting exposure into higher velocity rather than relying on rank volatility.
Notable Products
Blue Gumdrop Pre-Roll 3-Pack (1.5g) posted the steepest decline at -21.7% month over month and fell to rank 8, while Country Club Infused Pre-Roll (1g) dropped -17.3% at rank 9. Rocketeer Infused Pre-Roll (1g) retained rank 1 despite a -5.1% dip, and Rainbow Driver Resin-Infused Fruit Chews 10-Pack (100mg) in rank 2 grew +2.4% to $252,647. With eight of the top ten in Pre-Roll formats and two of those infused SKUs declining double digits, the pattern implies a pivot opportunity toward differentiated non-Pre-Roll offerings and selective support for premium Pre-Roll leaders rather than broad pack-line pushes.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

