

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
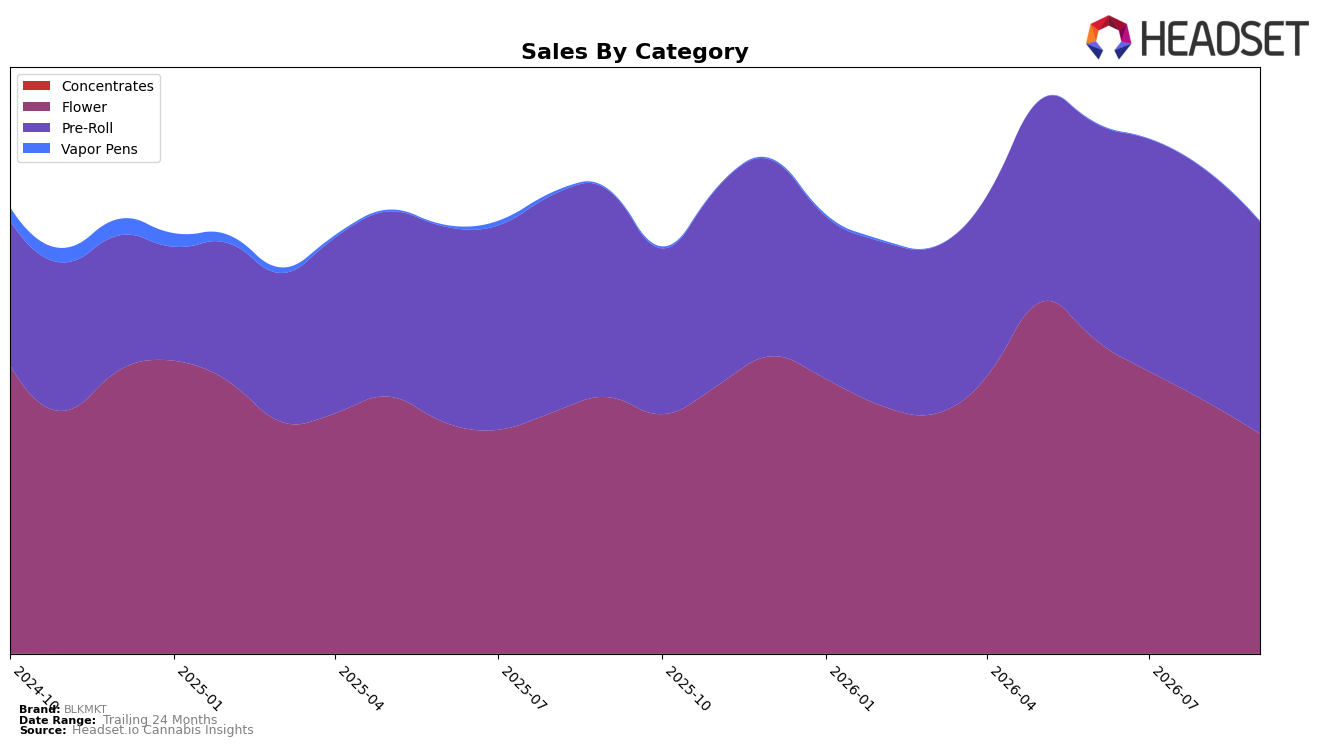
In September 2026, BLKMKT’s mix tilted to Flower at 50.84% share while Pre-Roll held 49.05% and Vapor Pens was 0.11%, with category dynamics pulling in different directions: Flower contracted both year over year by 14.29% and month over month by 13.08%, while Pre-Roll grew 2.59% YoY but slipped 8.28% MoM, and Vapor Pens fell 52.39% YoY yet ticked up 6.48% MoM. Despite an overall brand sales decline of 6.85% YoY alongside a 4.86% YoY increase in average price, the sales mix concentration in Flower coincided with a Flower category rank of 24 in Ontario, implying that reliance on a shrinking core category and limited diversification are anchoring short-term momentum.
The opposing signals—Flower losing double digits both YoY and MoM while Pre-Roll expands YoY but retreats MoM—imply a positioning pivot opportunity: leaning into Pre-Roll where share is near parity with Flower (49.05% vs. 50.84%) could buffer volatility from Flower’s 14.29% YoY contraction and reduce exposure to rank pressure at 24 in Ontario. The 6.48% MoM uptick in Vapor Pens, even off a 0.11% share and a 52.39% YoY drop, suggests a test-and-scale lane that, paired with a 4.86% YoY average price lift, could rebalance mix toward formats with steadier MoM trajectories and lessen dependence on a single category for share retention.
Competitive Landscape
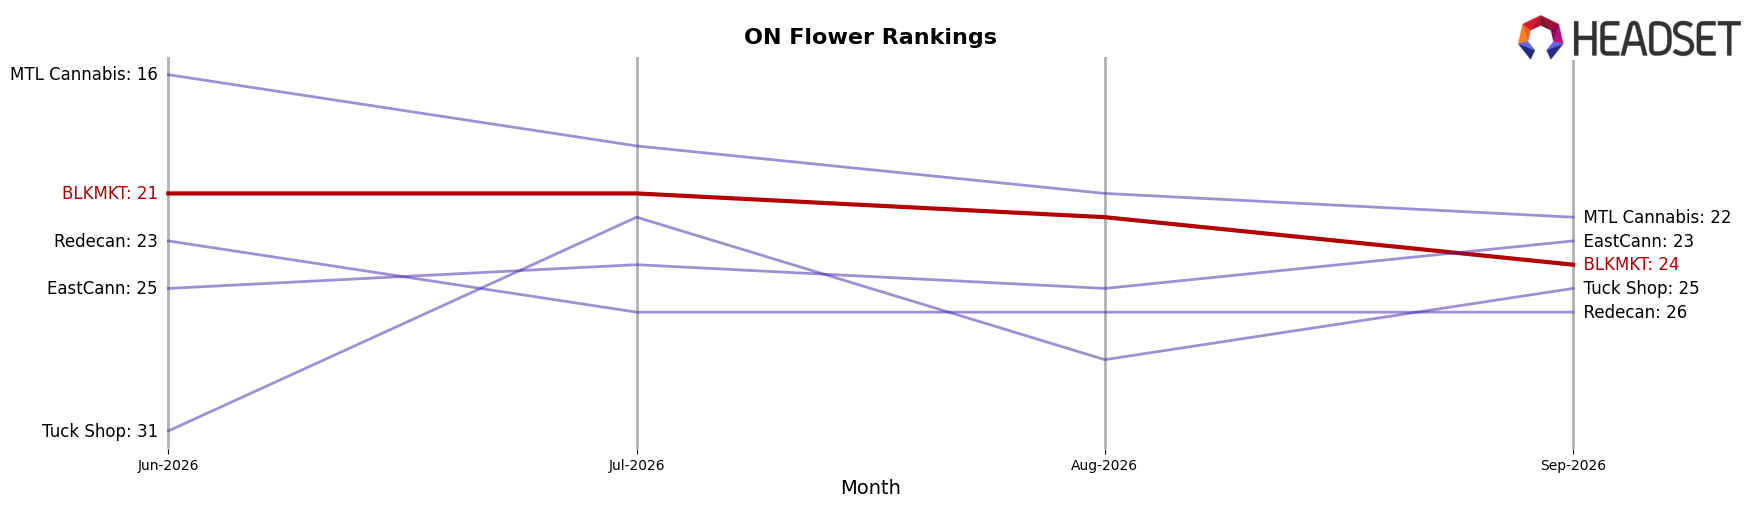
BLKMKT sits at rank #24 in ON Flower for September 2026, improving 5 positions year over year from #29 and slipping 3 positions from June 2026 when it was #21; relative to its peak of #20 in May 2026, the current standing is 4 ranks lower, while category leaders moved in the opposite direction, with Spinach climbing from #3 to #1 on 15.7% YoY sales growth and FIGR jumping from #14 to #5 on 51.7% YoY growth. Meanwhile, Back Forty / Back 40 Cannabis slid from #1 to #3 despite a -7.4% YoY sales change as Shred held steady at #2 with 13.4% YoY growth, indicating that BLKMKT’s modest YoY rank gain amid leaders consolidating top positions points to a need for sharper differentiation to convert mid-tier volatility into sustained ascent.
Notable Products
Britscotti Glass Cannon Blunt (1g) posted the steepest movement in September 2026 with a -42.9% month-over-month drop while holding rank 5, contrasting with Red Velvet Blunt (1g) up 31.2% at rank 6 and Jealousy Pre-Roll (1g) inching up 2.7% at rank 1. Rainbow P Pre-Roll (1g) fell -30.0% at rank 2 versus Dragon Glass Pre-Roll 5-Pack (2.5g) down a lighter -4.8% at rank 3, and Yuck Mouth Pre-Roll (1g) declined -17.7% while tied at rank 4 with Red Dragon Pre-Roll (1g) at -6.7%. Eight of the top ten SKUs are Pre-Rolls, and the contrast between a -42.9% decline and a +31.2% gain inside the blunt subset implies mix volatility around format preference rather than a broad demand shift. The concentration at ranks 1 through 7 in Pre-Rolls alongside the late entry of Flower Exclusives (7g) at rank 8 with $79,110 suggests BLKMKT is leaning into Pre-Roll dominance while testing whether a single Flower anchor can diversify revenue without diluting top-rank momentum.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

