

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Divvy is stocked at 58 licensed dispensaries across Michigan and Florida, 52 of them in Michigan, with the deepest coverage in Detroit, Kalamazoo, New Buffalo, Ypsilanti, and Adrian. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
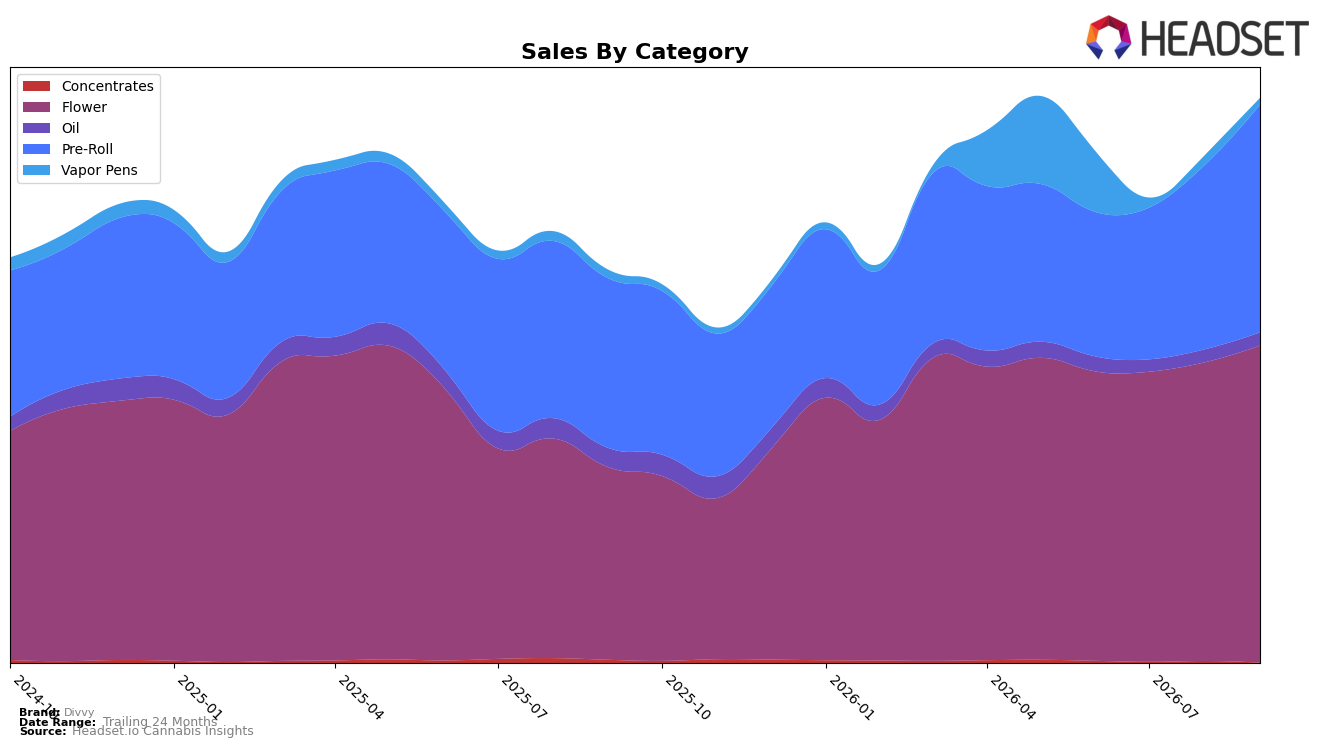
Divvy concentrated 55.83% of September 2026 sales in Flower with 64.29% year-over-year growth and 6.17% month-over-month, while Pre-Roll held 40.12% share with 33.94% year-over-year and 23.43% month-over-month gains; Oil slid to 2.47% share with a 29.72% year-over-year decline despite a 1.38% month-over-month uptick. Vapor Pens contracted to 1.36% share with an 18.80% year-over-year drop and a 27.76% month-over-month decline, and Concentrates fell to 0.21% share with a 70.34% year-over-year and 58.16% month-over-month pullback; this skew toward Flower and Pre-Roll, alongside a 46.99% year-over-year average price decrease and 43.16% total sales growth, implies volume-led expansion concentrated in inhalables while non-core formats are being deprioritized.
With Flower ranked 7 in Alberta, the 64.29% year-over-year growth and 6.17% month-over-month lift in that category, paired with Pre-Roll’s 23.43% month-over-month acceleration and 33.94% year-over-year rise, positions Divvy to compete on depth within its two largest format pools as price-led accessibility deepens penetration. The simultaneous 18.80% year-over-year and 27.76% month-over-month declines in Vapor Pens and a 70.34% year-over-year contraction in Concentrates indicate a deliberate simplification of the portfolio mix toward higher-turn SKUs, suggesting the path to gain share is reinforcing Flower and Pre-Roll assortment breadth while using Oil’s 1.38% month-over-month improvement as a test bed rather than a scale driver.
Competitive Landscape
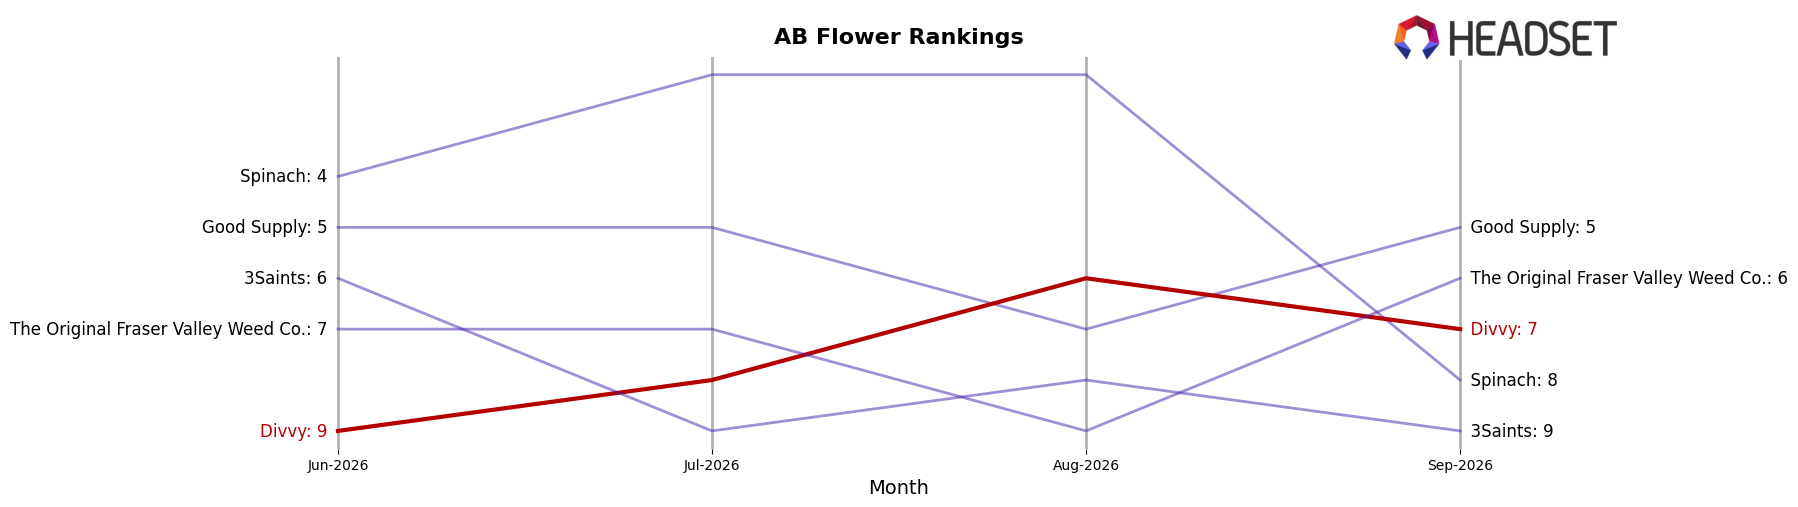
Divvy sits at #7 in AB Flower in September 2026, improving 5 ranks year over year from #12 and moving up 2 spots since June 2026, while its best position of #6 arrived in August 2026 before a 1-rank slip. Competitive shifts are mixed: Back Forty / Back 40 Cannabis climbed from #2 to #1 even as its sales fell 6.7% year over year, and Good Supply dropped from #1 to #5 alongside a 43.0% year-over-year sales decline; meanwhile, FIGR surged from #11 to #4 with 141.2% sales growth. The combination of Divvy’s 5-rank YoY ascent and a 1-rank pullback from its August 2026 peak implies mid-pack momentum that is vulnerable to sharper upswings from fast risers and volatility among incumbents.
Notable Products
Watermelon Pineapple Infused Pre-Roll 2-Pack (2g) posted the standout move with a 98.2% month-over-month gain, jumping into rank 6 while Roll Up Sativa Pre-Roll (1g) climbed 30.4% at rank 4. Roll Up Indica Pre-Roll (0.5g) advanced 37.9% to hold rank 1 as Blueberry (7g) slipped 1.2% at rank 5, and five of the top six SKUs are Pre-Rolls, with eight of the top ten in the same category. The concentration in Pre-Rolls alongside only mild declines in Flower suggests Divvy is leaning into higher-velocity, format-led demand rather than strain-led Flower, reallocating attention to infused and value-dosed Pre-Rolls for October 2026 and beyond.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

