

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Originals is stocked at 172 licensed dispensaries across California and Massachusetts, 135 of them in California, with the deepest coverage in Los Angeles, Santa Ana, Corona, Long Beach, and San Bernardino. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
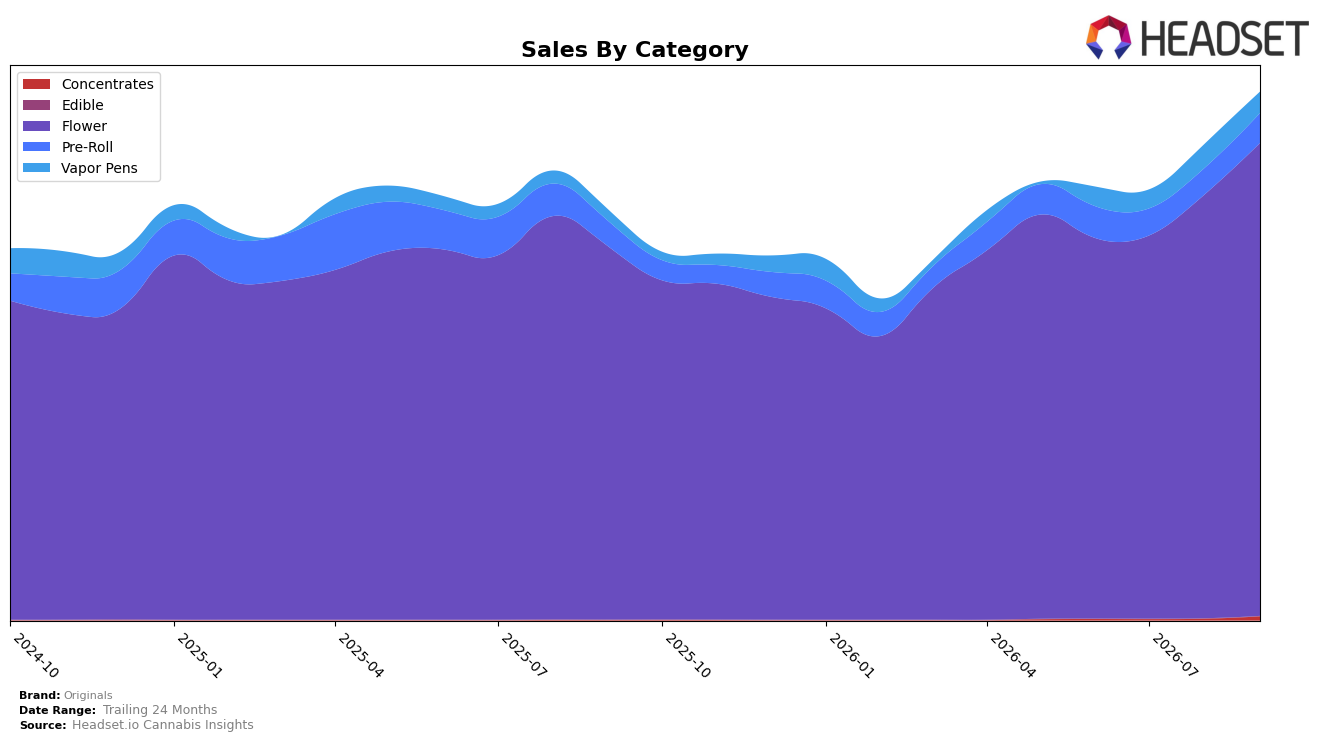
Originals concentrated 89.69% of September 2026 sales in Flower with 26.77% year-over-year growth and 11.60% month-over-month growth, while Pre-Roll held 5.60% share with 17.91% YoY and 12.89% MoM gains. Vapor Pens accounted for 3.98% share with 90.15% YoY growth but declined 11.21% MoM, and Concentrates—though just 0.73% share—spiked 2,158.23% YoY and 159.72% MoM. With an average price down 42.84% YoY to $15.02 and a Flower category rank of 19 in California, the mix points to volume-led gains anchored in Flower while small categories test outsized volatility; the implication is a strategy centered on defending Flower scale as a base while selectively piloting adjacent formats.
The divergent MoM trends—double-digit gains in Flower (+11.60%) and Pre-Roll (+12.89%) against a contraction in Vapor Pens (-11.21%)—suggest Originals is leaning into combustible formats for near-term share stability, using price elasticity to convert demand after a 42.84% YoY price reset. The surge in Concentrates (+159.72% MoM, +2,158.23% YoY) alongside Vapor Pens’ pullback indicates experimentation is shifting toward higher-potency niches rather than inhalable convenience, implying positioning that prioritizes Flower leadership (rank 19 in California) and a barbell of Pre-Roll scale with Concentrates exploration rather than broad vape expansion.
Competitive Landscape
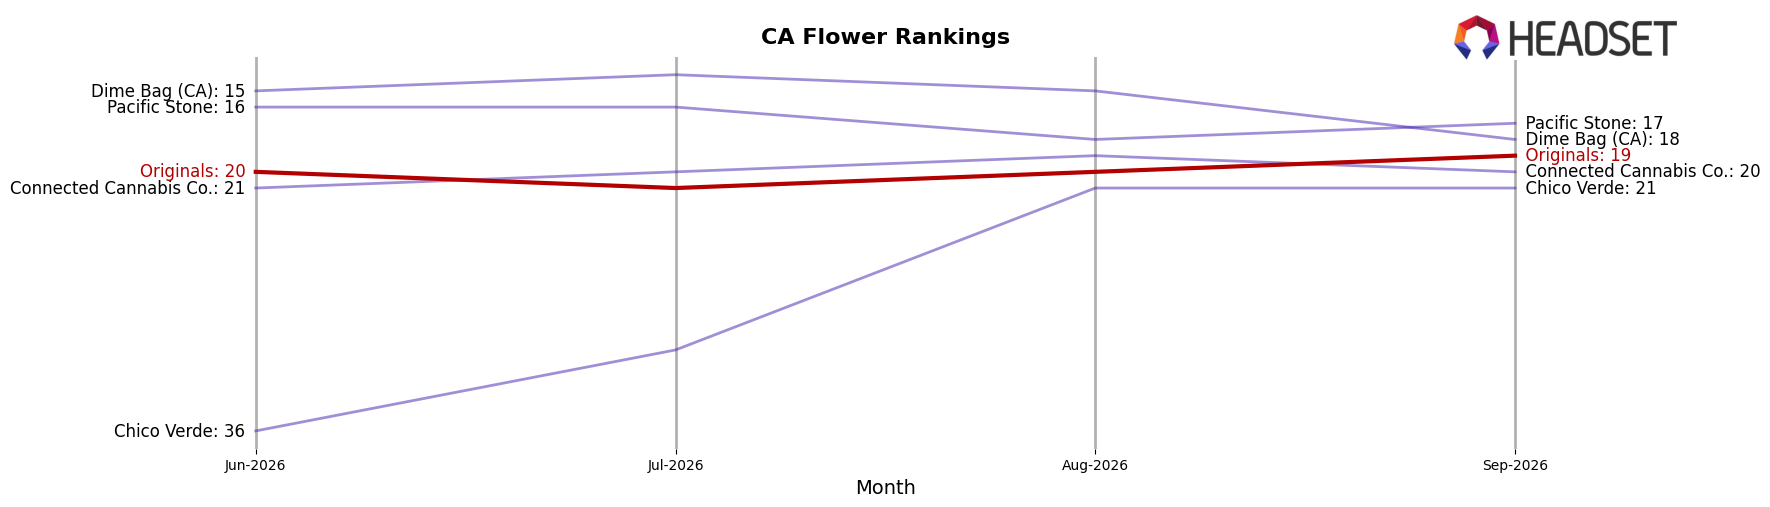
Originals sits at rank #19 in CA Flower in September 2026, a 1-place improvement from #20 year over year, and matching its peak at #19, while its 3-month position held at #20 indicating only a 1-rank climb over the quarter; in contrast, STIIIZY moved from #2 to #1 with 47.8% YoY sales growth and CAM advanced from #3 to #2 with 28.9% YoY growth, whereas CannaBiotix (CBX) slipped from #1 to #3 alongside a -21.1% YoY decline; the mix of upward mobility among leaders and a top-three reversal implies that Originals’ incremental rank gain, though only +1 place YoY and +1 place versus three months ago, positions it to capture share if churn continues among higher tiers.
Notable Products
The steepest movement in September 2026 was Oaksterdam (14g) dropping 31.7% to rank 8, while Ghost OG (3.5g) also slipped 12.6% at rank 5, indicating volatility concentrated in larger pack sizes. In contrast, Gelato (3.5g) climbed 24.5% at rank 3 and Blue Dream (3.5g) rose 10.1% at rank 10, while Bubba (3.5g) held rank 1 despite a 3.0% dip, with four of the top ten being 3.5g Flower SKUs that are gaining or holding share versus mixed trends in larger formats. The $143,681 result for Oaksterdam (14g) alongside a 31.7% decline and Bubba (3.5g) staying at rank 1 despite a 3.0% drop implies the product mix is tilting toward reliable 3.5g velocity over bulk-driven volume, pushing Originals toward depth in core eighths rather than breadth in larger sizes.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

