

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
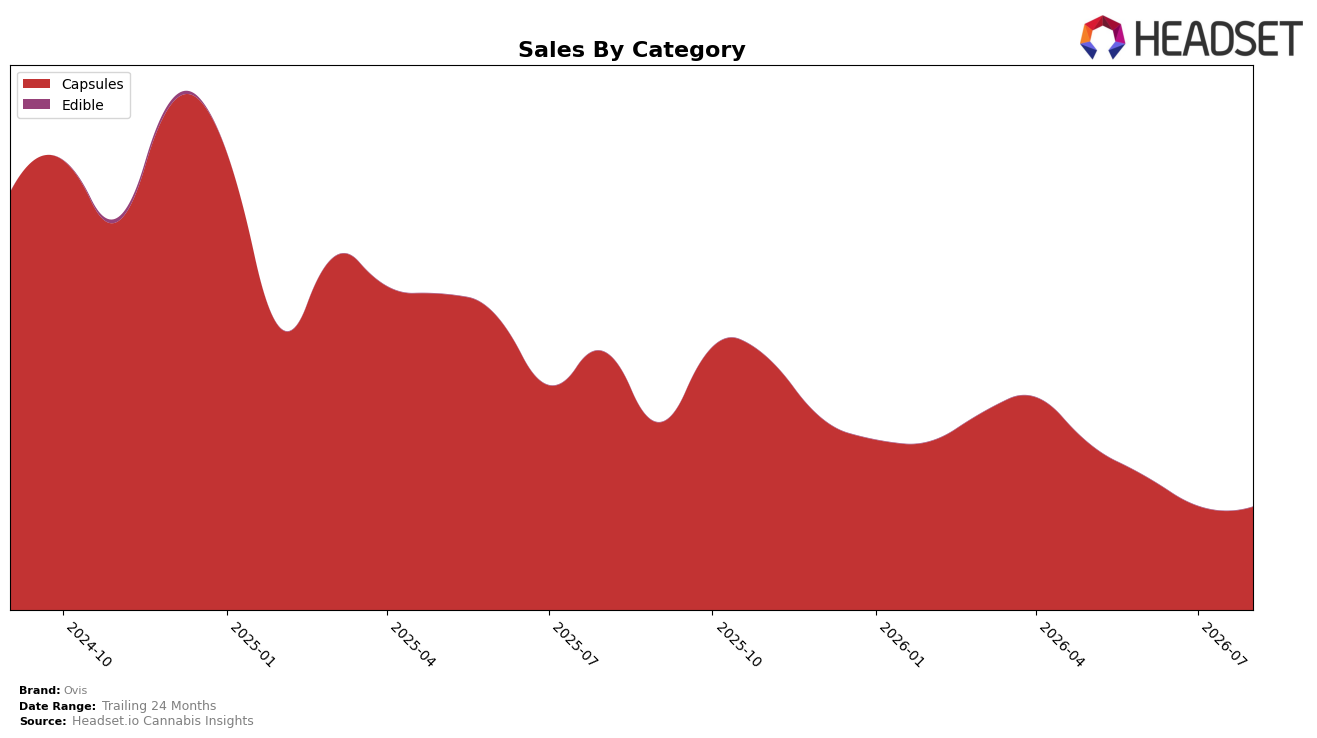
In August 2026, Ovis operated as a single-category brand, with Capsules accounting for 100.0% of sales, a year-over-year decline of 60.2% alongside a month-over-month dip of 0.7%. Average price rose 2.5% year over year to $16.31, while category share concentration at 100.0% left no internal mix offsets to counter the 60.2% annual contraction. With the top market listed as AB and rank data for Alberta Capsules unavailable, the absence of diversification combined with a 78.1% two‑year sales decline implies the brand’s volume base in Capsules is shrinking faster than any price relief can stabilize.
The consolidation in Capsules, paired with a 0.7% monthly slide and 2.5% price increase, indicates Ovis is leaning on unit pricing to slow erosion rather than spreading risk across adjacent formats. Given a 60.2% annual sales drop concentrated in a single category and a 78.1% decline over 24 months, the brand’s positioning is narrowing toward a niche Capsule presence in AB, where lack of rank signals either sub-scale visibility or channel retrenchment; this pattern implies that without reintroducing at least one additional category or resetting price-pack architecture, future rank recovery in Alberta Capsules is unlikely.
Competitive Landscape
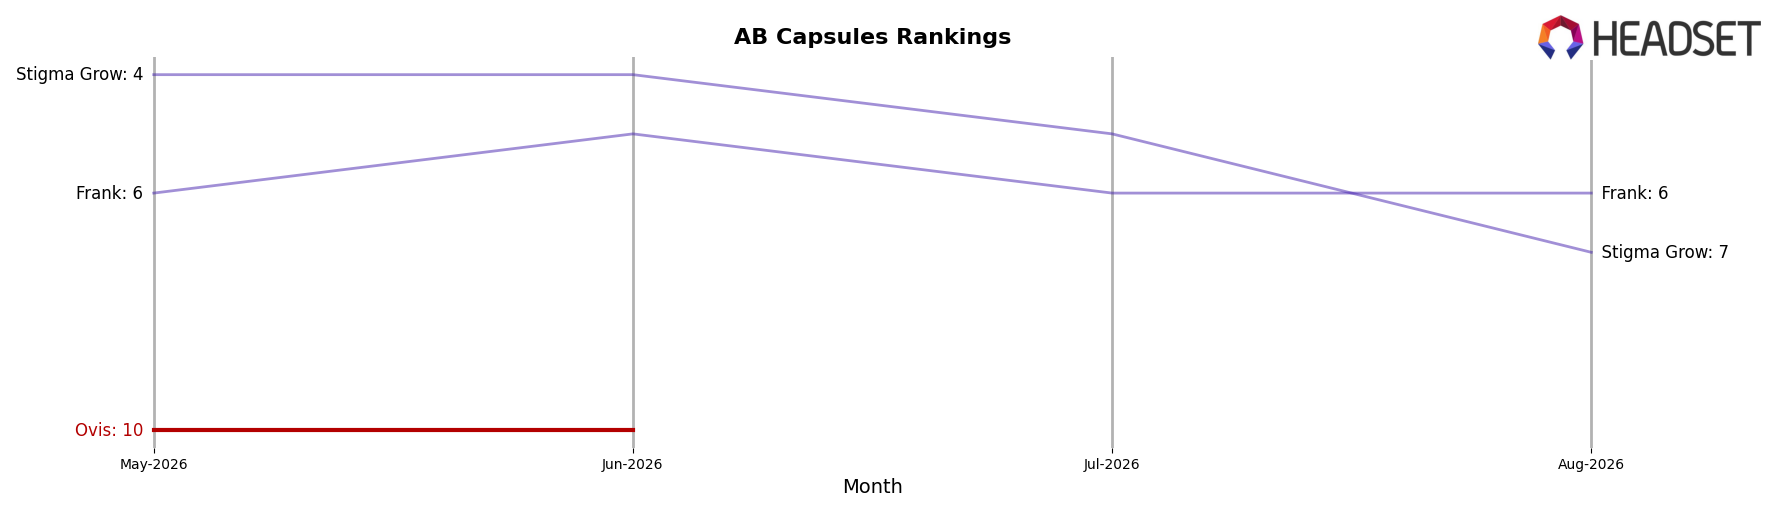
Ovis sits at #10 in AB Capsules in August 2026 with no year-over-year rank change from #10, and no 3-month movement from #10 either, while its historical peak was #7 in April 2025; in contrast, Tweed held #1 both this year and last year with sales up 23.1%, and Leisure Club advanced from #7 to #5 despite a 36.4% sales decline, indicating that Ovis’s flat ranking amid competitors’ upward mobility or retention at the top suggests a stable but capped position unless it can convert volatility above it into share gains.
Notable Products
CBD/THC 1:1 Capsules 15-Pack (150mg CBD, 150mg THC) posted the largest month-over-month surge at 236.9% to reach rank 3, while THC Softgel 15-Pack (150mg) fell 23.9% yet held rank 1, indicating share is consolidating around balanced formulations rather than pure THC. CBN Goftgels 10-Pack (200mg CBN) rose 124.7% into rank 5 as Blue THC Softgel 50-Pack (125mg) declined 27.5% to rank 4, and Capsules account for all top-ten placements this month, pointing to a portfolio concentrated in ingestibles over inhalables. Taken together, the gains in balanced and minor-cannabinoid SKUs alongside declines in THC-only formats imply Ovis is tilting assortment and demand toward ratio-driven relief and away from single-compound potency in August 2026.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

