

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
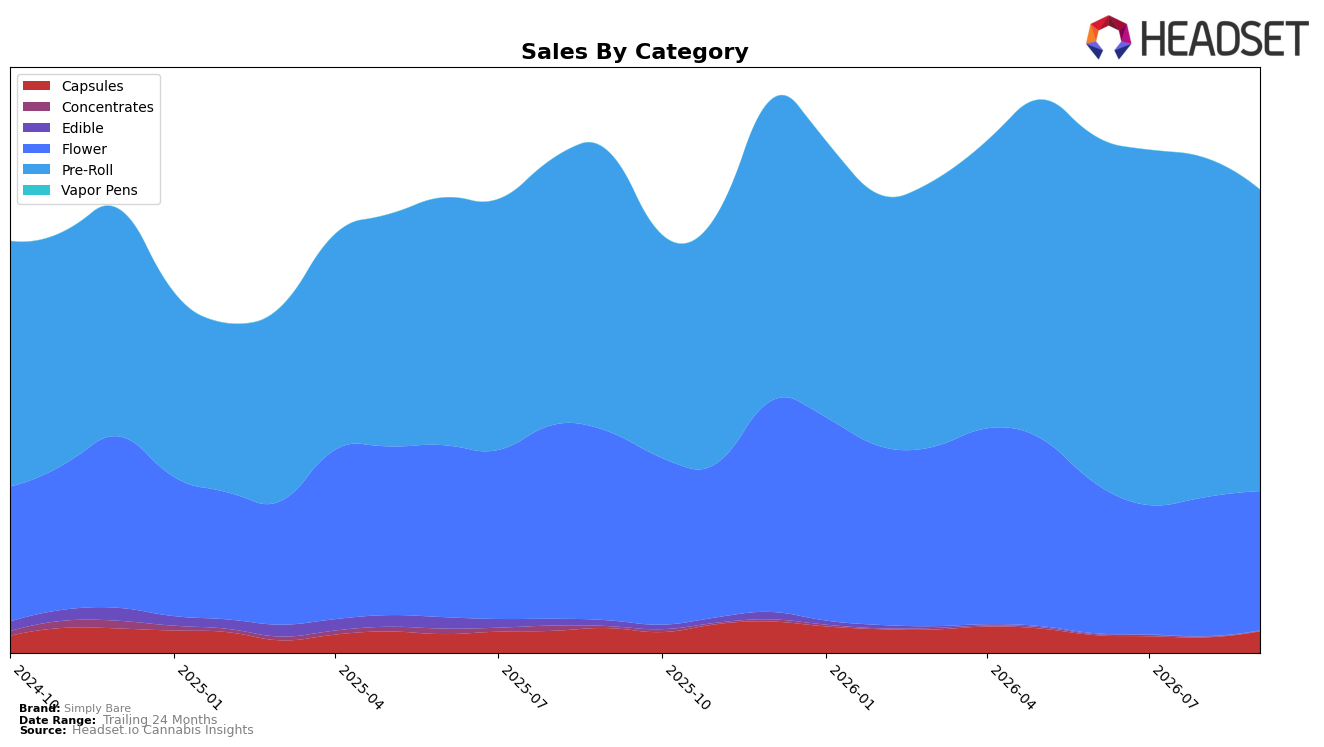
In September 2026, Simply Bare’s mix concentrated in Pre-Roll at 65.19% share with year-over-year growth of 7.65% but month-over-month decline of 11.21%, while Flower held 30.06% share with a 26.34% year-over-year drop and a 0.28% month-over-month uptick. Smaller lines were volatile: Capsules at 4.70% share rose 39.14% month-over-month despite a 12.66% year-over-year decline, whereas Concentrates fell 89.97% year-over-year and 63.30% month-over-month to 0.04% share, and Edible slid 98.12% year-over-year yet climbed 25.15% month-over-month to 0.02% share. With brand sales down 7.64% year-over-year alongside a 15.49% average price decrease and Pre-Roll still the top category in ON, the pattern implies a price-led defense of volume centered on Pre-Roll while legacy revenue from Flower contracts and peripheral categories serve only marginal, high-volatility contributions.
These shifts imply Simply Bare is leaning into a value-accessible Pre-Roll core while cautiously stabilizing Flower, evidenced by Pre-Roll’s rank position at 27 in Alberta Pre-Roll and the simultaneous 11.21% month-over-month dip that likely reflects price and promo cycling rather than structural demand loss. The divergence—Capsules’ 39.14% month-over-month rebound against Concentrates’ 63.30% month-over-month slide and Edible’s 25.15% month-over-month lift from a near-zero base—suggests selective SKU pruning around low-velocity niches while protecting share where price elasticity is favorable; the brand’s 6.92% sales gain over 24 months alongside a 7.65% year-over-year Pre-Roll lift indicates the positioning is migrating toward dependable, lower-ticket throughput over premiumized, higher-ticket Flower.
Competitive Landscape
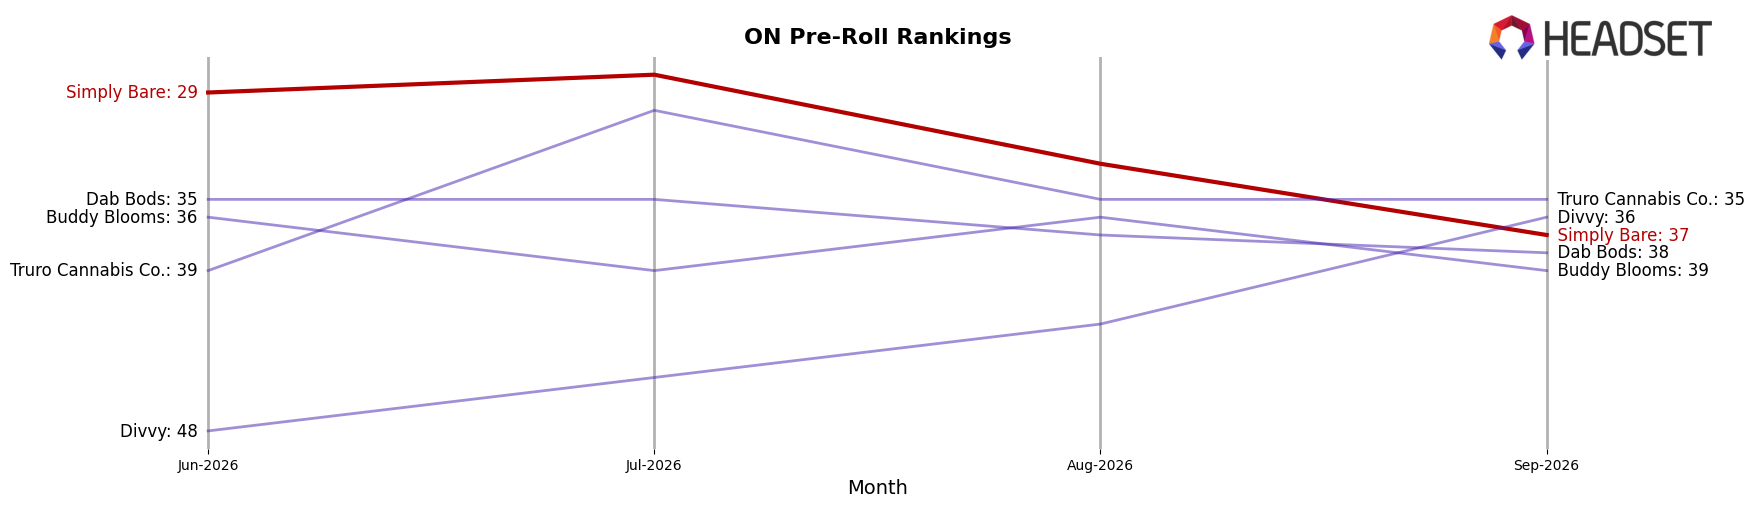
Simply Bare sits at rank #37 in ON Pre-Roll for September 2026, down 1 position year over year from #36 and down 8 positions from June 2026’s #29, even after peaking at #28 in July 2026; this contrasts with Back Forty / Back 40 Cannabis moving from #2 to #1 and Spinach climbing from #17 to #4 on 141.2% YoY sales growth, while General Admission slipped from #1 to #2 alongside a 38.2% YoY sales decline. The combination of a brief July 2026 peak at #28 followed by a retreat to #37, alongside competitors advancing multiple ranks, implies Simply Bare is losing relative shelf velocity and must either re-price or refresh assortments to avoid further share leakage.
Notable Products
BC Organic Fruit Loopz Pre-Roll (0.5g) led the downturn with a -62.8% month-over-month slide while holding rank 1, and Harlequin Pre-Roll 5-Pack (1.5g) fell -58.2% at rank 10, together signaling price- or distribution-driven pressure at both ends of the ranking. Against those declines, BC Organic Pink Drip Pre-Roll (0.5g) climbed +31.9% to rank 5, and four of the top ten are single 0.5g Pre-Rolls, indicating assortment weight in solos rather than multi-packs. With eight of the top ten in September 2026 concentrated in the Pre-Roll category and only one SKU posting a double-digit gain, the mix implies Simply Bare is leaning into breadth of Pre-Roll formats but needs to rebalance toward faster-turning singles to stabilize momentum.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

