

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Phat Panda is stocked at 284 licensed dispensaries across Washington, Massachusetts, and 3 other states, 232 of them in Washington, with the deepest coverage in Seattle, Tacoma, Spokane, Vancouver, and Everett. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
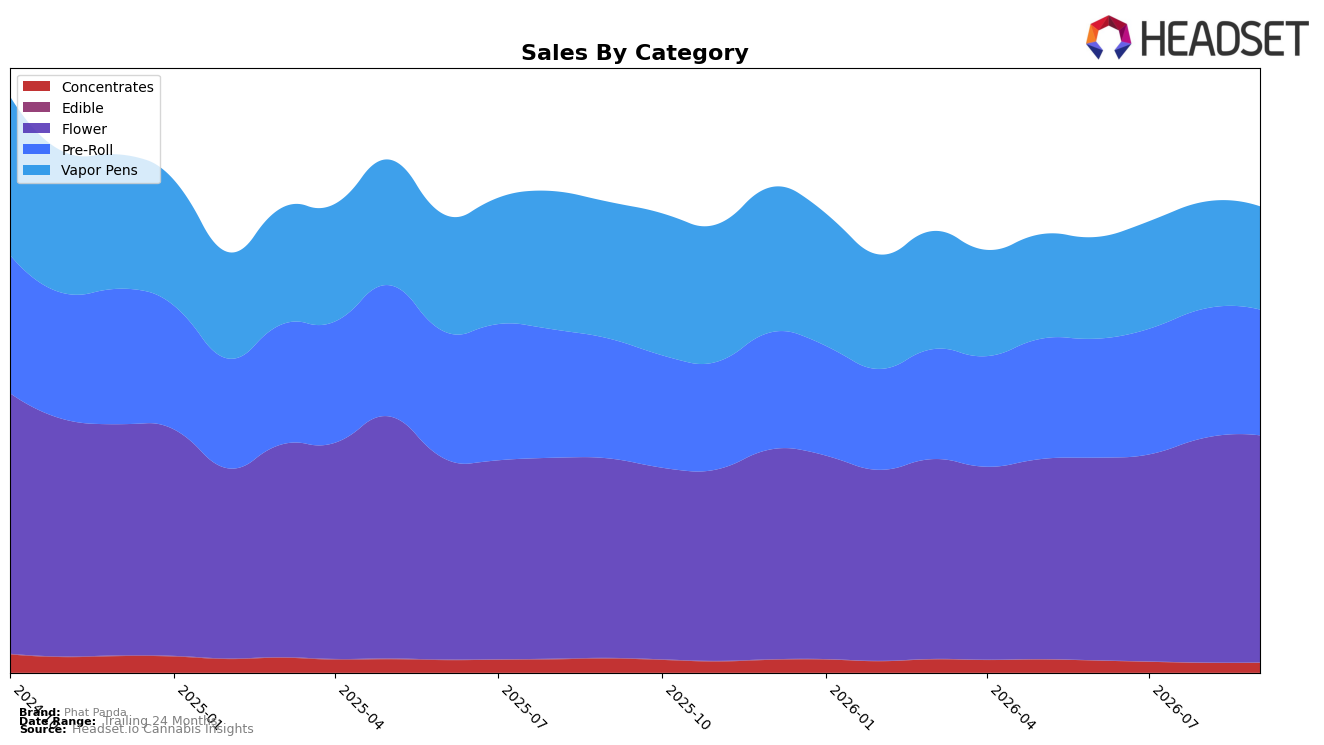
Phat Panda’s category mix in September 2026 concentrated in Flower at 48.73% share with year-over-year growth of 13.85% and month-over-month growth of 1.09%, while Pre-Roll held 26.98% share with 4.87% YoY and a -2.65% MoM dip. Vapor Pens accounted for 22.14% share but declined -24.48% YoY and -3.43% MoM, and Concentrates were 2.13% share with -30.10% YoY alongside a 1.09% MoM uptick; Edible was 0.02% share with -75.93% YoY and -38.11% MoM. Against this mix, brand-level sales were down -0.98% YoY despite an average price decrease of -3.38%, and the Flower rank stood at 1 in Washington, implying reliance on Flower growth to offset Vapor Pens and Concentrates headwinds while Pre-Roll softness limited MoM momentum.
The shift toward Flower’s rising share and rank 1 position in Washington suggests the brand is leaning into a category where price elasticity and assortment breadth can absorb promotional pressure, whereas the -24.48% YoY contraction in Vapor Pens and -30.10% YoY in Concentrates indicate portfolio exposure where price cuts are not translating to volume. With Pre-Roll’s -2.65% MoM and Vapor Pens’ -3.43% MoM, the mix is trending more Flower-heavy, which stabilizes near term but increases category concentration risk; the implication is to prioritize Flower-led acquisition and basket entry while reconfiguring Vape and Concentrate SKUs to prevent further share bleed that could erode the 48.73% anchor.
Competitive Landscape
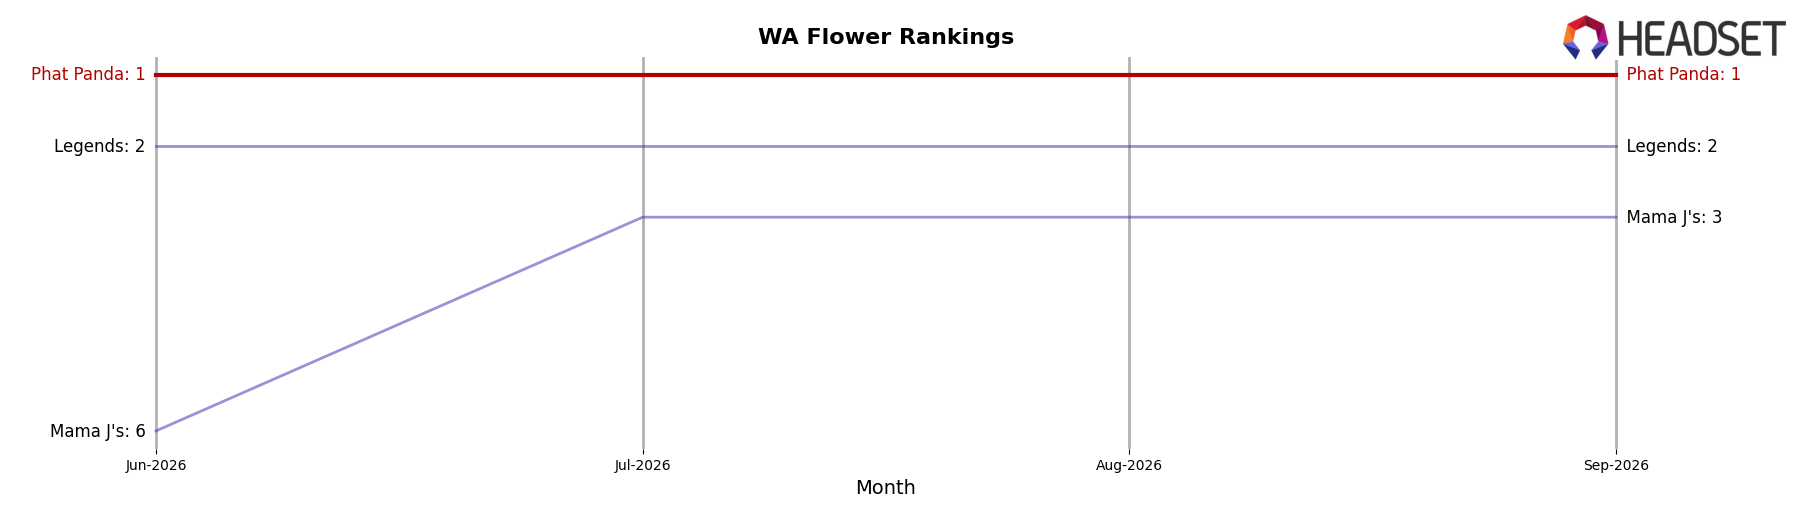
Phat Panda holds rank #1 in WA Flower in September 2026 with a 0-place YoY rank change from #1, while Legends sits at #2 with a -16.9% YoY sales decline and Mama J's moved from #4 to #3 on +3.2% YoY sales, indicating peers are either slipping or making only incremental gains; meanwhile, Lifted Cannabis Co advanced from #6 to #4 with +6.3% YoY sales and Hemp Kings surged from #24 to #5 on +105.1% YoY sales, yet neither closed the rank gap to #1. The trajectory—unchanged at #1 across September 2025 to September 2026 and peaking again at #1 in September 2026—implies sustained category leadership that competitors must outpace by multiple rank positions rather than modest percentage lifts.
Notable Products
Bangers - Golden Pineapple Pre-Roll 2-Pack (1g) posted the standout jump in September 2026 with a +126.5% month-over-month surge that propelled it to rank 2, while OG Chem Pre-Roll (1g) fell -63.7% MoM yet still held rank 1; that divergence suggests a rapid shift toward value-oriented multipacks even as the longtime leader contracts. Across the top ten, 10 of 10 products are Pre-Rolls, and two Platinum-branded Trophy Wife formats moved in opposite directions with the single (rank 3) up +9.2% MoM and the 28-Pack (rank 5) up +16.8% MoM, indicating consumer trade-up within the same strain family. Golden Pineapple Pre-Roll (1g) at rank 7 slid -8.4% MoM even as its Bangers 2-Pack counterpart surged, pointing to substitution from singles to 2-packs around a shared flavor profile. The pattern implies Phat Panda is concentrating demand into pre-roll multipacks and higher-count formats, signaling a portfolio pivot toward bundle value while maintaining premium strain anchors.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

