

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Pucks is stocked at 48 licensed dispensaries across Arizona, with the deepest coverage in Phoenix, Mesa, Chandler, El Mirage, and Tolleson. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
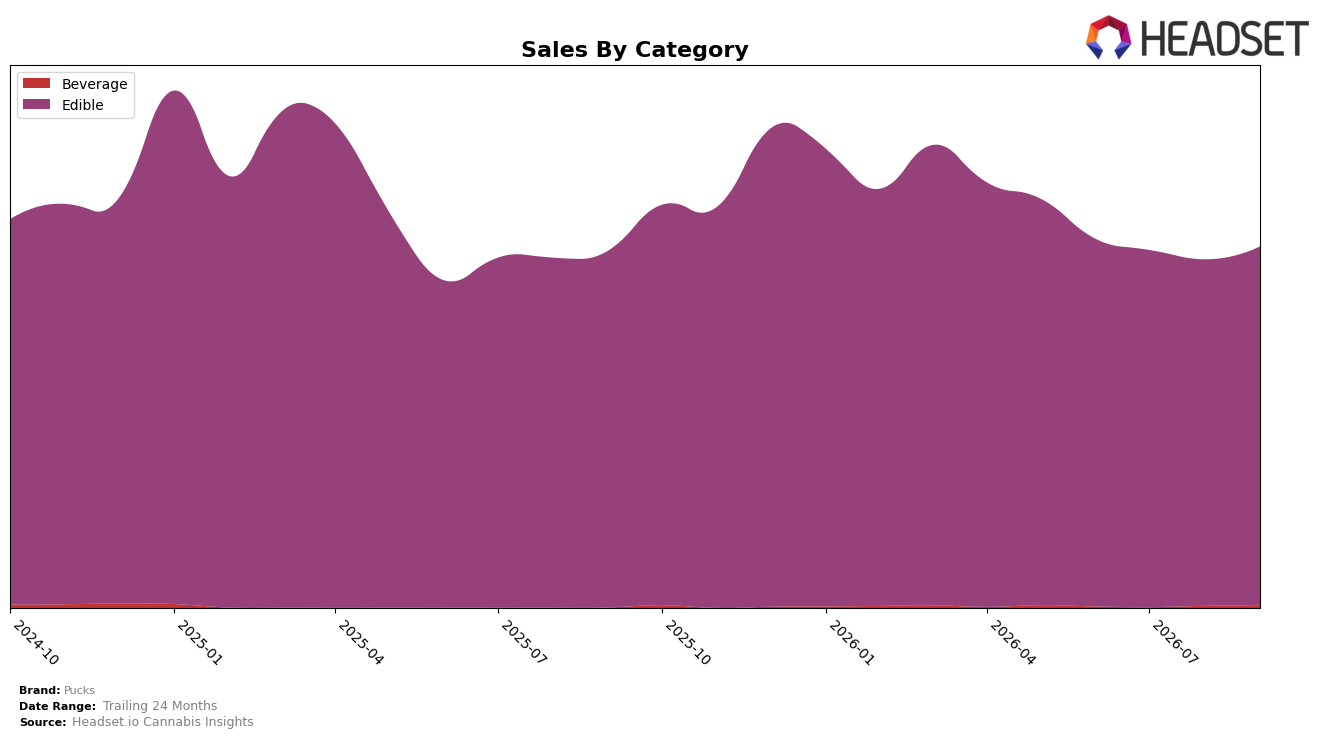
Pucks concentrated 99.46% of September 2026 sales in Edible, with Beverage at 0.54% share; within those slices, Edible grew 0.74% year over year and 3.75% month over month, while Beverage surged 317.00% year over year but declined 5.06% month over month. Average price fell 23.41% year over year to $7.67, paired with total brand sales up 115.77% year over year, implying the volume mix is expanding even as pricing compresses, and that the small Beverage footprint can swing on rate-of-change without shifting overall share.
Positioning skews toward value-led Edible scale, evidenced by the +3.75% month-over-month lift in Edible against a -5.06% month-over-month dip in Beverage, and reinforced by a 99.46% category share concentration that limits diversification risk management. In Arizona Edible, a rank of 15 alongside a 0.74% year-over-year Edible growth rate signals mid-pack throughput where price elasticity from the -23.41% average price change is likely a primary lever, suggesting Pucks can trade rank upward by leaning into price-pack architecture rather than category expansion.
Competitive Landscape
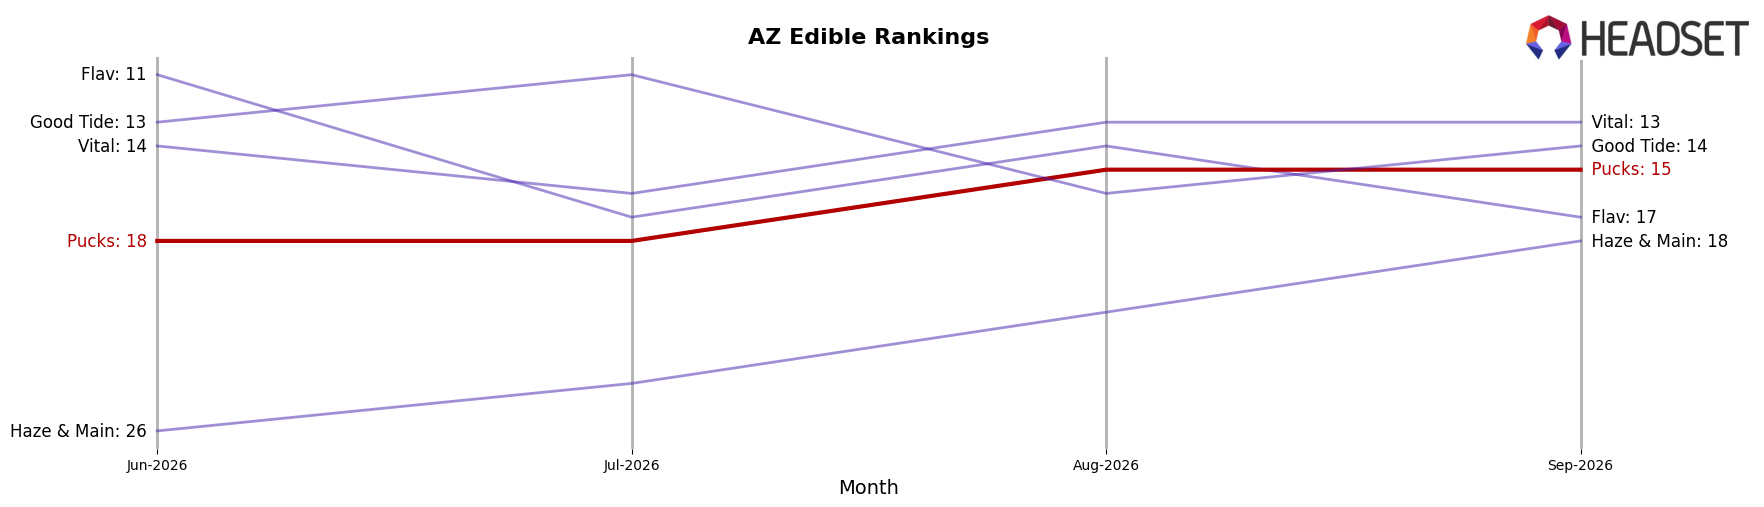
Pucks ranks #15 in AZ Edible in September 2026, down 2 places year over year from #13, after improving 3 spots since June 2026 when it was #18; this trailing trajectory contrasts with Baked Bros rising from #4 to #2 and posting a 22.5% YoY sales increase while Wyld holds #1 despite a 16.2% YoY sales decline. Compared with its peak at #12 in January 2025, the current #15 plus a 2-rank YoY slip signals erosion in relative position even as some leaders contract, implying Pucks must convert its recent 3-month climb into sustained share capture or risk further rank loss against competitors with either accelerating growth or resilient rank.
Notable Products
CBD/THC 3:1 PM Gummies 10-Pack (150mg CBD, 50mg THC) posted the steepest movement in September 2026 with a -17.6% month-over-month drop while holding rank 3, contrasting with Watermelon Gummies 10-Pack (100mg) up 10.7% at rank 1. Watermelon Sorbet Taffy 10-Pack (100mg) advanced 19.8% at rank 2, and eight of the top ten are Edible gummies or taffies, concentrating demand in a single dosage form. This mix signals a pivot toward flavor-led, standard-dosage Edibles while functional CBD/THC blends lose momentum despite top-three placement.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

