

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Quickies Prerolls is stocked at 53 licensed dispensaries across California, Oregon, and Massachusetts, 28 of them in California, with the deepest coverage in Los Angeles, Corona, El Monte, Moreno Valley, and Perris. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
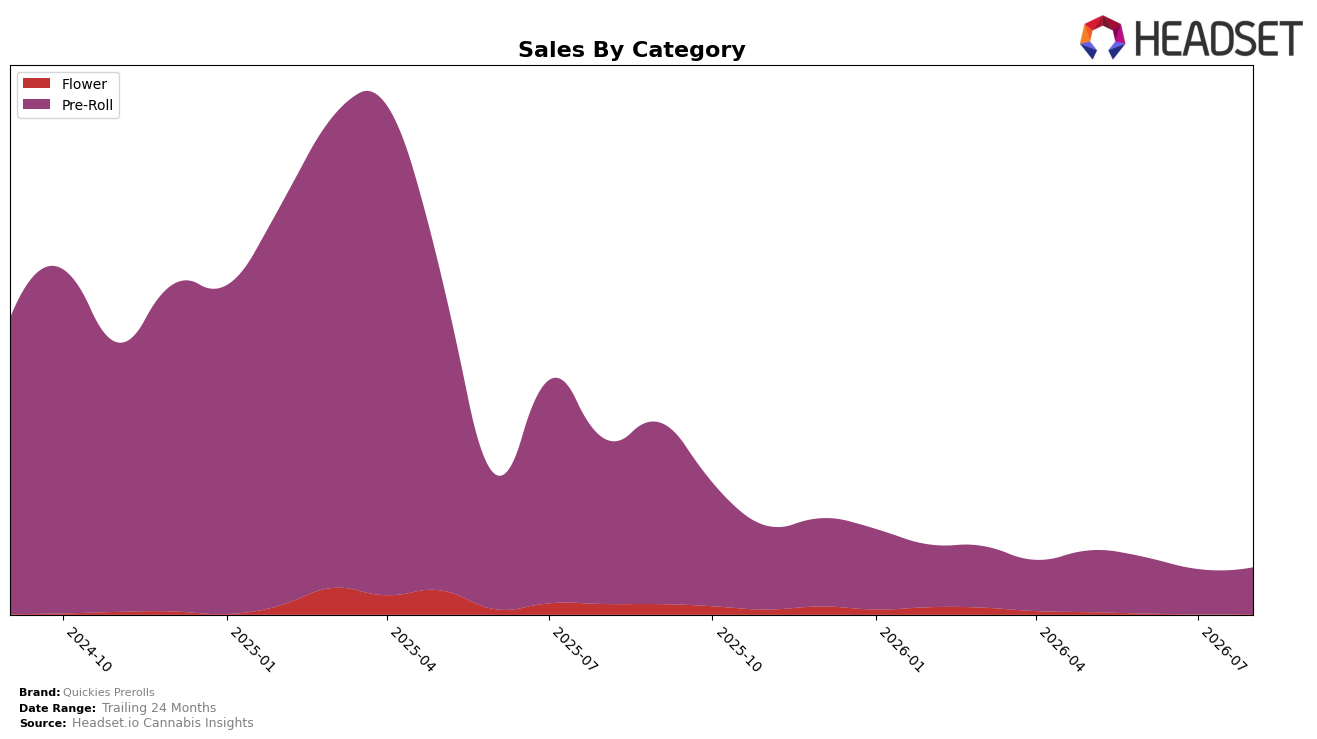
Quickies Prerolls concentrated 98.35% of August 2026 sales in Pre-Roll, with Flower at 1.65% share, indicating a narrowed category footprint as Pre-Roll fell 71.85% year over year while Flower declined 92.76% year over year. Month over month, Pre-Roll inched up 2.98% while Flower rebounded 101.87%, and the average price fell 24.04% year over year to $3.40, suggesting volume reliance at lower price points within a Pre-Roll-heavy mix. The pattern implies a category dependency where modest Pre-Roll stabilization offsets a much smaller but more volatile Flower line, narrowing strategic flexibility.
Within this context, the brand’s Pre-Roll rank position at 49 in Maryland places Quickies Prerolls below many peers, and the 2.98% month-over-month Pre-Roll gain contrasts with the much steeper 71.85% year-over-year contraction. The combination of a 24.04% price decrease and 98.35% category concentration points to a value-led positioning that may win incremental units short term but risks sustained share loss if year-over-year declines persist at the current -73.13% brand level. The pattern implies the brand is competing primarily on price within Pre-Roll and using Flower as a small, high-variance adjunct rather than a diversification engine.
Competitive Landscape
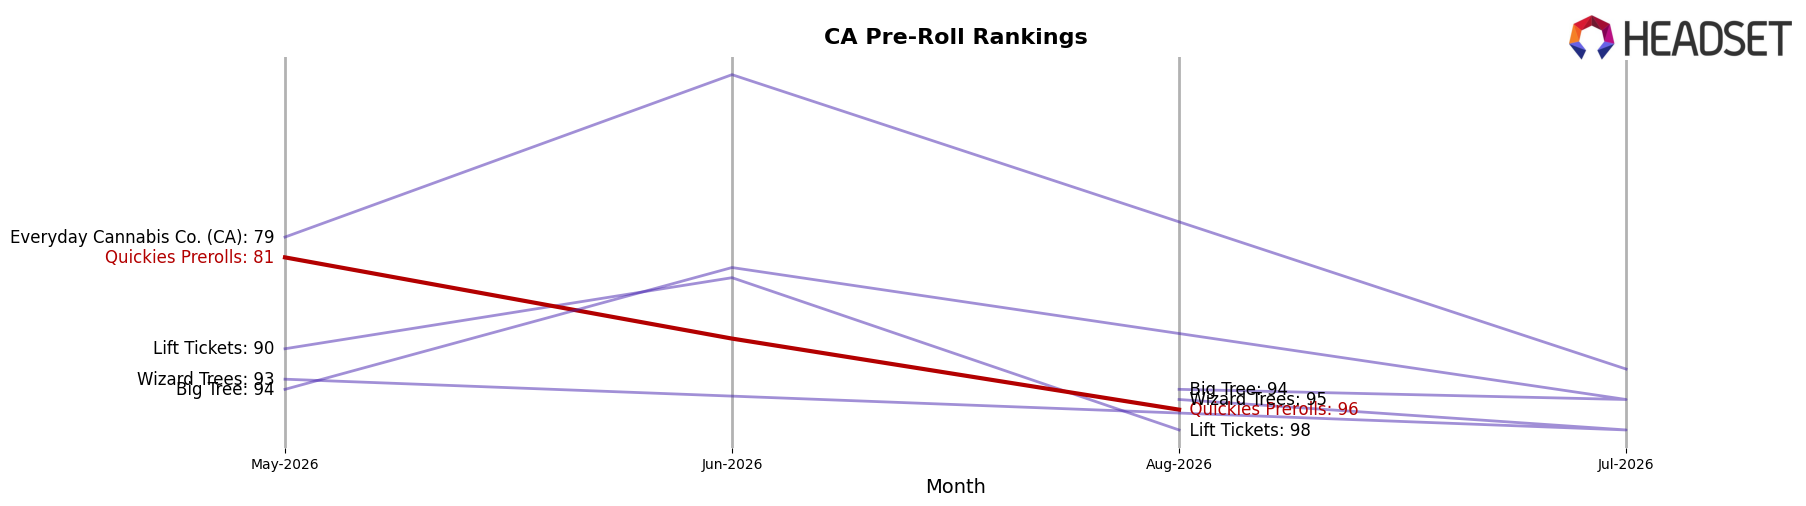
Quickies Prerolls sits at rank #96 in CA Pre-Roll for August 2026, sliding 60 positions from rank #36 year over year while also dropping 15 spots from #81 since May 2026; relative to its April 2025 peak at #11, this marks an 85-rank retreat. At the top end, Jeeter holds #1 with a 5.6% year-over-year sales increase and STIIIZY holds #2 with a 10.2% gain, indicating that Quickies Prerolls is losing rank faster than leaders are expanding share, and the trajectory implies the brand is ceding long-term shelf visibility unless it reverses multi-quarter slippage.
Notable Products
The steepest movement in August 2026 was the Sativa Pre-Roll (1g), which fell 17.36% MoM to rank 3 while the Sativa Diamond Infused Pre-Roll (1g) also declined 11.98% at rank 4, indicating a pullback in sativa-led demand; by contrast, Indica Pre-Roll (1g) grew 6.45% to hold rank 1 and Hybrid Pre-Roll (1g) jumped 23.44% to rank 2. Four of the top ten are diamond-infused SKUs, yet three of those posted declines between 9.04% and 15.05% while non-infused core SKUs rose by 6.45% to 23.44%, implying the value tier is outperforming enhanced formats. Gorilla Glue Infused Pre-Roll (1g) was a positive outlier at rank 7 with 23.79% MoM growth while Cherry Pie THCA Diamond Infused Pre-Roll (1g) dropped 15.05% at rank 8, suggesting flavor-led infused bets require tighter curation even as one SKU can still scale. The pattern implies Quickies Prerolls is leaning toward reliable Indica and Hybrid anchors while selectively pruning underperforming infused variants to protect share and margin mix.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

