

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Lime is stocked at 175 licensed dispensaries across California, with the deepest coverage in Los Angeles, San Diego, Sacramento, San Jose, and Modesto. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
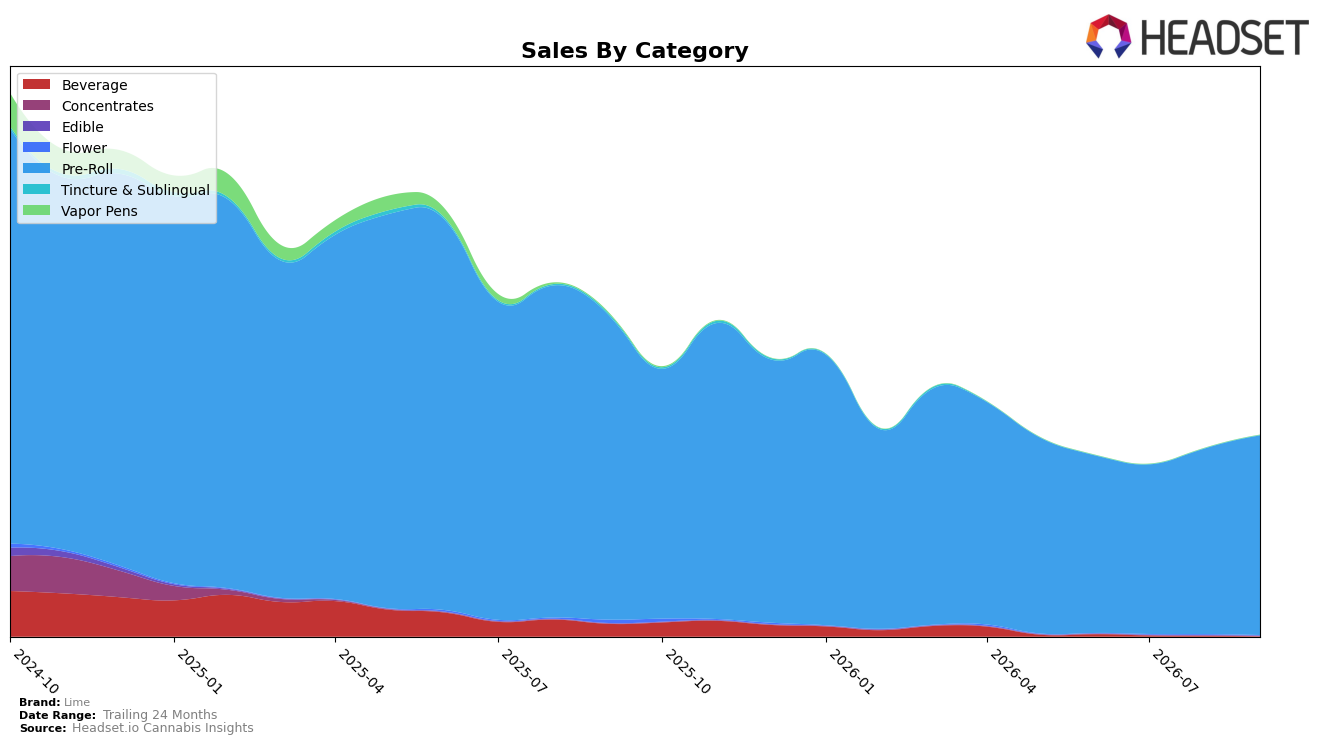
Lime’s mix in September 2026 is almost entirely Pre-Roll, with Pre-Roll at 99.96% share and ranked 24 in California, while Beverage has fallen to 0.04% share; within this, Pre-Roll sales were down 34.59% year over year but up 7.55% month over month, and Beverage declined 99.29% year over year and 83.78% month over month. Despite a 23.77% year-over-year drop in average price to $11.83, overall brand sales fell 38.14% year over year and 63.85% over 24 months, implying that price cuts stabilized Pre-Roll momentum month over month but did not offset the multi-year contraction or the near-elimination of Beverage.
The consolidation into Pre-Roll at 99.96% share alongside a California category rank of 24 indicates a narrowed competitive lane that gained short-term traction with a 7.55% month-over-month uptick, while the Beverage collapse to 0.04% share removes cross-category buffering and leaves pricing as the primary lever after a 23.77% year-over-year average price reduction. This pattern implies Lime is competing on depth rather than breadth: reliance on Pre-Roll could sustain incremental monthly gains, but with brand sales still down 38.14% year over year and 63.85% over 24 months, the positioning requires either further mix expansion or premiumization within Pre-Roll to improve rank mobility and reduce exposure to single-category volatility.
Competitive Landscape
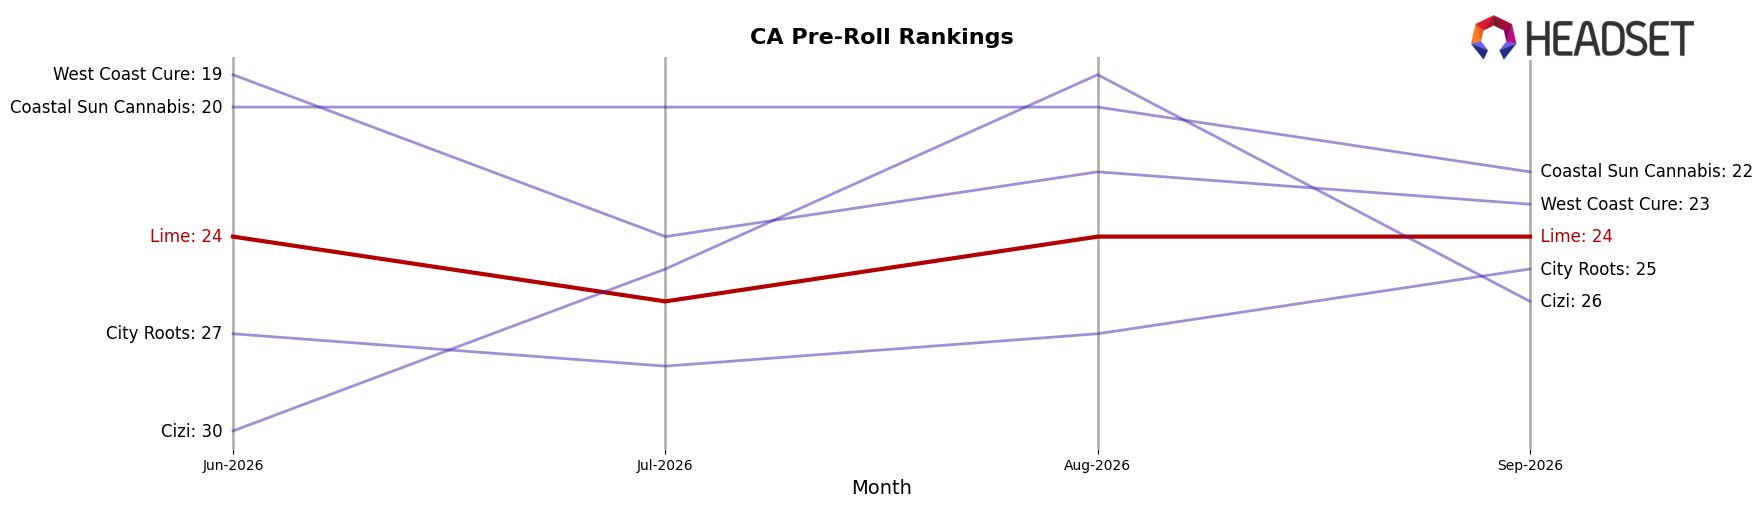
In September 2026, Lime ranks #24 in CA Pre-Roll, down 13 positions year over year from #11, and flat versus June 2026 at #24, while the brand’s peak of #9 in December 2024 marks a 15-rank slide from its high; by contrast, Jeeter holds #1 with a +1 YoY rank change alongside +16.0% YoY sales, and Claybourne Co. advanced to #4 from #6 with +19.3% YoY sales, indicating Lime’s multi-quarter stagnation at #24 and double-digit YoY rank erosion signal share loss to brands improving both placement and velocity.
Notable Products
Blue Dream Live Resin Infused Pre-Roll (1.75g) delivered the month’s sharpest move with a 59.3% MoM gain to rank 3, while Lil Limes - Maui Wowie Live Resin Hash Infused Pre-Roll 5-Pack (3g) fell 13.9% MoM to rank 7. Lil' Lime - Purple Zaza Diamond And Hash Infused Pre-Roll (0.6g) climbed 53.8% MoM to seize rank 1, and two single-count SKUs now sit in the top three as the 5-pack format slips from rank 6 to rank 7. With all top-10 entries concentrated in Pre-Roll and multiple mini formats rising while a key 5-pack retreats, the mix points to a pivot toward single-serve and flavor-led trial over bulk multipacks for September 2026.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

