


Where to Buy
RR Brothers is stocked at 13 licensed dispensaries across Arizona and Oklahoma, 9 of them in Arizona, with the deepest coverage in Phoenix, Mesa, Buckeye, El Mirage, and Guadalupe. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
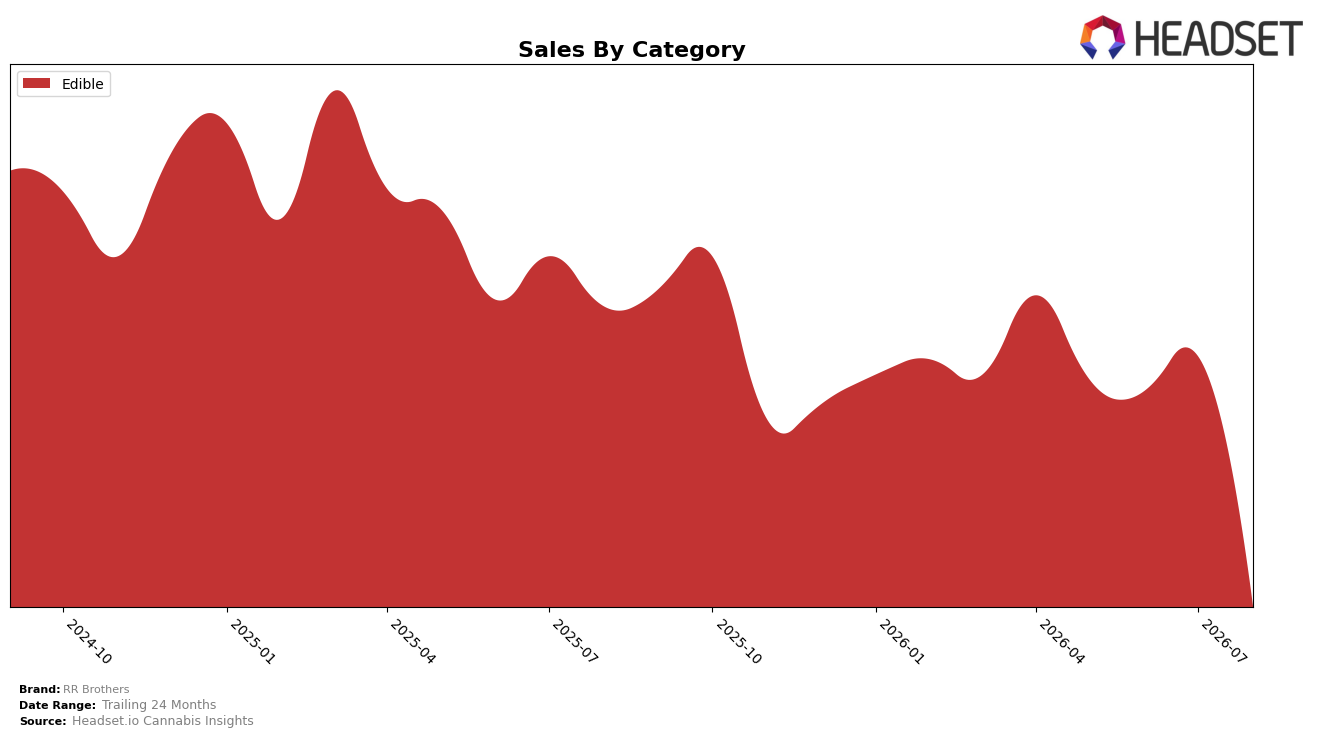
In August 2026, RR Brothers operated as a single-category brand with Edible accounting for 100.0% of sales, while Edible sales declined 82.9% year over year and 80.1% month over month. Average price in Edible reached $16.96 alongside a 29.7% YoY increase, indicating mix or pack-size shifts even as total brand sales contracted 82.9% YoY; with no reported rank in Arizona Edible, the absence of a rank change coupled with a full-category concentration implies volume erosion outpaced price gains and left the brand outside visible tiering.
The consolidation into a 100.0% Edible mix, combined with an 80.1% MoM contraction and a 29.7% YoY price rise, implies RR Brothers is positioned as a narrower, higher-price offer that is surrendering velocity faster than pricing can compensate. Given the lack of a reported rank in Arizona and an 82.9% YoY sales decline, the pricing and assortment stance likely restricts trial and repeat, suggesting that regaining distribution or introducing lower-price or value-oriented formats would be necessary to re-enter competitive visibility within Edible.
Competitive Landscape
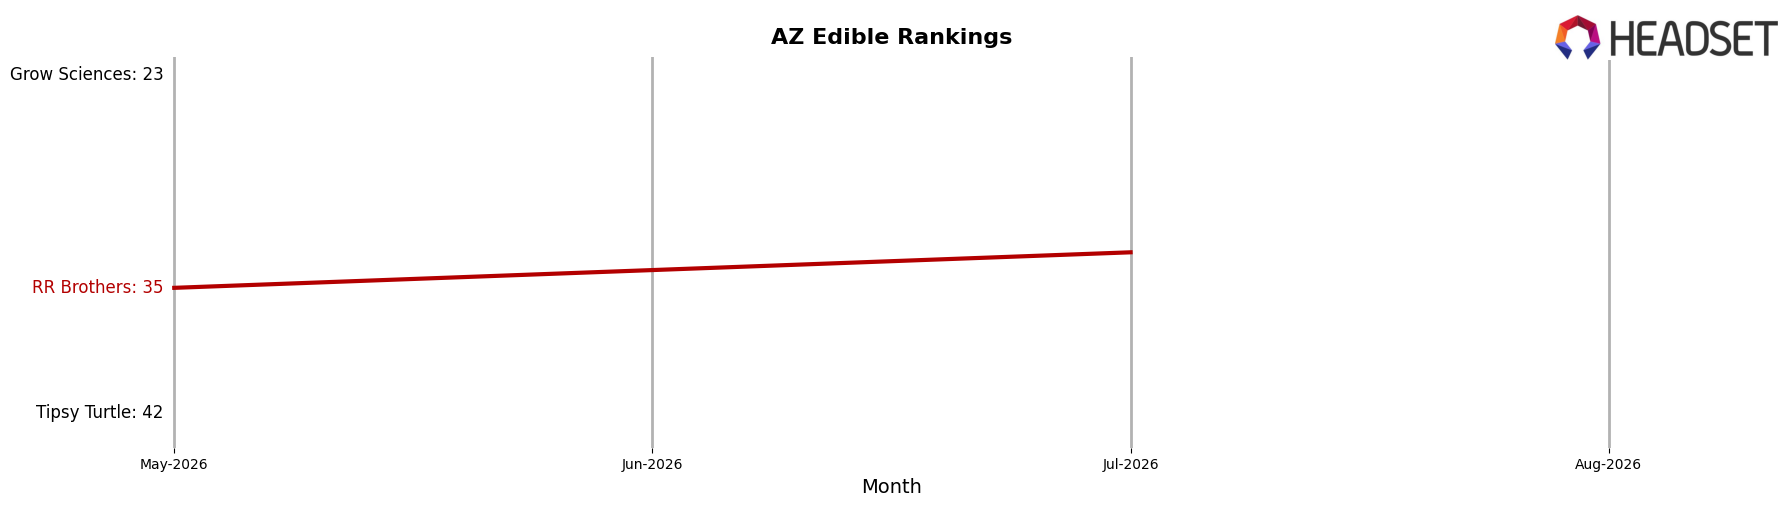
RR Brothers sits at rank #42 in AZ Edible in August 2026, down 13 positions year over year from #29, and 7 spots below its May 2026 rank of #35, while still trailing its October 2024 peak at #24; this contrasts with Wyld holding #1 despite a 19.2% year-over-year sales decline and OGEEZ steady at #2 with a 2.8% year-over-year increase, indicating that category leaders can maintain top ranks even amid contraction. The three-month slide from #35 to #42 alongside a 13-place year-over-year drop points to share erosion in mid-shelf slots as Baked Bros remains #3 with 9.5% year-over-year sales growth versus RR Brothers’ downward rank trajectory; the pattern implies RR Brothers must arrest sequential rank losses to avoid further displacement by competitors that are either growing low double digits or defending top-5 positions despite declines.
Notable Products
Blueberry Cream Gummies 10-Pack (100mg) posted the steepest decline, dropping 86.4% month over month to rank 5, while Indica Blueberry Gummies (100mg) fell 90.2% to rank 6. CBD/THC/CBN/CBG 1:1:1:1 Peach Mango Gummies (100mg CBD, 100mg THC, 100mg CBN, 100mg CBG) slid 68.4% MoM yet held rank 1, as CBD/THC/CBG 1:1:1 Orange Cream Gummies (100mg CBD, 100mg THC, 100mg CBG) declined 73.5% at rank 2. Eight of the top ten are Edible SKUs, and two high-rank cannabinoid-ratio gummies lost over 68%, indicating demand rotation within the same category rather than a shift to other form factors. The pattern implies a pricing or distribution reset in August 2026 that compressed volume across Edible leaders without changing the brand’s category focus.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

