

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
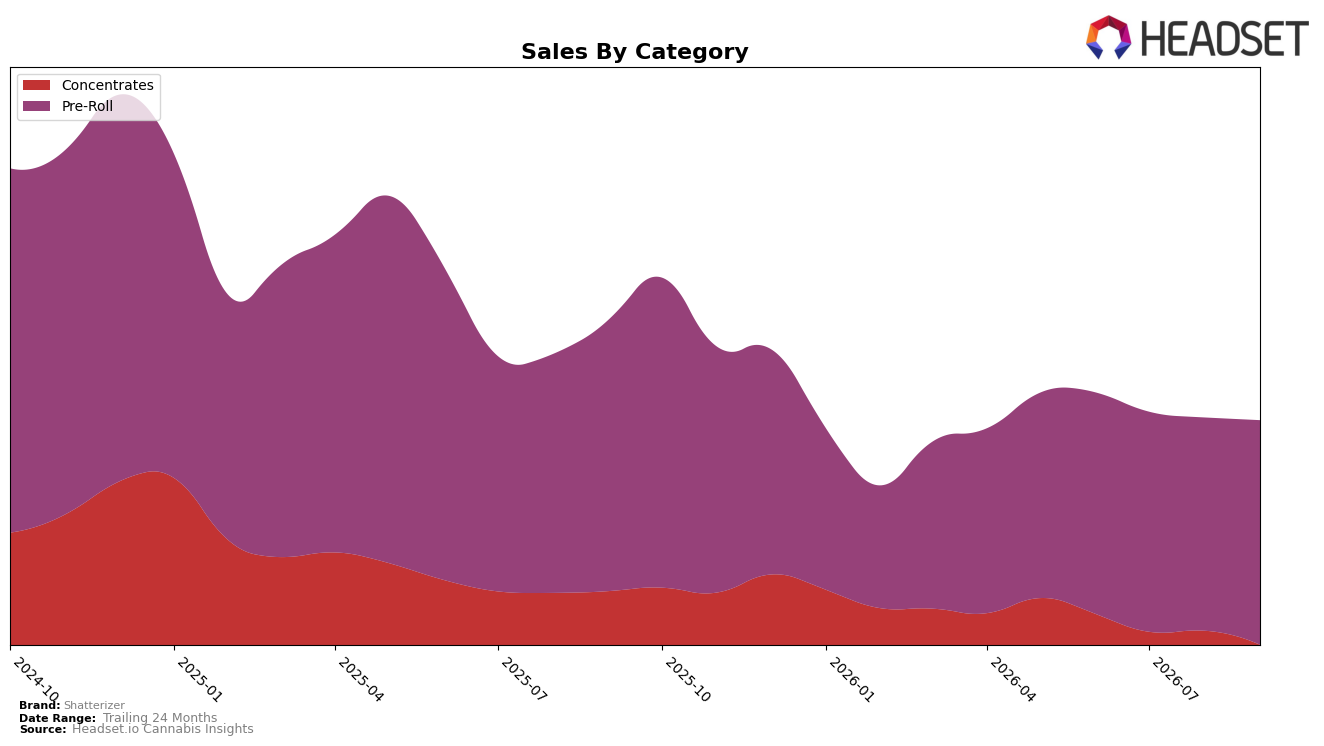
In September 2026, Shatterizer concentrated 79.91% of sales in Pre-Roll with a 3.93% month-over-month lift but a 13.44% year-over-year decline, while Concentrates held 20.09% share with a 15.70% month-over-month drop and a 41.60% year-over-year fall; against this mix, total brand sales were down 21.09% year over year and average price rose 7.97%. Within its focal category, Shatterizer sat at rank 47 in Pre-Roll in Ontario, and its average Pre-Roll price of $19.70 contrasted with Concentrates at an average price of $27.39; the pattern implies the brand is leaning harder into Pre-Roll momentum to offset Concentrates contraction while operating from a lower-tier ranking position that limits visibility.
The divergence—Pre-Roll up 3.93% month over month while Concentrates fell 15.70% month over month, and Pre-Roll down 13.44% year over year versus a 41.60% decline in Concentrates—signals a deliberate pivot toward value-accessible inhalables where price elasticity is tighter amid a 7.97% brand-wide price increase. Holding 79.91% mix in a category where the brand is ranked 47 in Ontario suggests that near-term gains depend more on incremental share capture within a crowded mid-pack than on breadth expansion, and the deeper 41.60% year-over-year slide in Concentrates indicates that further deprioritization of that segment could stabilize overall volatility but cap premium trade-up potential.
Competitive Landscape
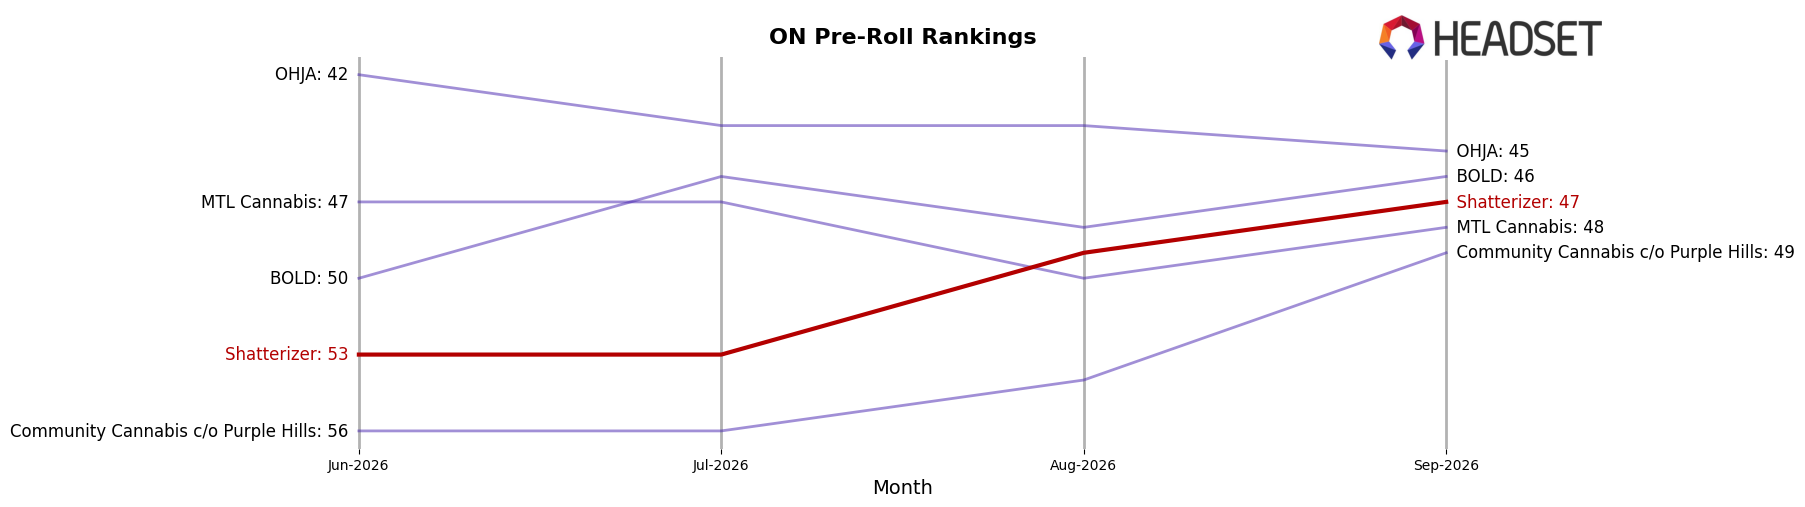
Shatterizer sits at rank #47 in ON Pre-Roll for September 2026, slipping 6 positions year over year from #41 while improving 6 spots versus June 2026 when it was #53; against this backdrop, Back Forty / Back 40 Cannabis rose from #2 to #1 with a 46.6% year-over-year sales increase, and General Admission fell from #1 to #2 with a 38.2% sales decline, indicating the top tier is reordering even as Shatterizer remains outside the top 40. With a historical peak at #27 in December 2024 and a current position of #47 alongside competitors like Spinach moving from #17 to #4 on 141.2% growth, the pattern implies Shatterizer’s downward YoY rank shift amid faster-rising peers will require share-capturing moves to avoid further relegation from high-visibility shelves.
Notable Products
Pink Gas Shatter Infused Pre-Roll (1g) posted the steepest decline at -36.18% and slid to rank 5, while Electric Grapefruit Shatter (1g) fell -22.99% to rank 10, indicating demand is rotating away from certain SKUs despite 8 Ball Kush Shatter Double Infused Pre-Roll (1g) holding rank 1 on a +5.50% lift. Four of the top ten are Pre-Roll formats ranked 1 through 6 except rank 7, and concentrates sit lower at ranks 7 and 10 with -12.23% and -22.99% MoM, implying mix is consolidating around infused Pre-Rolls rather than standalone concentrates. Rockstar Shatter Diamonds & Kief Infused Pre-Roll (1g) maintained rank 2 on +4.68% while Slurricane Double Infused Pre-Roll (1g) at rank 3 gained +8.86%, and Granddaddy Purple Shatter Infused Pre-Roll 5-Pack (2.5g) jumped +23.82% to rank 4 with approximately $73,363 in sales, pointing to multi-pack and infused formats anchoring share and guiding assortment toward high-rotation Pre-Roll variants.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

