

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
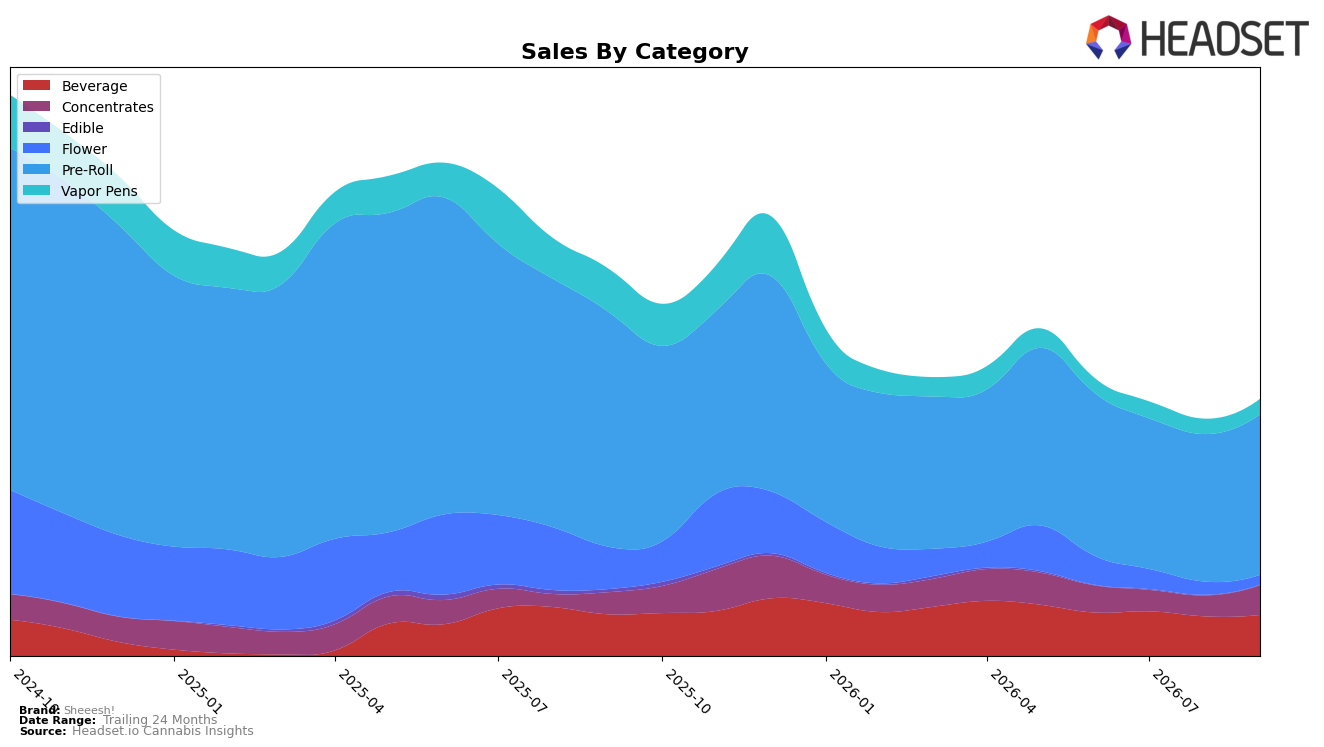
Sheeesh! concentrated 62.70% of September 2026 sales in Pre-Roll, up month over month by 8.89% but down year over year by 31.70%, while Beverage held 16.06% with a modest 3.47% MoM increase and a 1.60% YoY decline. The standout shift came from Concentrates at 11.52% mix, surging 43.01% MoM and 35.50% YoY, contrasted with Vapor Pens at 5.96% falling 64.53% YoY despite a 0.86% MoM uptick. Flower shrank to 3.70% share with a 26.26% MoM drop and a 77.50% YoY decline, and Edible contracted to 0.05% with a 60.69% MoM decline and a 95.15% YoY fall. Despite a -33.77% brand-level YoY downturn and a -21.83% YoY price reset to $14.43, the mix skews toward value-leaning Pre-Roll and momentum in Concentrates, indicating a shift from legacy inhalables toward higher-potency formats while de-emphasizing traditional Flower and Edible lines.
These mix moves reposition Sheeesh! toward a potency-and-convenience barbell: expanding Concentrates with a 35.50% YoY lift alongside a volume-priced Pre-Roll core at 62.70% share, while deprioritizing Flower with a 77.50% YoY drop and Edible with a 95.15% YoY decline. With Vapor Pens down 64.53% YoY and Pre-Roll rank at 64 in Ontario, the brand trades breadth for depth, implying resource allocation toward two lanes where price elasticity (Pre-Roll MoM +8.89%) and potency signaling (Concentrates MoM +43.01%) can lift throughput even as average prices reset, a positioning that prioritizes basket entry and potency-seeking repeats over flavor-led experimentation.
Competitive Landscape
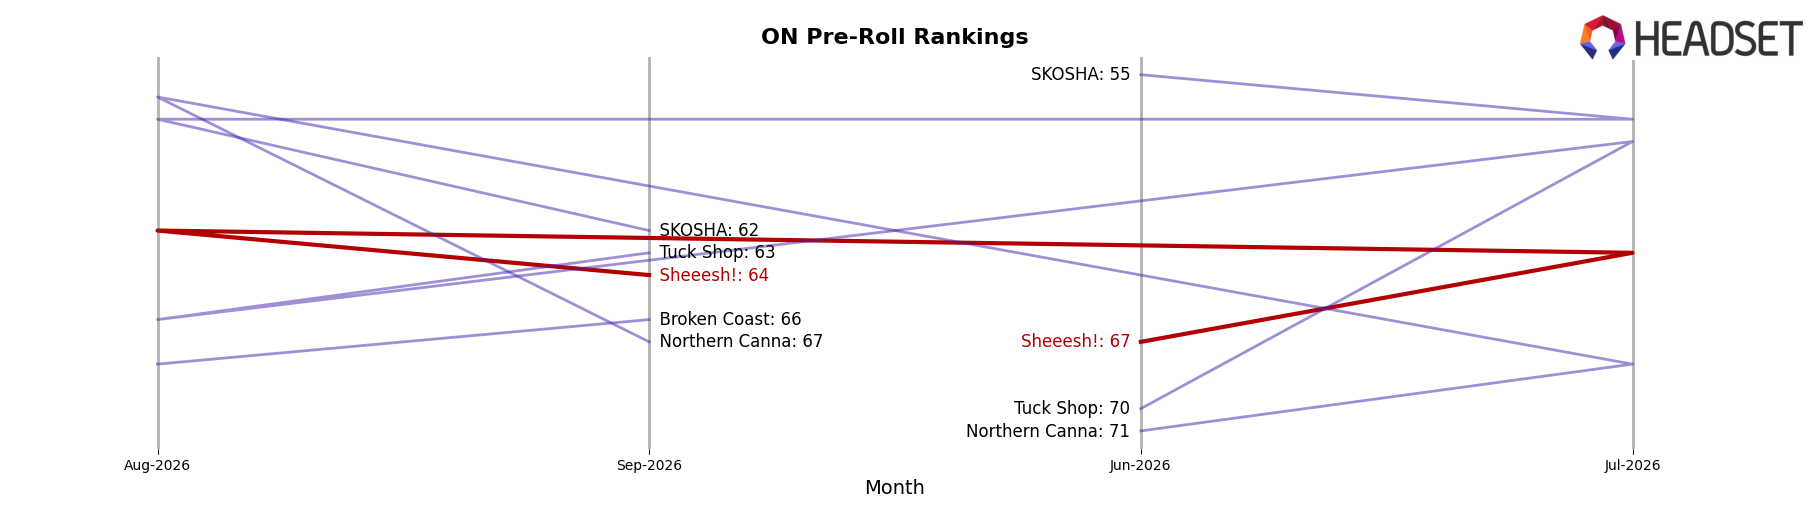
Sheeesh! is ranked #64 in ON Pre-Roll for September 2026, down 19 positions year over year from #45, and up 3 positions from its June 2026 rank of #67; the brand’s historical ceiling was #24 in September 2024, indicating a 40-position slide from peak to current. In contrast, Back Forty / Back 40 Cannabis moved from #2 to #1 while growing sales 46.6%, and General Admission slipped from #1 to #2 with a 38.2% sales decline, signaling that leadership is rotating at the top even as Sheeesh! drifts lower in the long arc. With Thumbs Up Brand advancing from #8 to #3 on 62.1% sales growth and Spinach jumping from #17 to #4 on 141.2% growth, Sheeesh!’s modest quarter-over-quarter uptick of 3 ranks does not offset its 19-rank annual decline, implying the brand is ceding relative share to faster-rising rivals and will need a structural change in assortment or velocity to avoid further mid-tier erosion.
Notable Products
Banjo Berry Rosin Strawberry Lemonade Soda (10mg THC, 12oz, 355ml) posted the steepest decline at -23.5% MoM while falling to rank 6, and Sheesh x Nugz - Neon Sunshine Live Rosin Happle Sm'Hash Soda (10mg THC, 355ml) slid -27.6% at rank 10, indicating beverage volatility even as Cherry D Live Rosin Cola (10mg THC, 12oz, 355ml) rose +30.8% to rank 2. SMRF Daredevil Dusted Infused Pre-Roll (1g) grew +25.5% while holding rank 1, whereas SMRF Distillate Infused Pre-Roll 5-Pack (2.5g) fell -21.8% at rank 8, with four of the top ten being Pre-Roll SKUs that split between single-stick gains and multipack weakness; this mix implies Sheeesh! is consolidating around premium singles rather than value packs as beverages pivot toward a single hero flavor.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

