

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
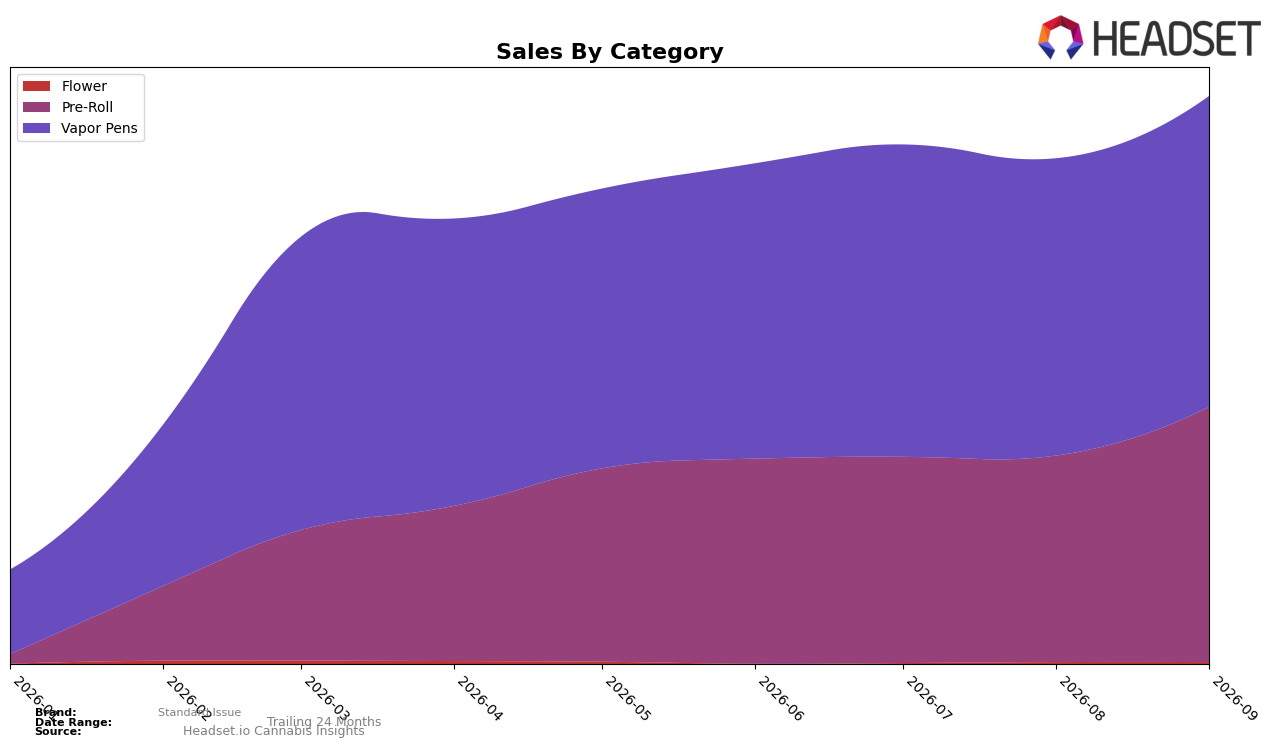
In September 2026, Standard Issue concentrated 54.31% of sales in Vapor Pens and 44.68% in Pre-Roll, with Flower at 1.01% share; monthly momentum diverged as Pre-Roll grew 23.14% MoM while Vapor Pens rose 4.58% MoM and Flower slipped 0.13% MoM. The Vapor Pens price point averaged $26.55 versus $17.97 in Pre-Roll, indicating mix is shifting toward a lower-price category even as the brand holds a top-category focus and a rank of 5 in Vapor Pens in British Columbia. The pattern implies near-term revenue is leaning on volume acceleration in Pre-Roll while maintaining Vapor Pens leadership, which could rebalance margin and share if the Pre-Roll surge sustains.
The mix tilt toward Pre-Roll (up 23.14% MoM) against a slower-growing Vapor Pens base (up 4.58% MoM) suggests elasticity-driven gains that may dilute average realized price relative to the $26.55 Vapor Pens and $24.84 Flower price anchors. With 54.31% share still in Vapor Pens and a category rank of 5 in British Columbia, the brand’s positioning remains premium-adjacent in form factor but increasingly reliant on a faster-turn, lower-price Pre-Roll engine at 44.68% share; this implies pricing and assortment need to defend Vapor Pens rank while converting Pre-Roll velocity into repeat share without eroding overall price architecture.
Competitive Landscape
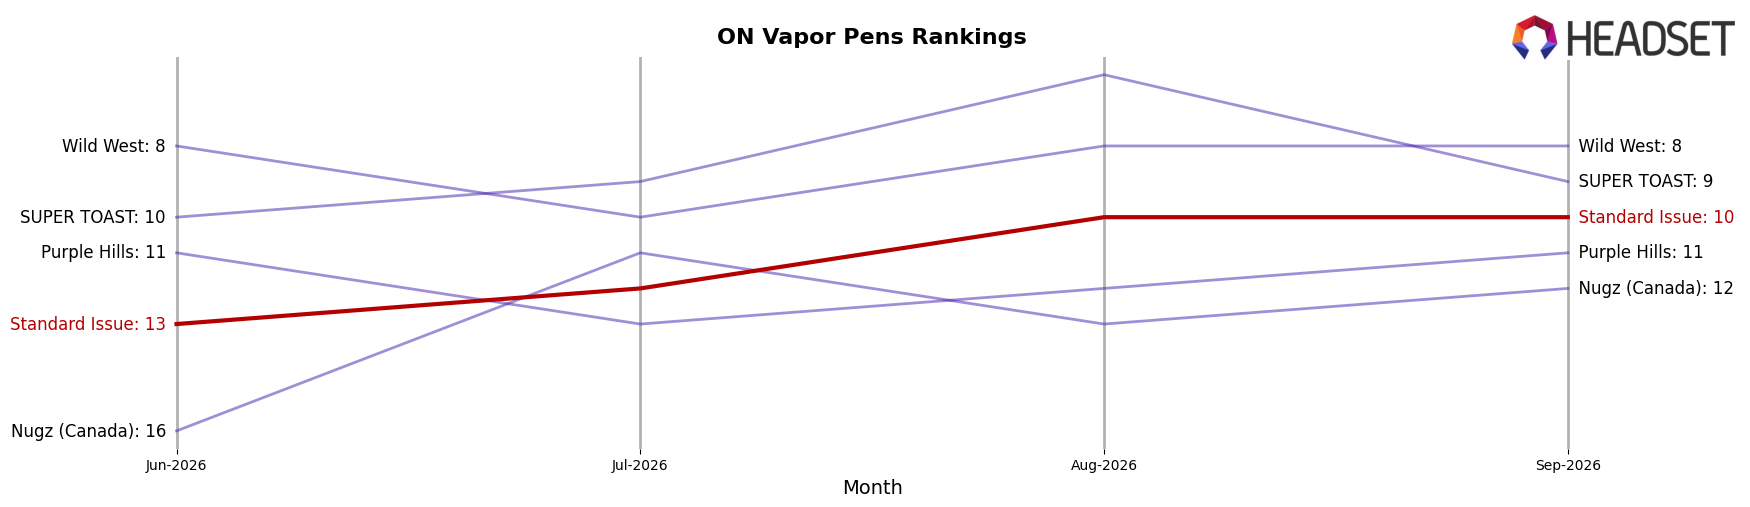
Standard Issue sits at rank #10 in ON Vapor Pens in September 2026, up 3 positions from #13 in June 2026, while also hitting its peak rank of #10 in September 2026; by contrast, Spinach holds #1 after a year-over-year climb of 4 ranks with 172.5% sales growth, and BoxHot is #3 after a 2-rank gain paired with 19.9% growth. Meanwhile, General Admission sits at #4 after a 3-rank lift despite an 12.0% sales decline, and Kolab advanced to #5 from #14 alongside 93.0% growth, indicating that Standard Issue’s recent 3-rank quarter-on-quarter rise places it among climbers but below the pace of top movers, implying the trajectory is improving but needs accelerated gains to break into the top 5.
Notable Products
The sharpest movement came from Watermelon Infused Pre-Roll 5-Pack (2.5g), up 17.3% month over month to rank 8 while Strawberry Lemonade Distillate Cartridge (1g) rose 22.2% at rank 1, signaling momentum consolidating at both the top and mid-tier. Wild Berry Distillate Cartridge (1g) slipped 3.4% at rank 2 as Grape Distillate Cartridge (1g) declined 5.6% at rank 10, yet Vapor Pens still hold three of the top ten while Pre-Rolls account for six of the top ten. With four Pre-Roll multipacks in the top ten and two of them posting double-digit gains, the mix points to multipack Pre-Rolls pulling share from single-stick formats even as a flagship 1g cartridge anchors revenue at $550,407. The pattern implies Standard Issue is tilting toward value-driven, flavored multipacks while maintaining a premium cartridge leader to stabilize category breadth.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

