

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
The Lab Concentrates is stocked at 17 licensed dispensaries across Ohio and Nevada, 14 of them in Ohio, with the deepest coverage in Bowling Green, Bridgeport, Chillicothe, Cincinnati, and Eastlake. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
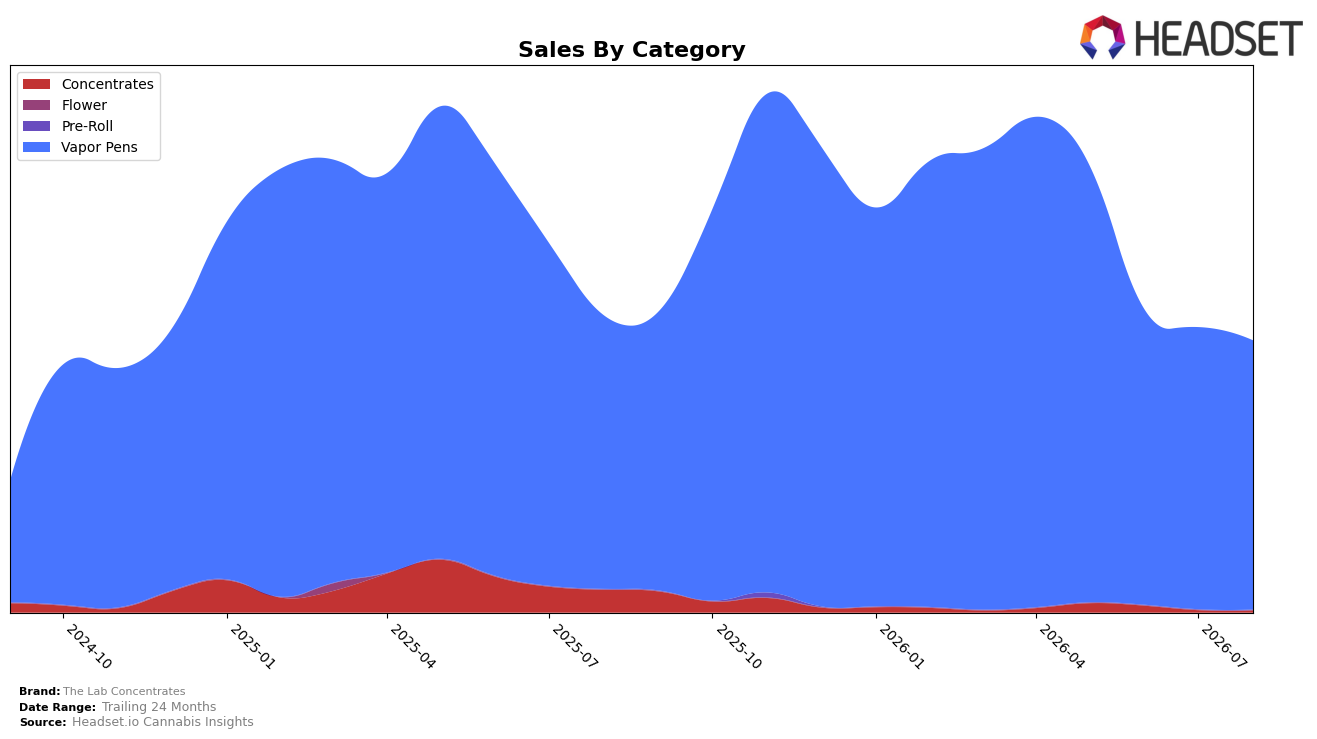
In August 2026, The Lab Concentrates derived 99.36% share from Vapor Pens with a month-over-month decline of 4.60% and a year-over-year decline of 1.59%, while the much smaller Concentrates line held 0.64% share with steeper month-over-month contraction of 14.64% and a year-over-year drop of 92.22%. Despite an average price decrease of 5.19% year over year to $28.15, total brand sales fell 8.45% year over year, and the Vapor Pens average price of $28.10 contrasted with Concentrates at $38.08. The pattern implies a category mix locked into Vapor Pens exposure where price cuts did not offset unit softness, and the Concentrates SKU base is shrinking to a token share that no longer contributes meaningful diversification.
Within Vapor Pens, The Lab Concentrates held rank 42 in Ohio, and with Vapor Pens at 99.36% share versus 0.64% for Concentrates, even moderate headwinds in the lead category transmit almost one-for-one to brand performance. With brand sales up 74.19% over 24 months but down 8.45% year over year, and Vapor Pens down 4.60% month over month while Concentrates fell 14.64%, the short-term slope is negative despite longer-term scale. The implication is that current positioning is a narrow single-category play that limits resilience to monthly demand swings and price compression, and shoring up rank in Ohio Vapor Pens or rebuilding a minimally viable Concentrates mix would be required to stabilize momentum.
Competitive Landscape
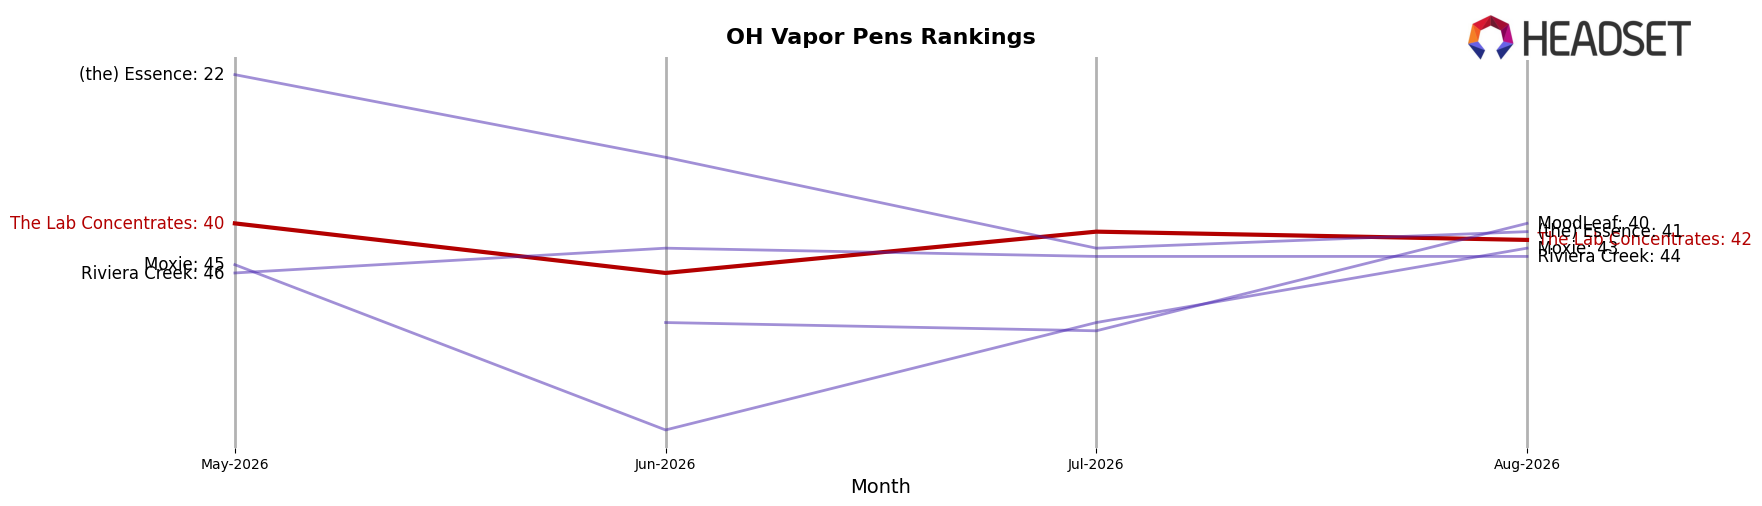
The Lab Concentrates sits at rank #42 in Ohio Vapor Pens for August 2026, down 3 positions from #39 year over year and 2 spots from #40 in May 2026, while still 17 places below its peak at #25 from November 2025; in contrast, Rove climbed from #10 to #3 with an 84.6% YoY sales increase and Certified (Certified Cultivators) held #1 with a 68.2% YoY lift, indicating that share is consolidating at the top as The Lab Concentrates drifts from the top 30. This combination of a 3-rank YoY drop and a 2-rank slide versus three months prior, alongside competitors moving up 7 positions and maintaining #1, implies a trajectory toward lower visibility unless distribution or product cadence resets the rank trend.
Notable Products
24K Gold Punch Distillate Disposable (0.5g) posted the steepest decline in August 2026 at -52.6% and slid to rank 9, while Maui Wowie Distillate Cartridge (1g) dipped -3.1% at rank 6, contrasting with modest gains of +2.1% for Alien Technology Distillate Disposable (0.5g) at rank 1 and +2.4% for Northern Lights Distillate Cartridge (1g) at rank 4. The top ten is fully concentrated in Vapor Pens, with four disposables and six cartridges in the mix, and the lone sharp drop in a disposable suggests format risk concentrated in budget-oriented SKUs rather than a category-wide issue. With Alien Technology Distillate Disposable (0.5g) holding rank 1 on a small +2.1% uptick and Northern Lights Distillate Cartridge (1g) advancing +2.4% inside the top five, leadership is consolidating around a few evergreen SKUs while middle-tier items absorb volatility. This pattern implies The Lab Concentrates is tilting toward sustaining high-velocity leaders in cartridges and select disposables while pruning underperforming disposable variants, redirecting attention to formats with steadier rank retention.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

