
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Triple Seven (777) is stocked at 98 licensed dispensaries across Maryland, New Jersey, and 7 other states, 28 of them in Maryland, with the deepest coverage in Baltimore, Columbia, Edgewater, Aberdeen, and Bethesda. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
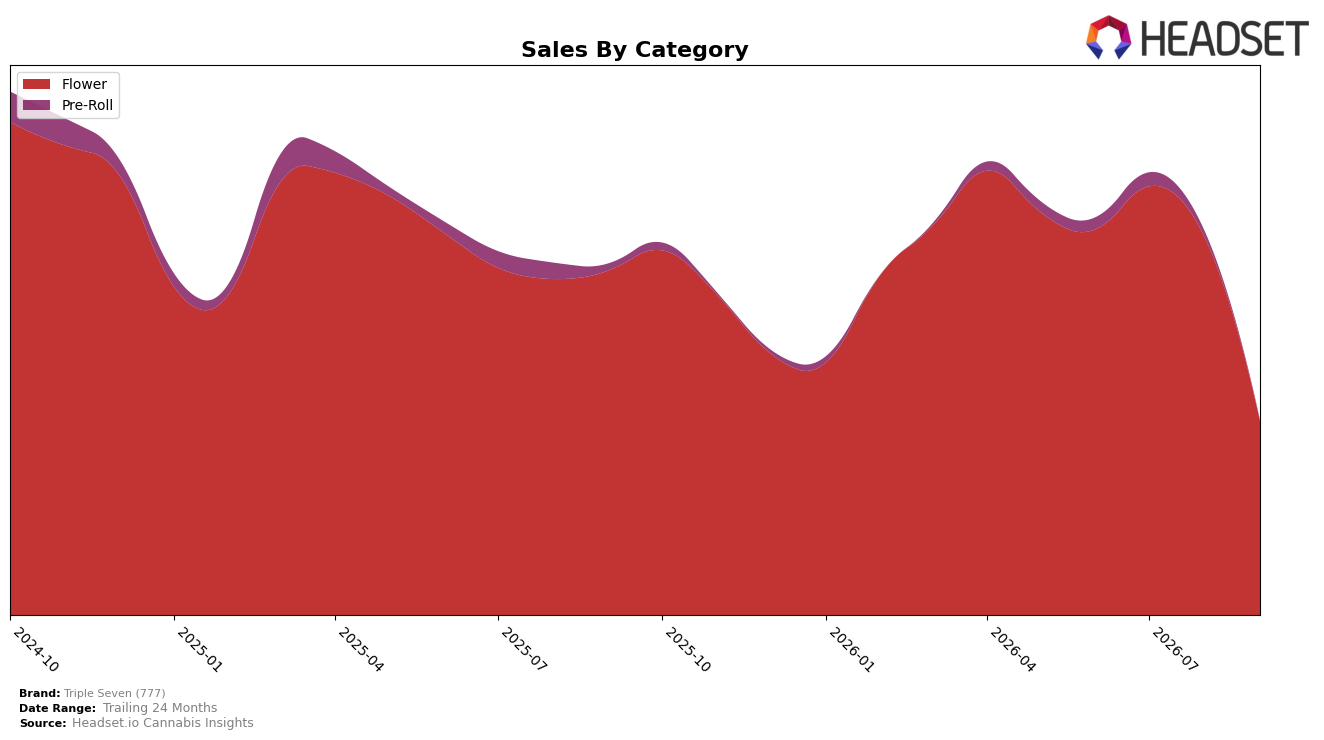
Triple Seven (777) concentrated 93.11% of September 2026 sales in Flower and 6.89% in Pre-Roll, with Flower down 42.13% year over year and 47.03% month over month while Pre-Roll declined 26.56% year over year and 23.76% month over month. Average price fell 12.89% year over year to $24.90 even as Flower’s category-specific price sat at $29.55, implying mix and promotional pressure; the brand’s overall sales contracted 41.27% year over year in the same period. The pattern implies overexposure to Flower is amplifying both the month-over-month volatility and the year-over-year contraction, with Pre-Roll too small at 6.89% share to buffer a 47.03% month-over-month pullback in the core.
Within Colorado Flower, a rank of 7 paired with a 42.13% year-over-year decline and a 47.03% month-over-month drop signals mid-tier shelf presence under pressure as price moves down 12.89% year over year. The 6.89% Pre-Roll mix, declining 26.56% year over year, is not yet positioned to offset Flower exposure or drive trading down from $29.55 to $7.97 effectively. The implication is that Triple Seven (777) is operating as a Flower-led brand competing on price while ceding stability, and needs either a higher-share subcategory to absorb month-over-month shocks or a pricing architecture that converts rank 7 visibility into steadier share despite category-wide compression.
Competitive Landscape
Triple Seven (777) sits at rank #7 in CO Flower in September 2026, down 2 positions from #5 year over year and sliding 4 spots from #3 in June 2026, while its historical peak was #2 in November 2024; meanwhile, Green Label Cannabis held at #1 year over year with sales up 38.0%, and In The Flow advanced from #12 to #5 on 113.5% YoY growth, indicating that Triple Seven (777)’s relative decline is less about category contraction and more about share being captured by faster-rising peers.

Notable Products
Appalacia White (14g) registered the steepest decline in September 2026, down 18.3% month over month while sliding to rank 4, and Freeworld Orange (14g) fell 32.3% MoM at rank 2; in contrast, Dirty Squirt Pre-Roll (1g) jumped 37.8% MoM at rank 3. With Flower occupying 8 of the top 10 spots and Honey Child (3.5g) holding rank 1 with a modest 2.2% MoM gain, the portfolio is concentrated in larger-format Flower even as single Pre-Rolls begin to accelerate. The mix implies Triple Seven (777) is leaning on high-volume Flower for scale while testing demand elasticity in Pre-Rolls to diversify velocity without ceding premium shelf ranks.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

