

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Seed & Strain Cannabis Co. is stocked at 140 licensed dispensaries across Ohio, Maryland, and 8 other states, 44 of them in Ohio, with the deepest coverage in Cincinnati, Columbus, Dayton, Aberdeen, and Bedford. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
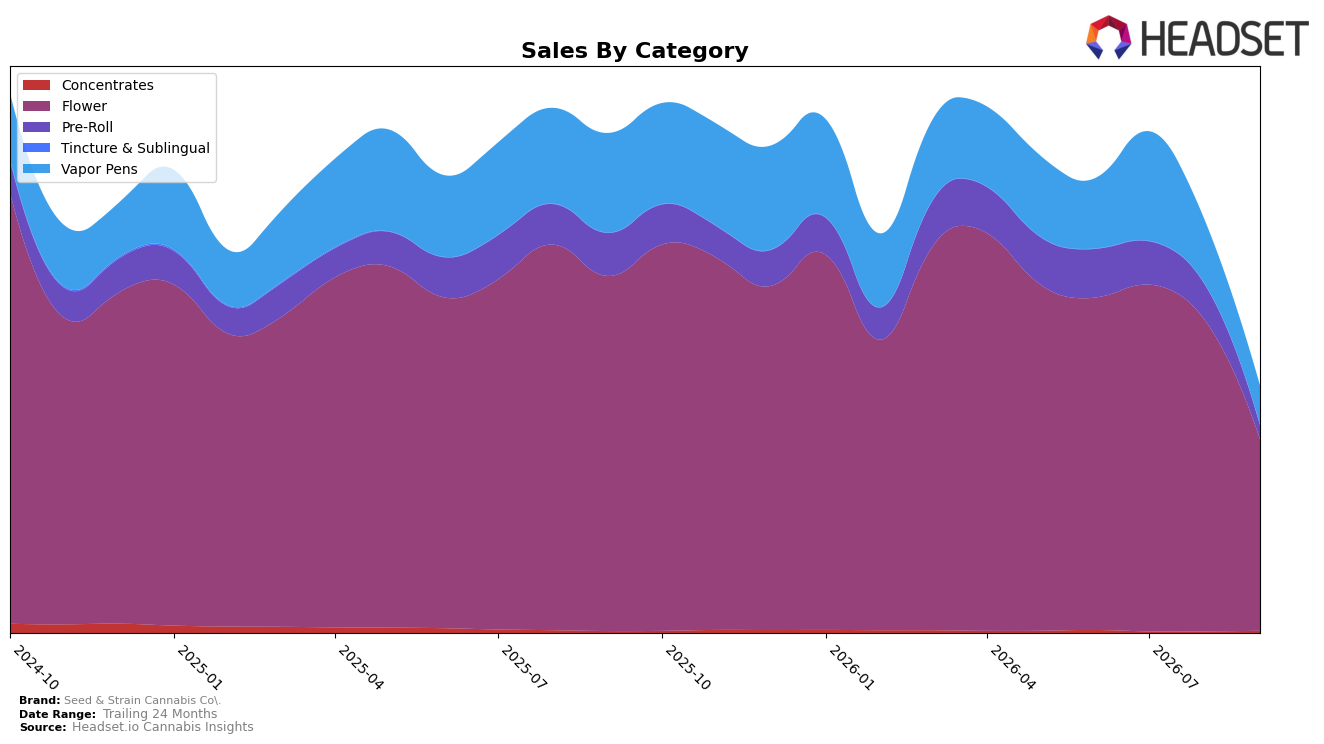
Seed & Strain Cannabis Co.’s category mix in September 2026 concentrated 77.78% share in Flower with year-over-year decline of 46.11% and month-over-month decline of 38.56%, while Vapor Pens held 15.85% share with steeper year-over-year decline of 60.70% and month-over-month decline of 38.68%. Pre-Roll accounted for 5.57% share with year-over-year down 67.86% and month-over-month down 61.16%, whereas Concentrates, at 0.79% share, moved counter to the rest with year-over-year growth of 14.45% and month-over-month growth of 46.85%. With brand-level sales down 50.67% year over year and average price up 7.55%, the widening declines in Vapor Pens and Pre-Roll versus Flower imply a portfolio tilt toward higher-price Flower and a smaller but rising Concentrates niche that could stabilize mix volatility.
The shift—heavier dependence on Flower despite rank 4 in Colorado Flower and simultaneous contraction in Vapor Pens and Pre-Roll—suggests margin and positioning are increasingly anchored in premiumized Flower rather than volume-led inhalables. The 46.85% month-over-month growth in Concentrates alongside a 38.56% month-over-month decline in Flower indicates consumers at the margin are trading into potency-driven formats even as the core Flower base remains large; this pattern implies an opportunity to defend Flower rank while reallocating activation toward Concentrates as a counter-cyclical buffer against double-digit declines in the two other inhalable segments.
Competitive Landscape
Seed & Strain Cannabis Co. sits at rank #4 in Colorado Flower for September 2026 after a YoY rise from #2 to #4 and a 3-month slide from #1 to #4, with its peak at #1 in August 2026; by contrast, Green Label Cannabis held #1 with a YoY position of #1 and +38.0% sales growth, while Good Chemistry Nurseries advanced to #2 from #3 YoY with +45.5% sales and Green Dot Labs moved to #3 from #4 YoY with +33.4% sales; even In The Flow climbed to #5 from #12 YoY alongside +113.5% sales, indicating competitive pressure concentrated above and immediately below #4. The pattern implies Seed & Strain Cannabis Co.’s brief peak in August 2026 did not convert into defended share, and the September 2026 rank indicates near-term vulnerability to upward pressure from #5 and sustained outperformance by the top three.

Notable Products
Crazen (14g) posted the steepest September 2026 movement with a -62.7% month-over-month drop and slid to rank 2, while Secret Snax (14g) also contracted by -55.4% and held rank 9; together these declines indicate demand consolidation rather than broad category weakness. Banana Rama (14g) led the lineup at rank 1 with outselling peers by a clear margin, and Pink Burst (14.15g) at rank 6 was the only SKU above $200,000 in sales, suggesting volume is pooling around fewer hero packs even as mid-tier ranks 3–5 cluster closely. With all top-10 entries sitting in Flower and four of the top six in 14g pack sizes, the mix points to a deliberate emphasis on large-format Flower that concentrates share at the very top while pruning underperforming SKUs.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

