

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeWhere to Buy
Western Cultured is stocked at 93 licensed dispensaries across Washington, with the deepest coverage in Seattle, Everett, Tacoma, Spokane, and Vancouver. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
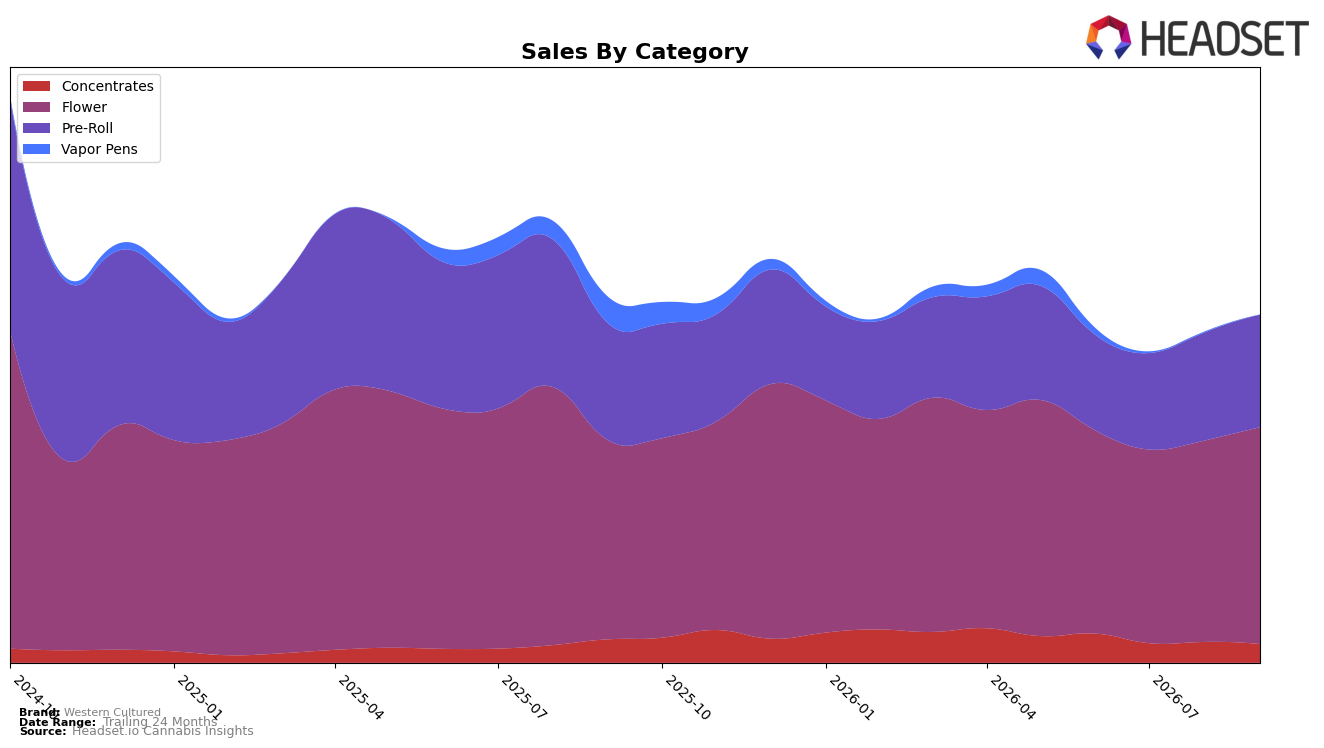
Western Cultured’s mix in Washington centered on Flower at 62.33% share, with category sales up 8.97% year over year and 7.70% month over month in September 2026, while average brand price fell 16.15% YoY to $14.89. Pre-Roll held 32.30% share with a 3.98% MoM lift but a 3.81% YoY decline, and Concentrates slipped to 5.35% share with a 10.23% MoM drop and 20.31% YoY decline; Vapor Pens effectively exited at 0.03% share with -99.66% YoY and -88.06% MoM. With total brand sales down 4.80% YoY but Flower expanding and Pre-Roll stabilizing, the pattern implies a deliberate shift toward volume-led inhalables while pruning underperforming form factors.
These shifts position Western Cultured as a Flower-anchored brand competing on unit velocity rather than premium price, evidenced by Flower growth alongside a lower average price and a rank of 43 in Washington Flower. The contraction in Concentrates (−20.31% YoY) and the Vapor Pens retreat (−99.66% YoY) reallocate share toward core combustion formats, suggesting focus on breadth within Flower and Pre-Roll to regain scale despite a 35.04% 24-month sales decline and only a 3.98% MoM lift in Pre-Roll; the implications are tighter SKU prioritization and pricing that trades margin for share to improve rank trajectory from position 43.
Competitive Landscape
Western Cultured sits at rank #43 in WA Flower in September 2026, a 2-place improvement from #45 year over year, while edging up 4 positions from #47 in June 2026; this contrasts with Mama J's moving from #4 to #3 year over year and Hemp Kings leaping from #24 to #5. Despite a historical peak at #29 in September 2024, the current #43 marks a 14-rank slide from that peak even as near-term momentum turned positive by 4 ranks quarter-over-quarter; paired with Phat Panda holding #1 both this year and last, the pattern implies Western Cultured is stabilizing off-peak but needs step-change gains to reenter the top 30.

Notable Products
Wedding Cake Pre-Roll 2-Pack (1g) posted the standout move with a 48.07% month-over-month rise, climbing into rank 6, while Seatown Lemon Haze Pre-Roll 2-Pack (1g) held rank 1 with a 17.19% gain and Seatown Lemon Haze (3.5g) stayed at rank 2 on a 17.19% increase. Four of the top ten are Pre-Roll SKUs, including Dude Where's My Keys Pre-Roll 2-Pack (1g) up 13.03% at rank 3 and Lumpy Space Princess Pre-Roll 2-Pack (1g) up 6.91% at rank 5, whereas Lumpy Space Princess (3.5g) in Flower slipped 7.55% to rank 8. The concentration of gains at ranks 1, 3, 5, and 6 within Pre-Rolls, contrasted with a Flower decline, signals a mix tilting toward small-format inhalables over bulk Flower, with a likely push to sustain velocity via multi-pack pre-rolls despite a $27,747 anchor in flagship Flower.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

