

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeWhere to Buy
Passion Flower Cannabis is stocked at 150 licensed dispensaries across Washington, with the deepest coverage in Seattle, Spokane, Vancouver, Tacoma, and Olympia. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
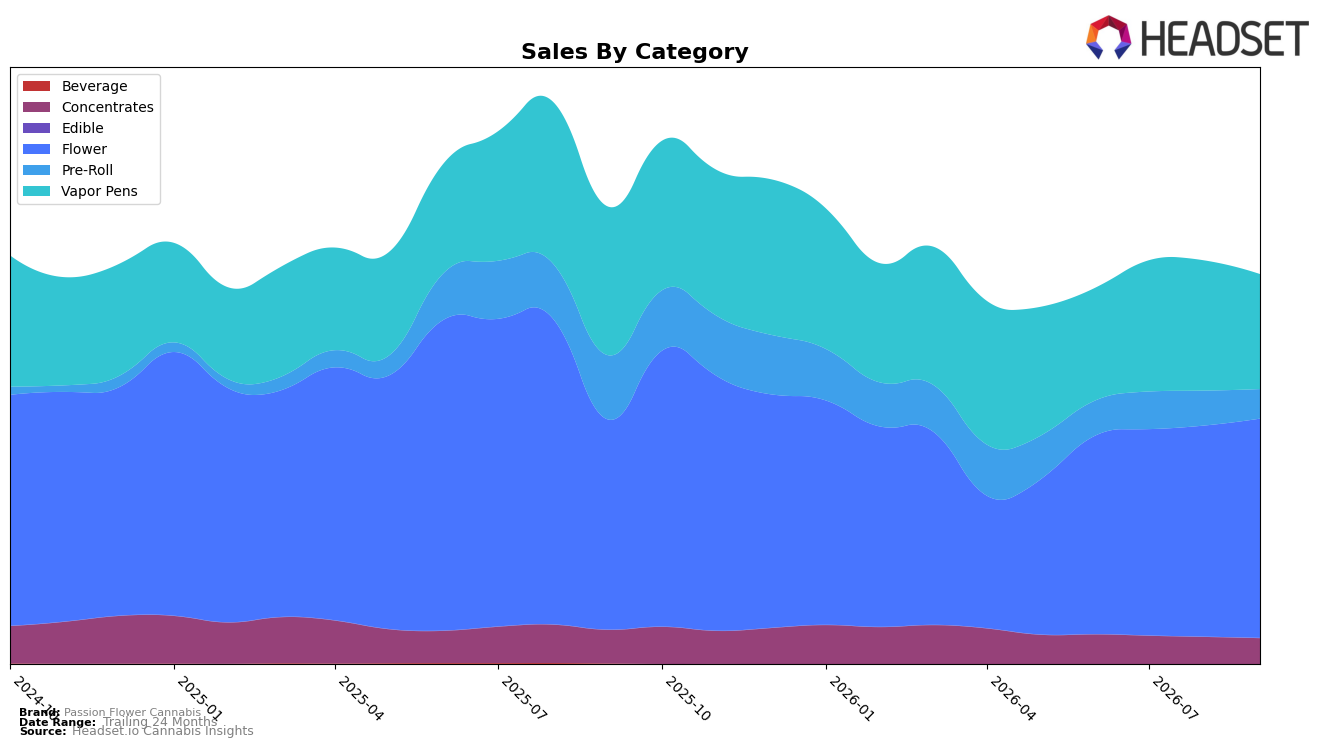
In September 2026, Passion Flower Cannabis concentrated over half of sales in Flower at 56.35% share with year-over-year growth of 4.40% and month-over-month growth of 3.84%, while Vapor Pens held 29.53% share but contracted by 22.66% YoY and 11.67% MoM. Pre-Roll, at 7.53% share, fell 54.27% YoY and 15.45% MoM, and Concentrates, at 6.60% share, declined 23.08% YoY and 4.53% MoM. With brand-level sales down 14.78% YoY despite a 2.15% YoY uptick in average price to $14.51, the mix shift toward Flower growth alongside broad declines in the other three categories implies reliance on a single expanding pillar to offset multi-category contraction.
The pivot toward Flower expansion alongside a 27th rank in Flower within Washington positions Passion Flower Cannabis as a mid-pack player leveraging a category that is growing for the brand (4.40% YoY, 3.84% MoM) while ceding ground in higher-price inhalable formats where declines are steeper (Vapor Pens -22.66% YoY, Concentrates -23.08% YoY). The simultaneous YoY price increase and Vapor Pens contraction suggests price or product architecture is dampening volume elasticity in premium-adjacent formats, pushing the brand toward value-forward Flower and away from Pre-Roll (-54.27% YoY) where scale losses are acute; this pattern implies near-term share stability depends on deepening Flower assortment while rethinking Pens and Pre-Roll positioning to prevent further mix erosion.
Competitive Landscape
Passion Flower Cannabis sits at rank 27 in WA Flower in September 2026, down 1 position year over year from rank 26, while its three-month position held flat at rank 27 and remains well off its peak at rank 14 from June 2025; in contrast, Hemp Kings surged from rank 24 to rank 5 alongside 105.1% YoY sales growth, and Mama J's edged up from rank 4 to rank 3 with 3.2% YoY sales growth. Meanwhile, category leaders are relatively stable as Phat Panda held rank 1 year over year with 19.0% YoY sales growth and Legends stayed at rank 2 despite a 16.9% YoY sales decline, indicating that Passion Flower Cannabis’s slight rank erosion amid both upward and downward competitor movements implies share is being redistributed toward faster risers, and its trajectory points to a need to regain momentum to re-approach the June 2025 peak.

Notable Products
Sour Green Strawberries (3.5g) posted the largest month-over-month gain at 69.9% and climbed into rank 3, while White Truffle (3.5g) fell 11.8% to rank 2 and the White Truffle Pre-Roll 2-Pack (1g) dropped 22.1% to rank 7. Flower concentrates the lineup with six of the top ten SKUs and holds ranks 1 through 5, whereas Pre-Roll activity sits lower at ranks 6–8 with mixed to negative momentum including an 8.7% decline for Lilac Sunset Pre-Roll 2-Pack (1g). The Strawberry Headband + CBG Live Resin Cartridge (1g) held rank 10 with a 6.4% dip, signaling limited pull from Vapor Pens compared to Flower strength at the top. The pattern implies a pivot toward curating momentum Flower strains and deprioritizing Pre-Roll and Vapor Pen breadth until those formats can recover rank and growth velocity.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

