
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeMarket Insights Snapshot
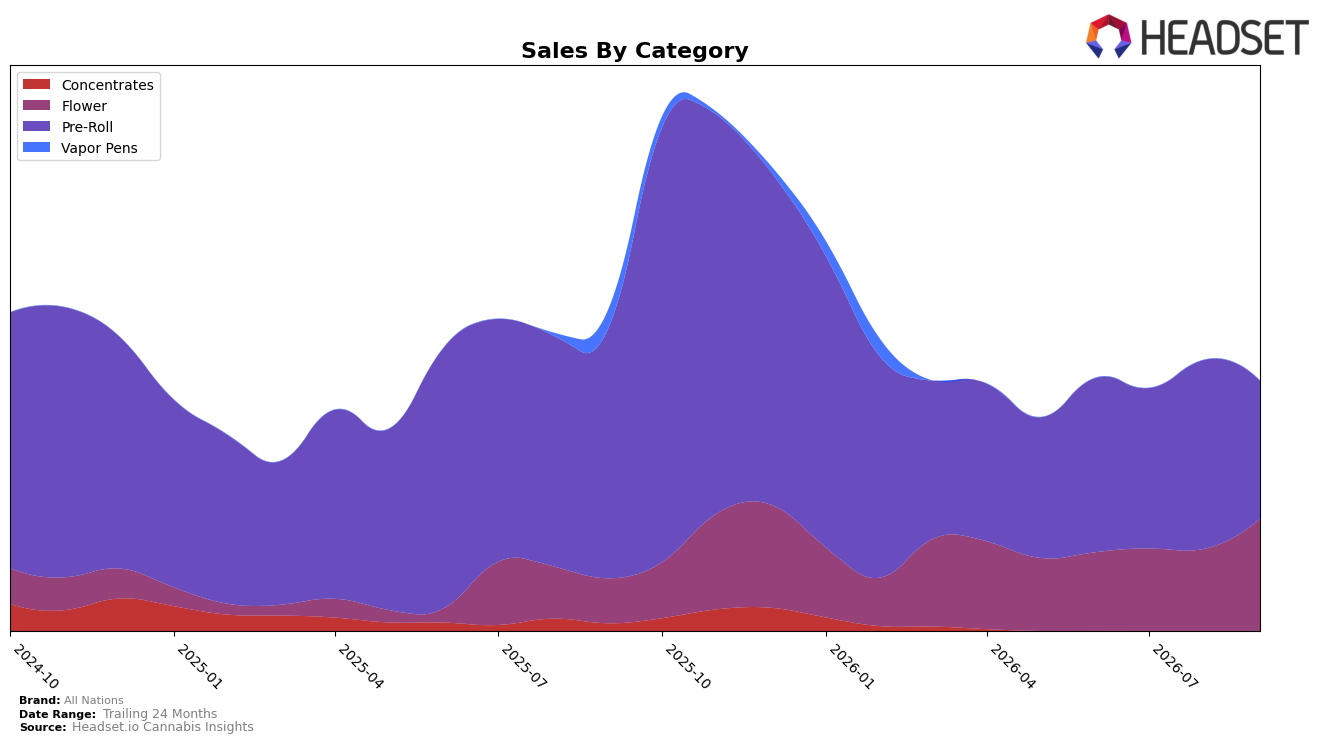
All Nations' category mix in September 2026 concentrated in Pre-Roll at 55.25% share despite a 44.72% year-over-year decline and a 26.88% month-over-month drop, while Flower rose to 44.75% share on a 150.83% year-over-year increase and a 36.53% month-over-month lift. Overall brand sales fell 22.10% year over year as the average price increased 10.66%, and in Pre-Roll the brand sat at rank 58 in British Columbia; this mix now leans on Flower growth to offset sharp Pre-Roll contraction, implying a pivot point where pricing and assortment need to realign with the faster-moving Flower segment.
The swing from Pre-Roll contraction (-44.72% YoY, -26.88% MoM) to Flower expansion (+150.83% YoY, +36.53% MoM) suggests consumer preference shifting toward higher-priced Flower (average $43.56 versus $16.25 in Pre-Roll), while the 10.66% average price increase coincides with a 22.10% brand sales decline, indicating price elasticity risk in categories with weakening velocity. With Pre-Roll still holding a 55.25% share yet ranking 58 in British Columbia, the brand’s positioning benefits from reallocating shelf emphasis toward Flower’s momentum and deploying targeted price-pack architecture in Pre-Roll to stabilize share without eroding the Flower-led margin mix.
Competitive Landscape
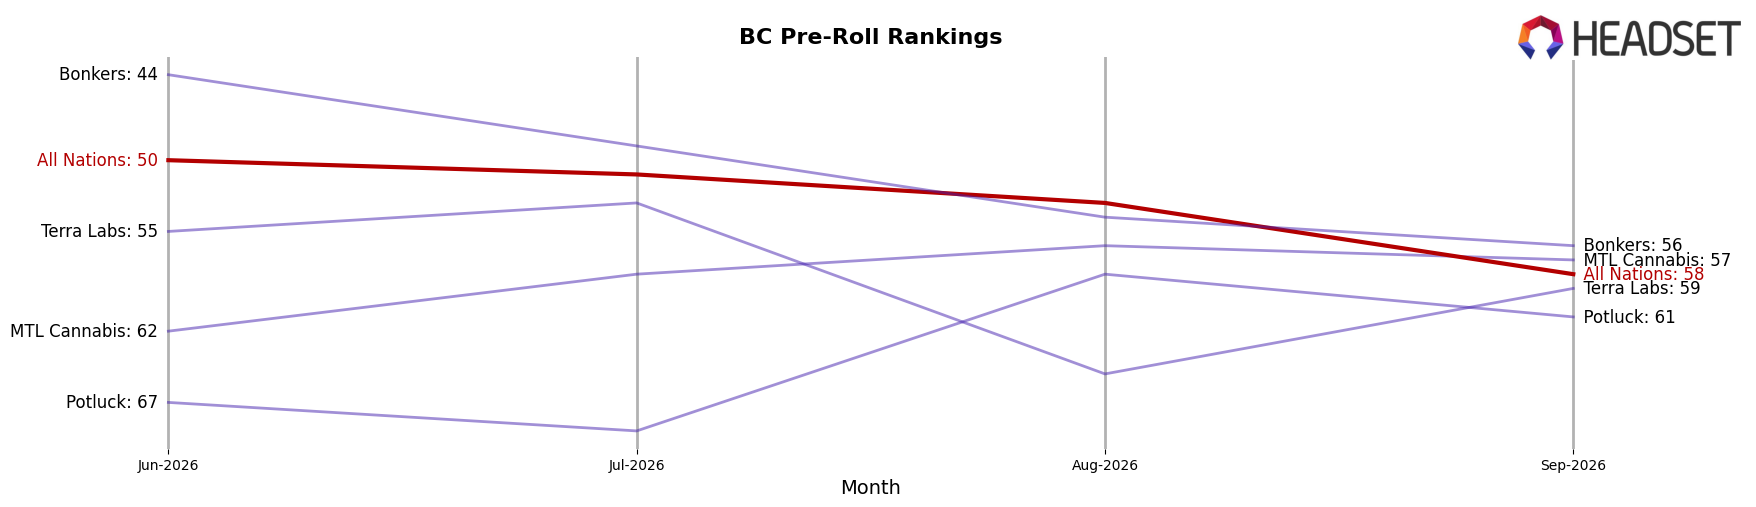
All Nations ranks #58 in BC Pre-Roll for September 2026, down 26 positions year over year from #32, and 8 places below its June 2026 position of #50; the brand’s trajectory contrasts with Weed Me holding #1 after rising from #2 year over year and with Back Forty / Back 40 Cannabis moving up to #2 from #13 alongside a 197.3% YoY sales lift, while General Admission sits at #3 despite a -8.5% YoY sales change; given a prior peak of #5 in October 2025, the drop from the top decile to #58 implies erosion in share-of-shelf and consumer rotation toward faster-rising leaders.
Notable Products
Blade Runner (3.5g) posted the standout move in September 2026 with a 79.9% month-over-month increase to rank 7, while Glitter Bomb Pre-Roll 3-Pack (1.5g) fell 61.7% to rank 10, indicating volatility between Flower and Pre-Roll formats. Four of the top ten are Pre-Roll SKUs, yet three of those—Lemon Tartz Pre-Roll 3-Pack (1.5g) at rank 1 down 24.8% and Sto:Lo Haze Pre-Roll 3-Pack (1.5g) at rank 2 down 22.6%, plus Tropic Thunder Pre-Roll 3-Pack (1.5g) at rank 4 down 37.9%—declined, while Flower SKUs like Cherry Gas (14g) rose 35.9% at rank 5, tilting mix toward larger-pack Flower. With only one Pre-Roll gainer among the leaders (El Chivo Pre-Roll 3-Pack up 9.1% at rank 3) against broad Pre-Roll pullbacks and rising mid-rank Flower, the pattern implies All Nations is migrating demand toward value-oriented Flower sizes rather than multi-pack Pre-Rolls.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

