

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Blem is stocked at 308 licensed dispensaries across California, with the deepest coverage in Los Angeles, San Diego, Sacramento, La Mesa, and Long Beach. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
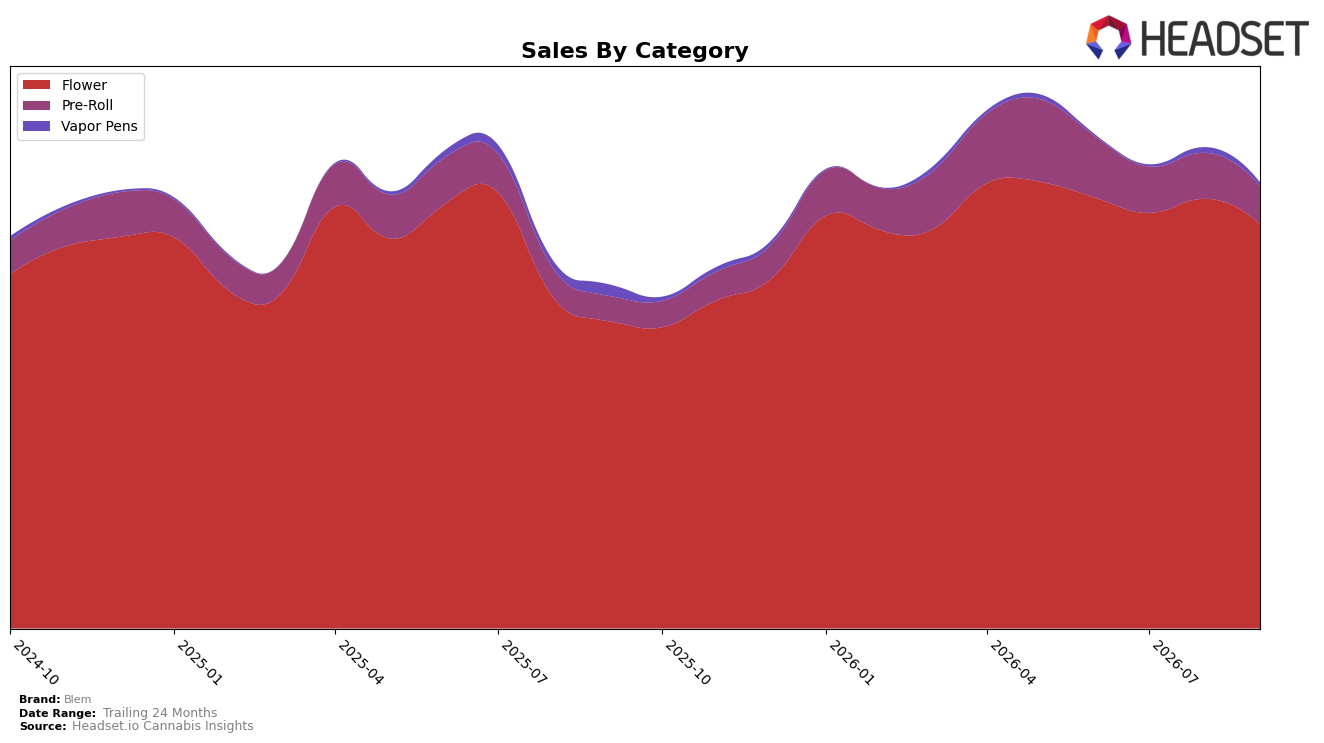
In September 2026, Blem concentrated 90.11% of sales in Flower, with Pre-Roll at 8.78% and Vapor Pens at 1.11%, indicating a narrowly focused mix. Flower grew 31.34% year over year but slipped 5.93% month over month, while Pre-Roll rose 48.68% year over year yet fell 16.30% month over month, and Vapor Pens contracted 60.96% year over year alongside a 27.71% month-over-month decline. The brand’s average price fell 9.32% year over year to $43.20 as the top state California anchored volume in Flower, and Blem held rank 7 in Flower within California. The pattern implies Blem is leaning harder into Flower to drive annual gains while near-term softness in both Flower and Pre-Roll compresses breadth, raising dependence on a single category to sustain momentum.
Blem’s positioning is tilting toward value-capture within Flower as price elasticity supports unit throughput, evidenced by a 31.34% year-over-year Flower lift against a 9.32% average price decline and a rank of 7 in California’s Flower category. However, simultaneous month-over-month pullbacks of 5.93% in Flower and 16.30% in Pre-Roll, combined with Vapor Pens’ 27.71% month-over-month drop and 60.96% year-over-year retrenchment, suggest the current price-volume equation may be nearing diminishing returns without complementary mix expansion. The implication is that maintaining rank 7 will require either stabilizing month-over-month Flower performance by tightening promotional cadence or reallocating attention to Pre-Roll’s higher year-over-year velocity despite recent monthly slippage, because a 90.11% Flower dependence limits resilience if monthly dips persist.
Competitive Landscape
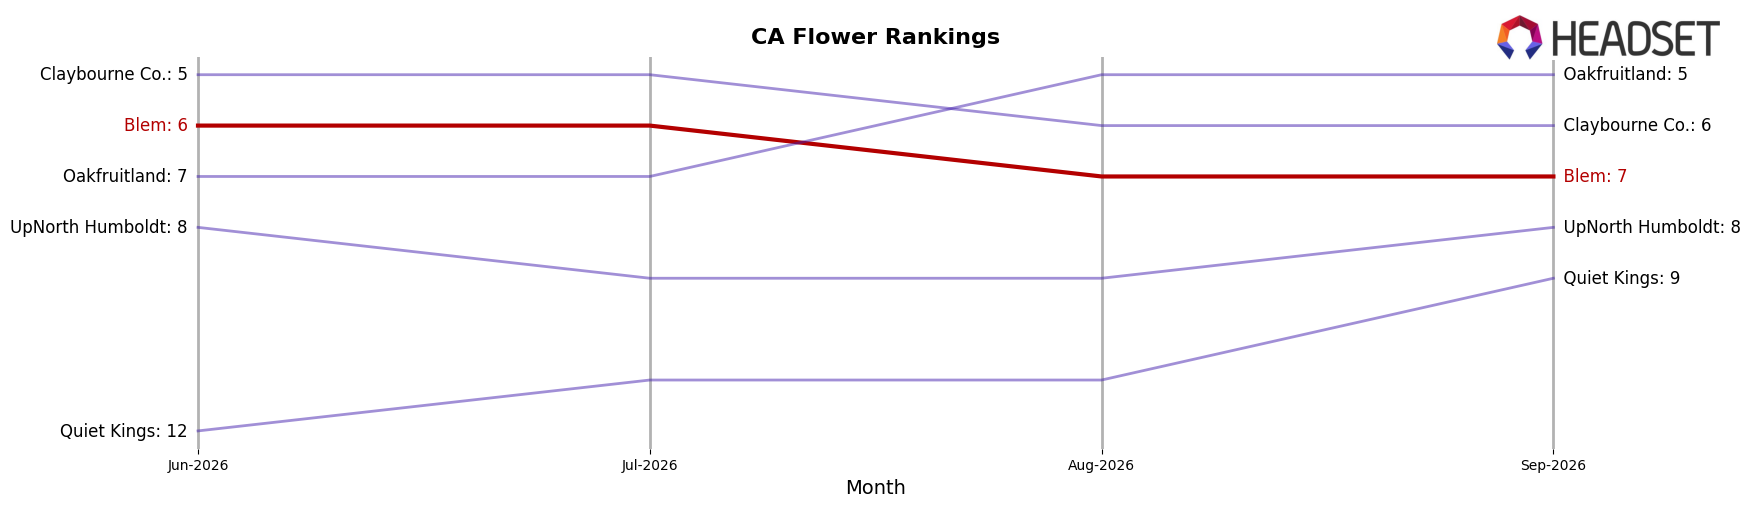
Blem sits at rank #7 in California Flower in September 2026, improving 3 positions year over year from #10 while slipping 1 spot versus June 2026 from #6, indicating a net upward YoY trajectory but a recent quarter-over-quarter softening; meanwhile, STIIIZY advanced from #2 to #1 with a 47.8% YoY sales increase and Oakfruitland jumped from #11 to #5 with 73.5% YoY growth, whereas CannaBiotix (CBX) fell from #1 to #3 alongside a 21.1% YoY sales decline; this mix of upward and downward competitor moves around Blem, combined with Blem’s prior peak at #4 in December 2024 and current placement outside the top 5, implies Blem is stabilizing into an upper-mid tier that can regain share if it converts recent rank gains into sustained monthly momentum against faster-rising rivals.
Notable Products
Rude Boy (3.5g) posted the steepest movement in September 2026 with a -52.9% month-over-month slide as it fell to rank 8, while Dream (3.5g) also contracted by -48.5% at rank 9, signaling a retreat among mid-table Flower SKUs. In contrast, Bomba (3.5g) surged 57.6% month over month to rank 4, but the top two ranks were held by Unruly OG (3.5g) at rank 1 with -9.0% and Unruly OG (10g) at rank 2 with -4.9%, indicating leadership concentrated in Unruly-branded formats despite mixed momentum. With eight of the top ten coming from Flower and only one Pre-Roll in the top six down -24.0% at rank 6, the mix points to deeper reliance on Flower while non-Flower formats lag, implying Blem’s commercial direction is anchored in flagship Flower lines that mask volatility in secondary SKUs.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

