

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Allswell is stocked at 170 licensed dispensaries across California, with the deepest coverage in Sacramento, San Diego, Los Angeles, San Francisco, and San Jose. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
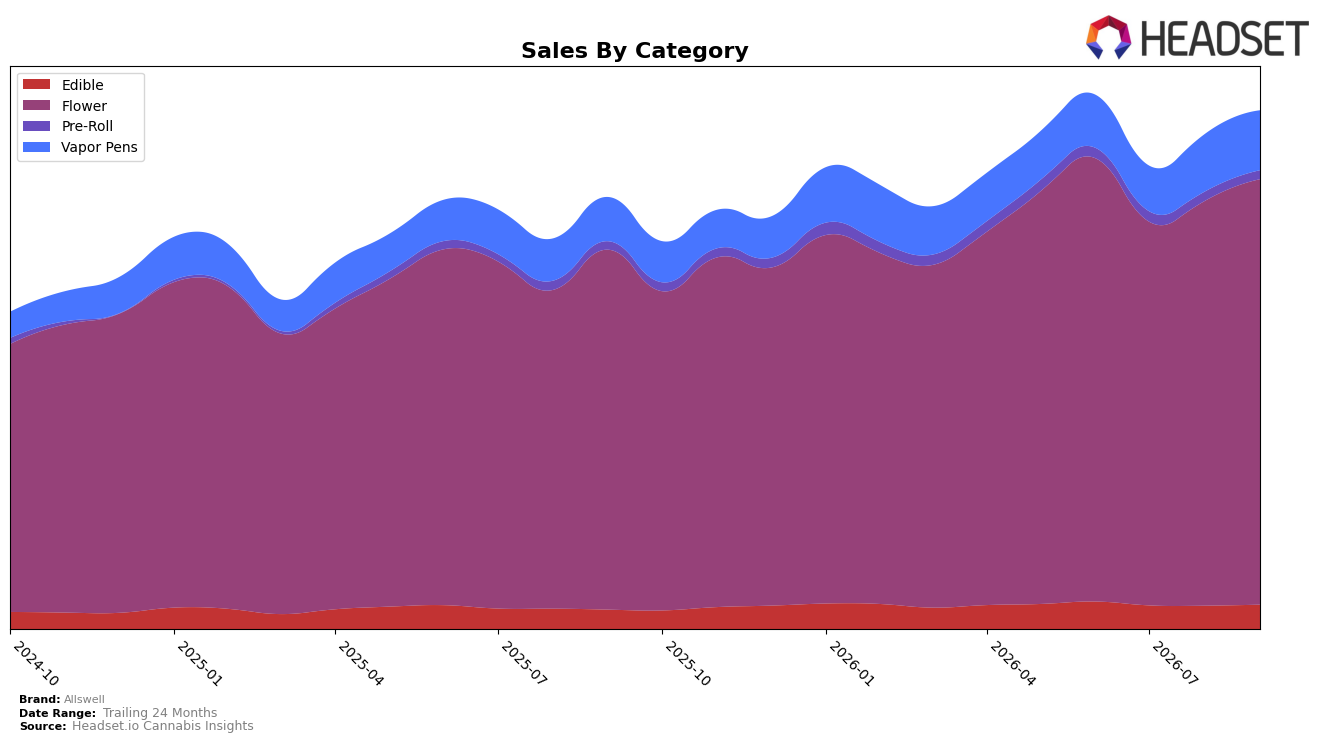
Allswell concentrated 81.44% of September 2026 sales in Flower, while Vapor Pens accounted for 11.67% and Edible for 4.95%; Flower grew 18.15% YoY and 5.12% MoM, Vapor Pens rose 34.54% YoY and 4.09% MoM, and Edible increased 23.70% YoY and 4.19% MoM. Pre-Roll held 1.94% share with 5.35% YoY growth but slipped 3.85% MoM, and the brand’s average price fell 11.87% YoY alongside overall sales growth of 19.84% YoY; combined with a Flower rank of 4 in California, the mix implies deliberate volume capture in core Flower while nurturing faster-growing, smaller formats. The pattern implies Allswell is trading price for scale in Flower to anchor share, using that base to incrementally expand in Vapor Pens and Edible where growth rates outpace the core but remain secondary in contribution.
With Flower still above four-fifths of revenue and ranked 4 in California, the 18.15% YoY and 5.12% MoM gains point to sustained shelf velocity even as average price dropped 11.87% YoY, indicating a volume-led posture; meanwhile, Vapor Pens’ 34.54% YoY and Edible’s 23.70% YoY growth, despite smaller shares of 11.67% and 4.95%, indicate a hedge toward inhalable convenience and value snacking. The implication is that Allswell’s positioning is anchored in accessible Flower that underwrites distribution and rank, while faster growth in Vapor Pens and Edible provides optionality to rebalance mix if Pre-Roll’s 3.85% MoM decline persists and if price elasticity continues to favor lower price points.
Competitive Landscape
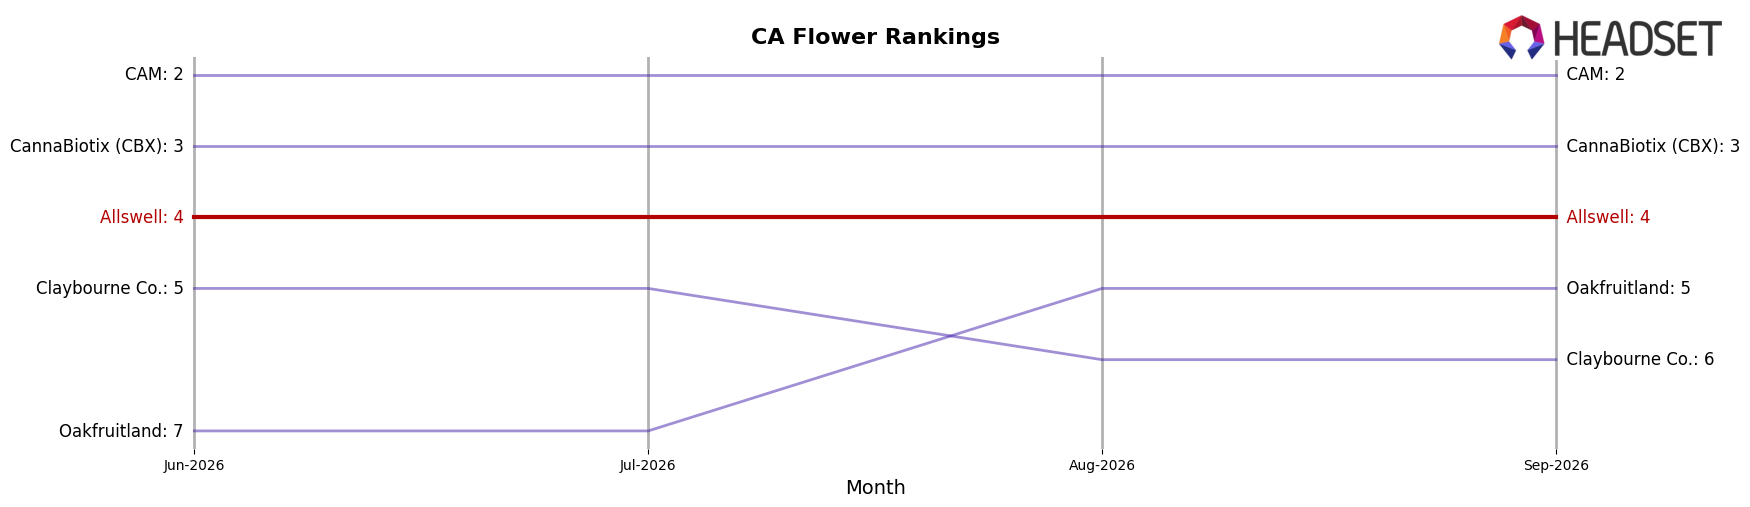
Allswell sits at rank #4 in CA Flower for September 2026, unchanged from #4 in September 2025, while its three-month position also held at #4; in contrast, STIIIZY moved from #2 to #1 with a 47.8% year-over-year sales increase and CannaBiotix (CBX) slid from #1 to #3 with a 21.1% sales decline. Additional pressure comes from CAM climbing from #3 to #2 alongside a 28.9% sales lift, while Oakfruitland surged from #11 to #5 with 73.5% growth, placing Allswell’s static #4 rank against both upward and downward competitor movements; the flat rank across year-over-year and three-month windows implies Allswell is holding share amid a reshuffle above and below it, signaling a need to convert stability into upward mobility before faster risers crowd the #4 slot.
Notable Products
Tangie Storm Pre-Roll (1g) posted the standout movement with a 26.5% month-over-month gain to rank 10 in September 2026, while Citrus Twist Gummies 10-Pack (100mg) slipped 5.4% at rank 9, and Sour Tropical Blast Gummies 10-Pack (100mg) advanced 12.0% at rank 7. Sweet Berry Dream Gummies 10-Pack (100mg) held rank 1 with an 8.5% lift as Sour Blue Raspberry Gummies 10-Pack (100mg) stayed at rank 2 with a 5.2% increase, but the absence of any double-digit MoM surge at the very top suggests incumbents are adding incremental volume rather than step-change growth. Four of the top ten are Pre-Roll SKUs concentrated between ranks 4 and 10, indicating category breadth is widening even as five Edible SKUs occupy ranks 1 through 9. The mix implies Allswell is pivoting from Edible-led volume to a more diversified basket where Pre-Rolls are beginning to contribute growth bursts that can offset softer Edible compares.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

