
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
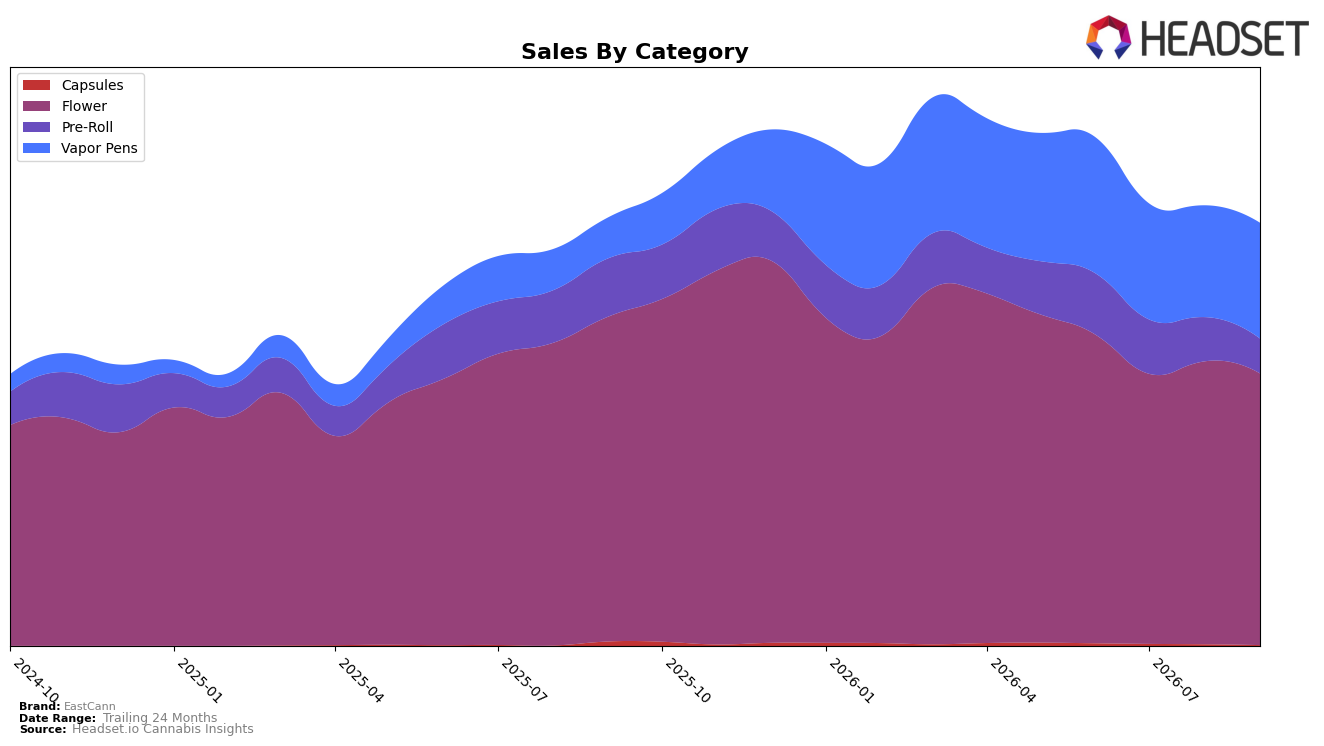
EastCann concentrated 64.29% of September 2026 sales in Flower, where year-over-year declined 16.39% and month-over-month dipped 3.98%, while Vapor Pens rose to 27.35% share with 184.08% year-over-year growth and a 3.56% month-over-month increase. Pre-Roll contracted to 8.19% share with a 40.40% year-over-year drop and a 21.24% month-over-month decline, and Capsules fell to 0.17% share with an 83.17% year-over-year and 53.41% month-over-month decrease; together, these shifts offset a 5.45% average price increase and align with EastCann’s overall 1.27% year-over-year brand sales dip. In Ontario Flower, the brand sits at rank 23, implying that category-led headwinds in Flower and Pre-Roll are being partially rebalanced by Vapor Pens’ outsized growth and mix gain.
The pivot toward Vapor Pens’ 27.35% share alongside a 184.08% year-over-year surge, against Flower’s 16.39% decline and Pre-Roll’s 40.40% decline, implies EastCann is migrating demand to higher-velocity non-Flower formats to stabilize revenue. Maintaining rank 23 in Ontario Flower while Flower mix remains high at 64.29% suggests a need to lean further into Vapor Pens’ momentum and selectively prune underperforming Pre-Roll and Capsules, because the current mix delivered only a 3.56% month-over-month lift in Pens against a 3.98% month-over-month drag in Flower—pointing to incremental share gains coming more efficiently from Pens than from defending Flower.
Competitive Landscape
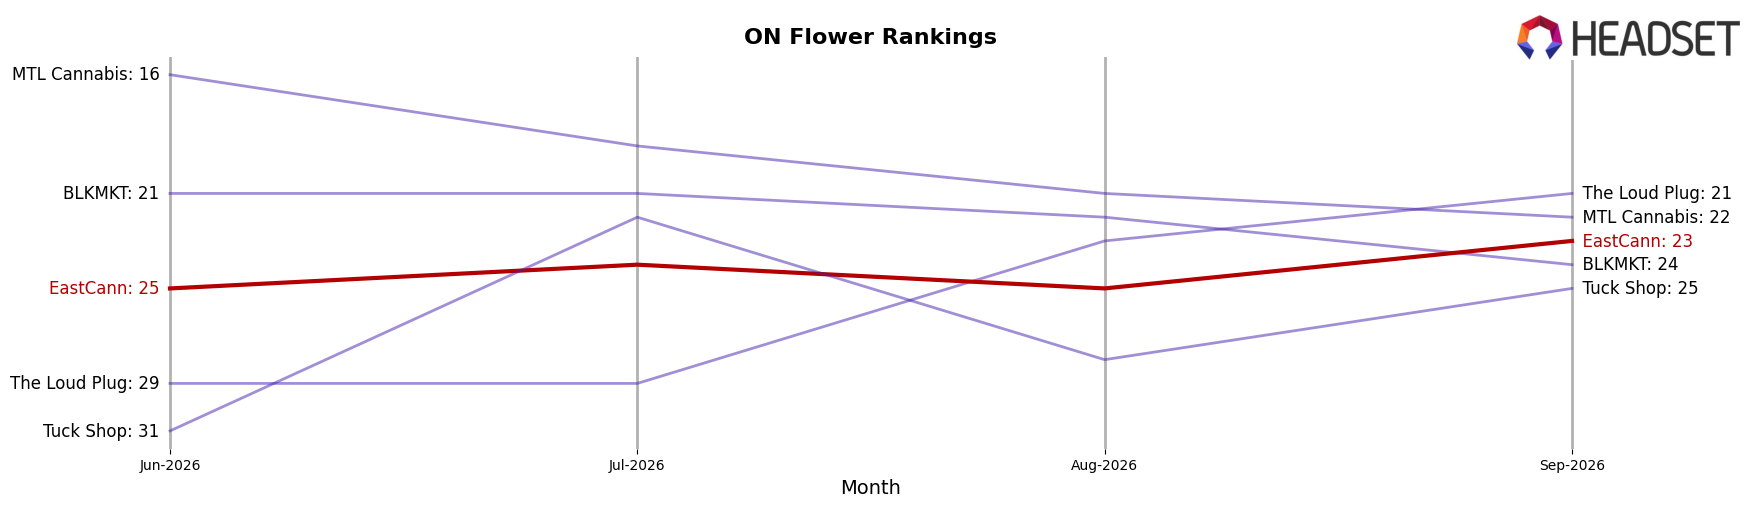
EastCann sits at rank 23 in September 2026, improving 2 positions year over year from rank 25 and holding a 2-position climb from June 2026’s rank 25, while its peak rank was 21 in April 2026 and is now 2 places lower; in contrast, Spinach advanced from rank 3 to rank 1 alongside a 15.7% year-over-year sales increase, and Back Forty / Back 40 Cannabis slid from rank 1 to rank 3 with a 7.4% sales decline. With FIGR jumping from rank 14 to rank 5 on 51.7% year-over-year growth while EastCann remains 2 spots off its April 2026 peak, the pattern implies EastCann’s modest rank gains are being outpaced by faster risers, signaling a need to convert stability into upward share capture.
Notable Products
Rainbow Pave Pre-Roll 10-Pack (5g) fell 45.8% month over month to rank 10 in September 2026, while Chopper's Pick Pre-Roll 10-Pack (5g) declined 27.8% at rank 9, signaling a pullback in multi-pack pre-roll momentum despite Flower strength. In contrast, Velvet Z (7g) climbed 43.3% MoM to secure rank 1 and Chopper's Pick (28g) gained 9.6% at rank 4, concentrating demand in larger Flower formats that now anchor the top spots; four of the top ten are Flower SKUs. Vapor Pens were mixed, with Mango Sour Pure Live Resin Cartridge (1g) up 18.6% at rank 2 versus Frozen Lemons Live Resin Cartridge (1g) down 16.6% at rank 8, implying consumers are trading into select terpene-led carts while exiting value pre-roll bundles. The pattern implies EastCann’s commercial direction is tilting toward premium large-format Flower and a curated set of Vapor Pen flavors, with pre-rolls de-prioritized in the near term.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

