
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
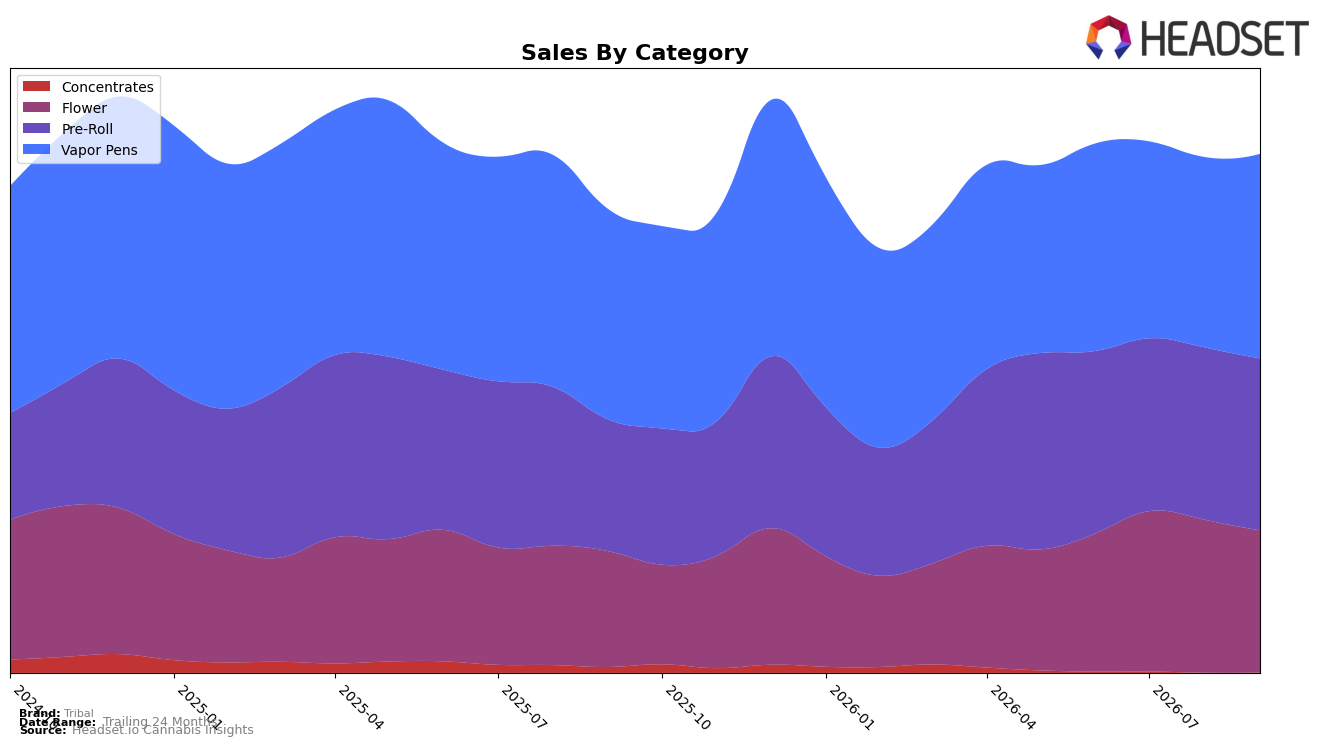
In September 2026, Tribal’s mix leaned on Vapor Pens at 38.62% share with a month-over-month gain of 7.13% but a year-over-year dip of 2.68%, while Pre-Roll held 32.67% share with a 28.76% year-over-year increase and a slight 0.18% month-over-month decline. Flower reached 27.28% share with 21.53% year-over-year growth yet fell 6.69% month-over-month, and Concentrates sat at 1.43% share with a 41.43% year-over-year drop alongside a 1.58% month-over-month uptick. Average price fell 19.16% year-over-year to $27.21 while total brand sales grew 11.18% year-over-year, implying a volume-led expansion skewed toward Pre-Roll and Flower even as Vapor Pens stabilized sequentially.
The combination of a 7-place rank in Vapor Pens within Ontario and a 7.13% month-over-month lift in that category, alongside a 6.69% month-over-month decline in Flower, points to a near-term mix shift toward inhalable convenience formats and away from bulk purchase occasions. With Pre-Roll up 28.76% year-over-year but nearly flat month-over-month at down 0.18%, and Concentrates contracting 41.43% year-over-year despite a 1.58% month-over-month nudge, the brand’s price compression of 19.16% year-over-year appears to be reallocating demand from higher-complexity formats toward accessible form factors, implying Tribal’s positioning is consolidating around Vapor Pens and Pre-Roll as the primary demand engines while Flower becomes more promotional and Concentrates recede to a niche.
Competitive Landscape
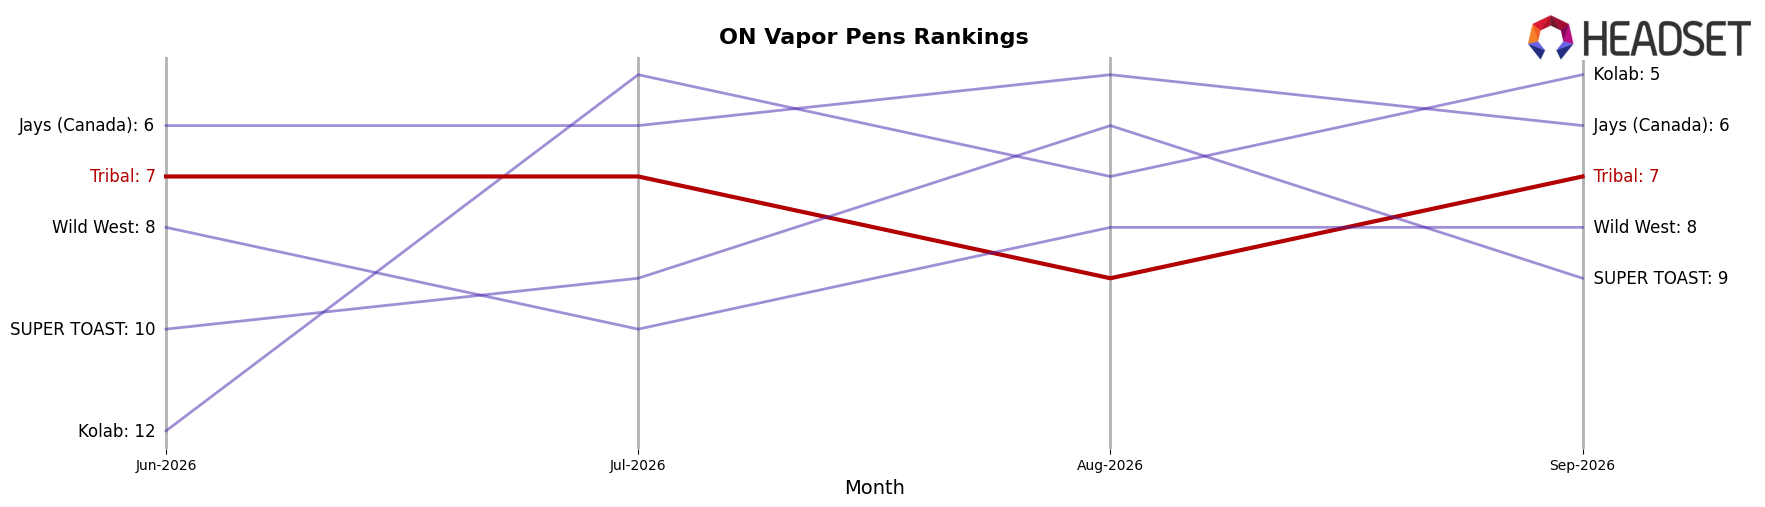
Tribal sits at rank #7 in ON Vapor Pens in September 2026, down 1 position year over year from #6 while flat versus June 2026 at #7, indicating a stall below its February 2026 peak at #5 and a two-spot gap from that high. In contrast, Spinach climbed from #4 to #1 with 172.5% YoY sales growth, and Kolab jumped from #14 to #5 with 93.0% YoY growth, while Back Forty / Back 40 Cannabis slipped from #1 to #2 despite a 3.0% YoY increase. The pattern—Tribal drifting from #6 to #7 while peers move sharply up or, in one case, down a single spot—implies Tribal is losing relative momentum in a consolidating top tier and will require share capture to re-close the two-rank gap back to its February 2026 peak.
Notable Products
Gran Turismo Pre-Roll (1g) posted the standout move in September 2026 with an 86.7% month-over-month surge and a climb to rank 4, while Gran Turismo (3.5g) fell 12.2% MoM at rank 10, indicating a format shift within the same strain line. Cuban Linx Live Resin Cartridge (1g) rose 15.2% MoM at rank 3 as Cuban Linx Pre-Roll (1g) gained 8.9% at rank 1, and five of the top ten are Pre-Roll SKUs, concentrating demand in ready-to-consume formats. With Cuban Linx Pre-Roll 5-Pack (2.5g) dipping 2.5% MoM at rank 2 and Gran Turismo Pre-Roll 5-Pack (2.5g) up 13.0% at rank 7, multipack momentum appears brand- and strain-specific rather than category-wide. The mix points to Tribal leaning into Pre-Rolls and vapor formats over traditional flower, reallocating attention toward convenience-led SKUs where rank positions are highest and MoM velocity is more reliable.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

