


Where to Buy
Bloom County is stocked at 68 licensed dispensaries across Colorado, with the deepest coverage in Denver, Boulder, Aurora, Colorado Springs, and Grand Junction. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
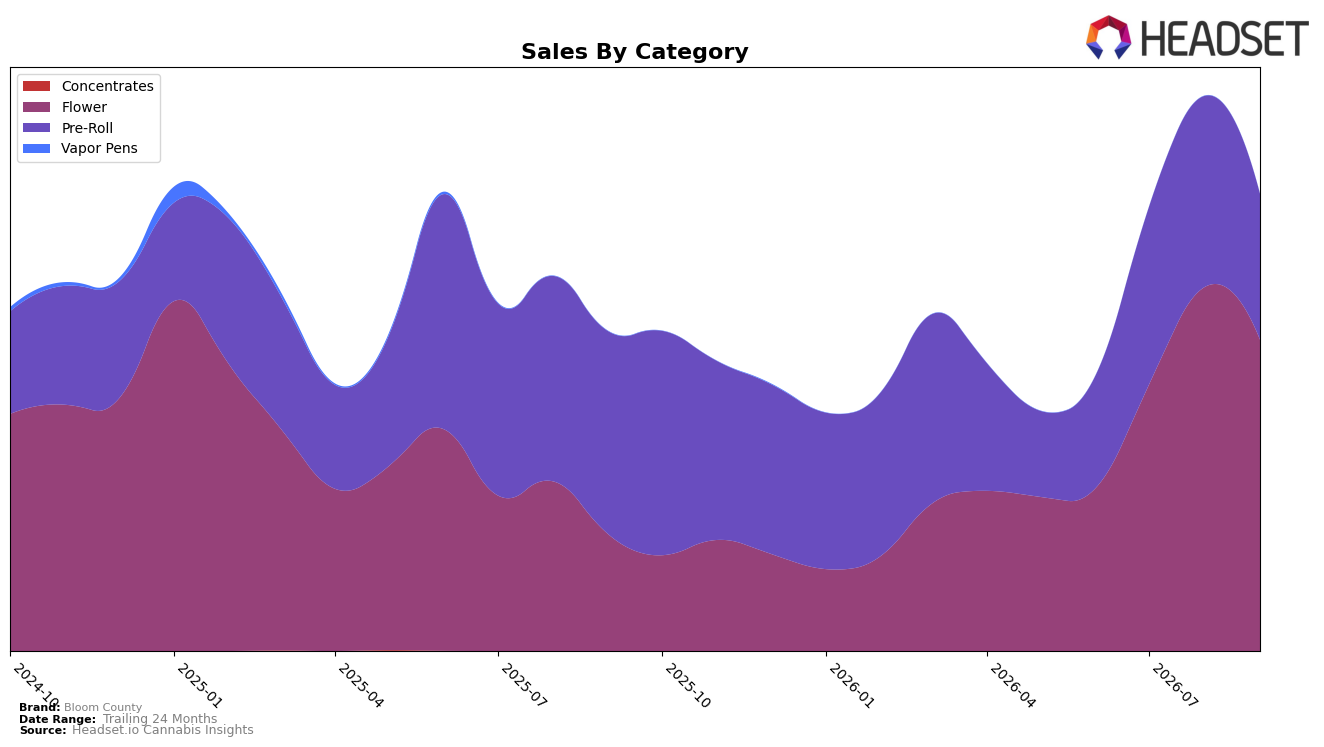
In September 2026, Bloom County’s mix concentrated in Flower at 68.11% share with 167.03% year-over-year growth but a -14.47% month-over-month decline, while Pre-Roll held 31.89% share with -28.14% year-over-year and -23.72% month-over-month changes; against this mix, the brand’s average price rose 74.29% year-over-year to $9.94 and Flower’s average price sat at $16.48. Within Flower, the brand ranked 17 in Colorado, implying the category is both the growth engine and the volatility source, with the September 2026 pullback and dual-category MoM declines signaling a tactical need to stabilize pricing and inventory in the core while the shrinking Pre-Roll contribution reduces diversification.
The shift toward Flower (up 167.03% YoY but down -14.47% MoM) alongside Pre-Roll contraction (-28.14% YoY and -23.72% MoM) tightens Bloom County’s positioning around a single category where it holds rank 17 in Colorado and 68.11% internal share, meaning category-led swings will disproportionately influence total outcomes. The combination of a 74.29% YoY average price increase and a -23.72% MoM drop in Pre-Roll suggests pricing power and mix-driven margin potential in Flower, but also elevated sensitivity to monthly demand shifts; this implies Bloom County’s most durable path is deepening Flower differentiation while selectively rebuilding Pre-Roll to smooth volatility rather than relying on MoM spikes in a single category.
Competitive Landscape
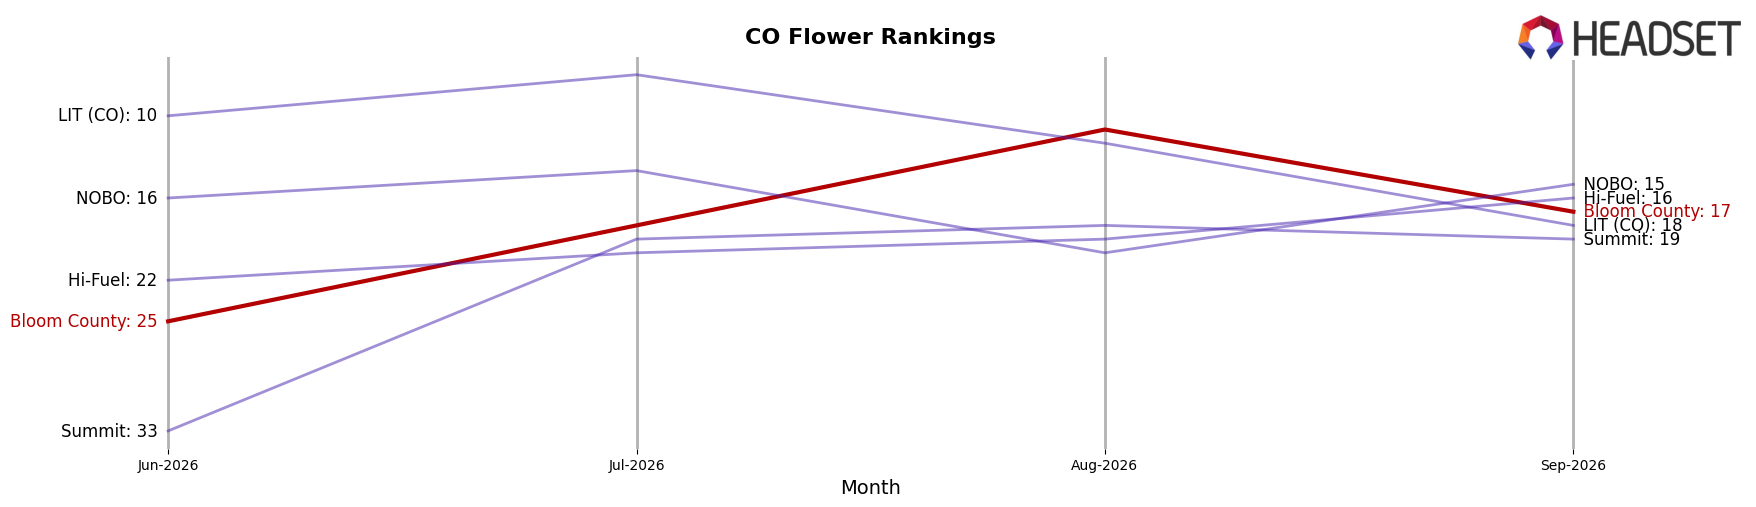
Bloom County sits at rank #17 in Colorado Flower in September 2026, improving 21 positions from #38 year over year, while slipping 8 spots from #9 since its January 2025 peak; over the latest quarter it declined from #25 to #17, a 32% rank improvement within three months that still trails its earlier high-water mark. In directional contrast, Green Label Cannabis held #1 year over year and in September 2026 with a 38.0% YoY sales increase, and Good Chemistry Nurseries advanced from #3 to #2 with 45.5% YoY sales growth, whereas Seed & Strain Cannabis Co. slid from #2 to #4 alongside a -33.5% YoY drop; this mix of upward and downward competitor moves implies Bloom County’s rebound from #38 to #17 is momentum-driven but not yet durable enough to dislodge entrenched leaders without further share gains.
Notable Products
New York City Diesel Pre-roll (1g) posted the steepest decline at -37.6% MoM while sliding at rank 10, and First Class Gas Pre-Roll (1g) also contracted -15.5% MoM from rank 6, signaling pressure within value or legacy pre-rolls rather than across the board. Golden Goat (3.5g) grew 7.8% MoM at rank 3 and Super Lemon Haze (3.5g) dipped -4.1% MoM at rank 9, while four of the top ten are Pre-Roll SKUs concentrated between ranks 1–6, implying shelf space is still anchored by pre-rolls even as volatility increases at the lower end. Blue Dream Pre-Roll (1g) held rank 1 with no reported MoM rate and Gary Payton Pre-Roll (1g) sat at rank 5 with no reported MoM rate, while Golden Goat (3.5g) contributed $95,570, indicating Flower resilience can offset pre-roll softness. The pattern implies Bloom County is leaning into a barbell mix where premium Flower steadiness and flagship pre-roll positions counterbalance sharper drops among secondary pre-rolls, guiding assortment toward fewer, higher-velocity SKUs.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

