

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
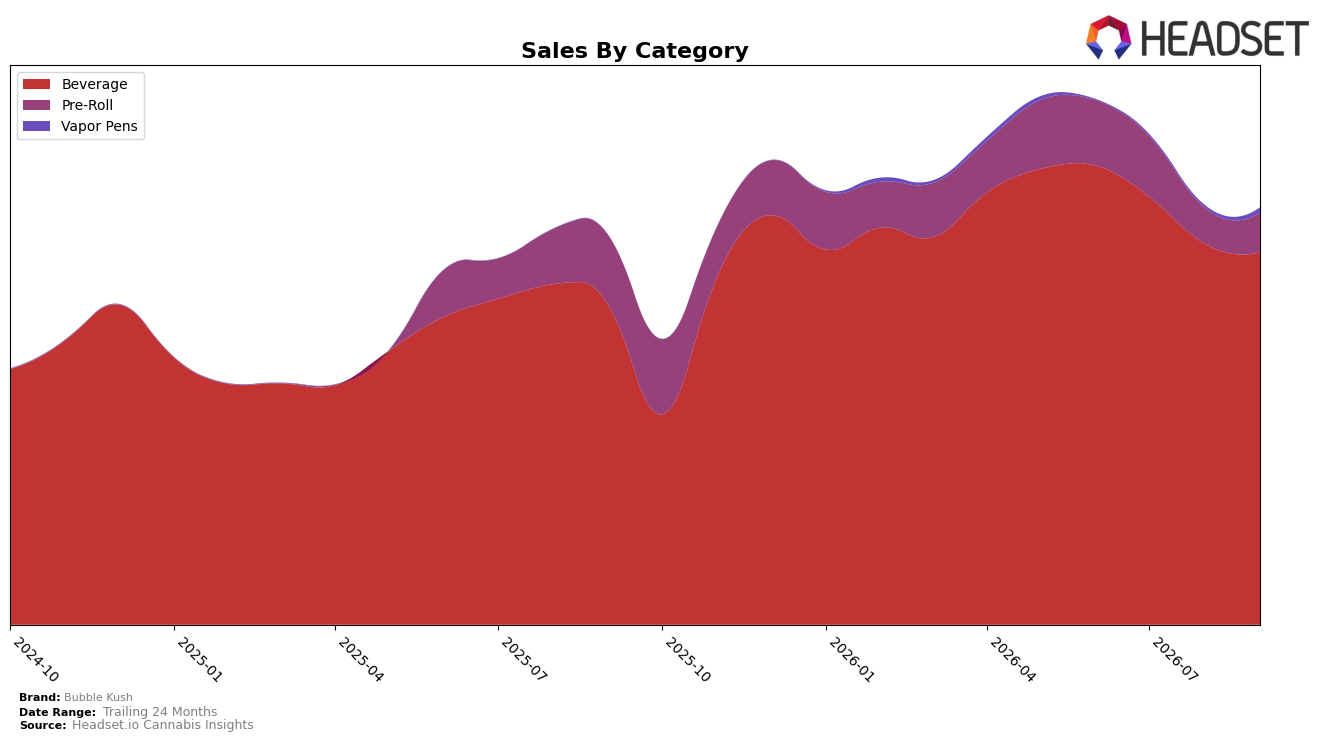
In September 2026, Bubble Kush concentrated 89.41% of sales in Beverage, up 16.62% year over year but down 2.28% month over month, while Pre-Roll held 9.46% share with a 43.47% YoY decline and a 10.10% MoM rebound. Vapor Pens remained small at 1.13% share but posted a 120.29% MoM surge from a low base, with no YoY comparison available, and the brand’s average price fell 5.36% YoY alongside a 7.06% YoY lift in total sales. Given Bubble Kush’s rank of 1 in Beverage in British Columbia, the mix skews toward defending category leadership rather than diversifying volume.
The shift—Beverage softening 2.28% MoM as Pre-Roll grows 10.10% MoM and Vapor Pens jumps 120.29% MoM—implies Bubble Kush is using lower price (down 5.36% YoY) to protect its Beverage base while cautiously testing adjacent formats. With 89.41% of volume tied to Beverage and rank 1 in British Columbia, the pattern points to a positioning anchored in high-share Beverage leadership, with Pre-Roll’s 43.47% YoY contraction and Vapor Pens’ 1.13% share indicating limited but accelerating extensions that reduce single-category risk without materially shifting the portfolio yet.
Competitive Landscape
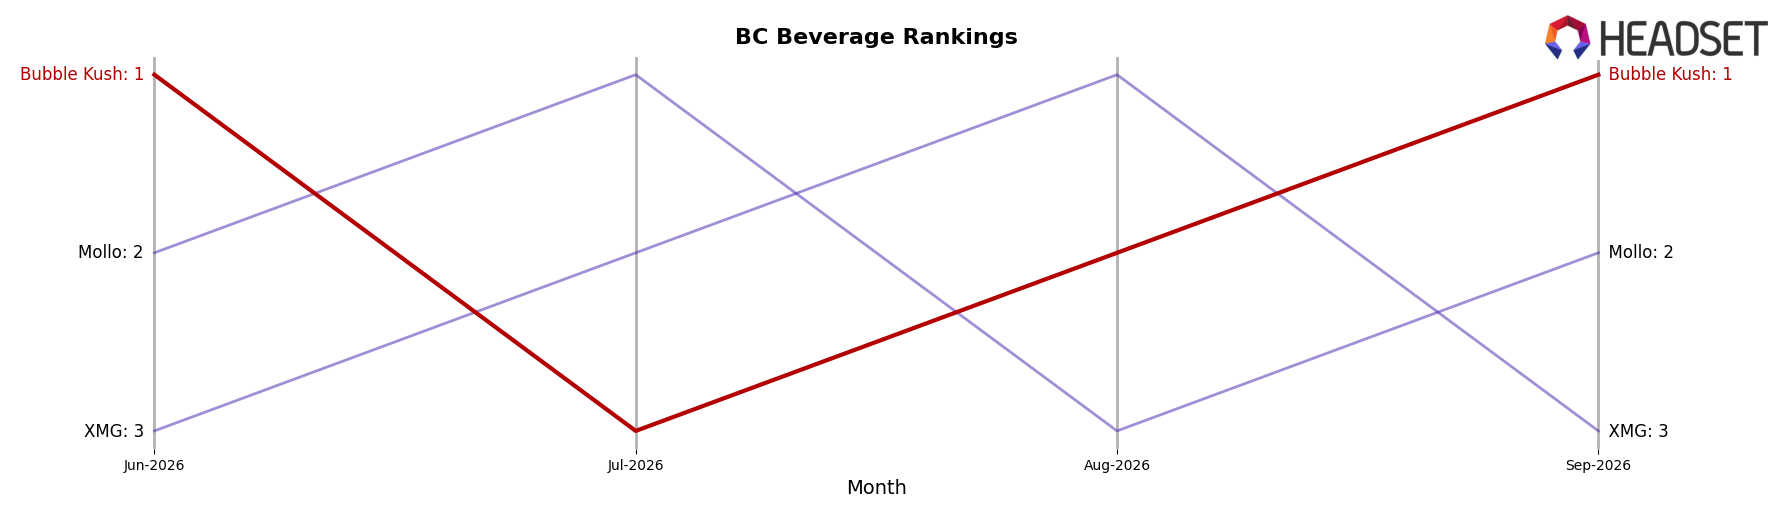
Bubble Kush holds rank #1 in BC Beverage in September 2026 with no year-over-year rank change from #1, while Mollo sits at #2 after improving from #3 and expanding sales by 32.6%, and TeaPot climbed from #10 to #5 on 136.5% year-over-year growth, indicating pressure from fast risers below; meanwhile, XMG slipped from #2 to #3 despite 12.7% sales growth and Sweet Justice stayed flat at #4 with 7.8% growth, a spread that suggests Bubble Kush’s static #1 against double- and triple-digit growth beneath implies a need to defend share before upward momentum from challengers converts into rank displacement.
Notable Products
Zapz - Kiwi Sorbet Distillate Disposable (1g) posted the month’s sharpest move with +120.3% MoM, climbing into rank 9, while Wandz Fruitz - Dragonfruit Hibiscus Infused Pre-Roll 5-Pack (2.5g) fell -31.3% MoM at rank 10. Root Beer Beverage (10mg THC, 355ml) held rank 1 with a -2.3% MoM dip while Orange Soda (10mg THC, 355ml) rose +9.1% MoM at rank 2, and Rocket Fizz Soda (10mg THC, 355ml) slid -17.7% MoM at rank 5 against Lemon Lime Soda (10mg THC, 355ml) down -7.4% at rank 4. Four of the top ten are Pre-Roll SKUs, but only one cracked double-digit rank movement over +15%, suggesting Vapor Pens are now the incremental growth lever even as Beverages still concentrate the bulk of volume near the top; September 2026 therefore points to diversification beyond the flagship soda lineup. The mix implies Bubble Kush is shifting from Beverage-led rank stability toward testing higher-velocity niches in Vapor Pens, using selective Pre-Roll rationalization to fund growth.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

