


Where to Buy
ButACake is stocked at 39 licensed dispensaries across New Jersey, with the deepest coverage in Bloomfield, Jersey City, Newark, Atlantic City, and Belleville. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
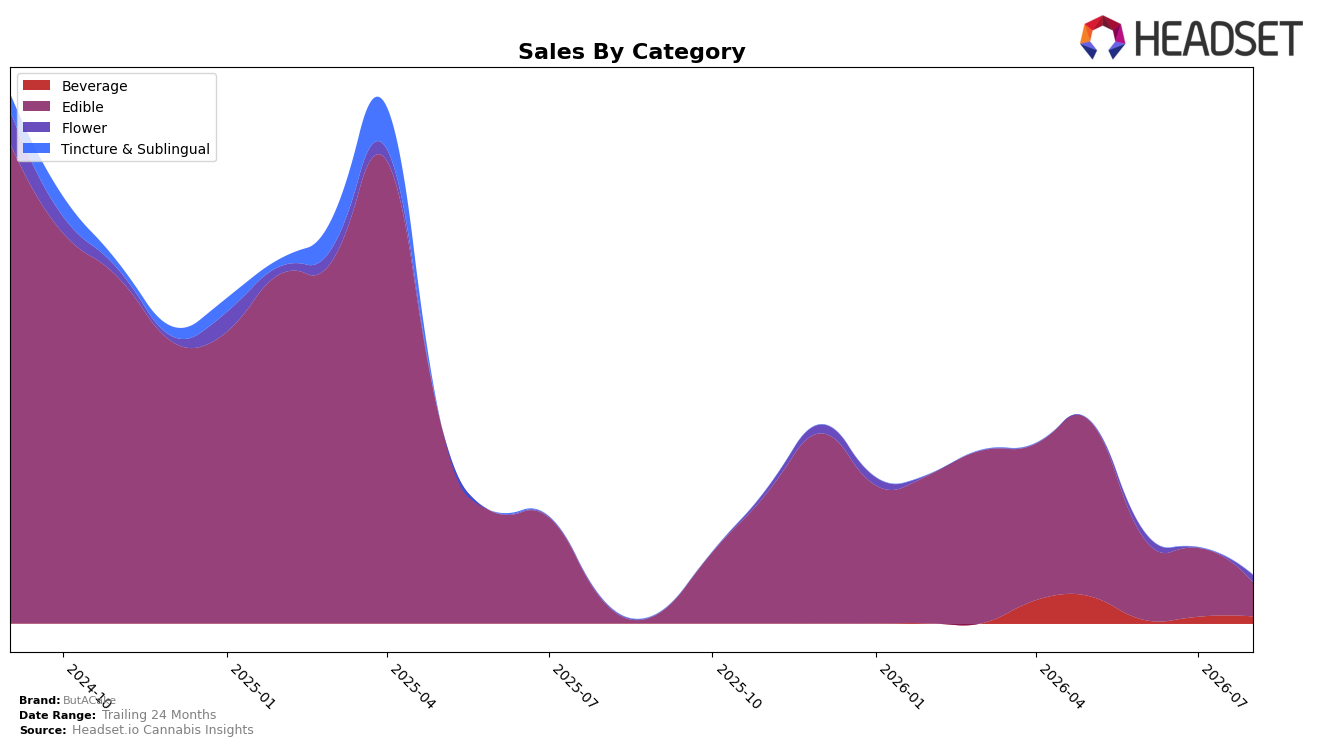
ButACake concentrated 70.70% of August 2026 sales in Edible, where category sales were up 60.57% year over year but down 50.86% month over month, while average price sat at $9.47 with overall brand pricing up 20.71% YoY. Beverage contributed 14.76% share with a 4.50% MoM lift and no reported YoY, contrasted by Flower at 14.54% share surging 4,088.54% MoM and 853.70% YoY on a lower $7.66 average price. The mix shift toward rapid Flower growth alongside a halving MoM in Edible implies a pivot from a single-category anchor toward a dual-pillar portfolio that trades some short-term Edible momentum for outsized acquisition in Flower.
With brand sales up 119.50% YoY but down 92.51% versus 24 months, the August 2026 mix suggests ButACake is rebuilding scale through high-velocity Flower while preserving margin via a 20.71% YoY price increase. Edible remains the anchor at rank unknown in New Jersey Edible, yet the 50.86% MoM decline alongside a 4.50% MoM Beverage rise indicates near-term demand is shifting toward quicker-turn formats and value-price Flower at $7.66; the implication is that ButACake’s positioning is migrating from a primarily Edible-first identity toward a balanced value-accessible Flower plus premium-priced Edible stance that can widen household penetration while cushioning mix-driven margin risk.
Competitive Landscape
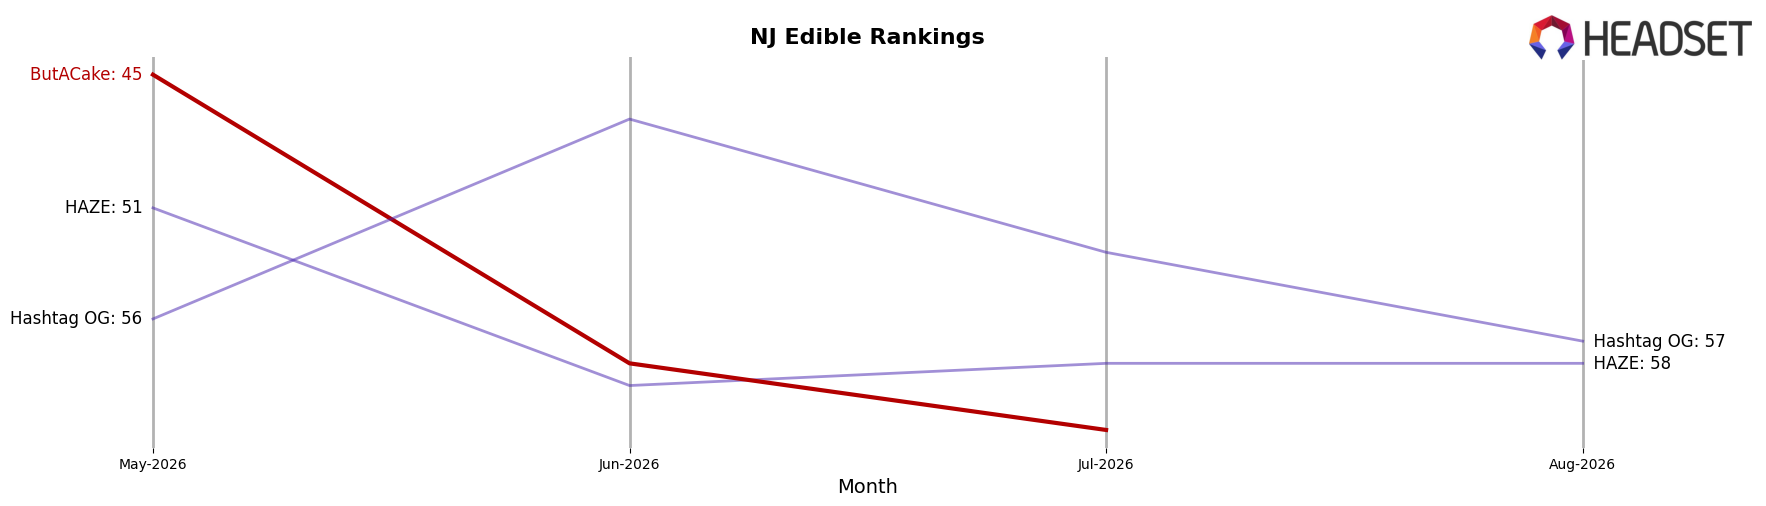
ButACake ranks #66 in New Jersey Edible for August 2026, down 2 positions year over year from #64 and 21 positions since May 2026 when it stood at #45; the brand also sits 44 spots below its peak #22 from August 2024, indicating a two-year slide that contrasts with category leaders. While Gron / Grön holds #1 with a -19.9% year-over-year sales change and OGEEZ advanced from #7 to #4 alongside an 18.0% sales increase, ButACake moved the opposite direction from #45 to #66 within three months and from #64 to #66 year over year; this divergence implies ButACake is losing relative shelf position as faster-moving rivals consolidate the top ranks despite mixed growth in the category.
Notable Products
Classic Brownie (10mg) delivered the standout movement in August 2026 with +165.95% MoM to rank 1, while Choco Chunk Cookie (10mg) fell -72.91% to rank 5, indicating a sharp shift toward brownies at the very top of the ladder. PBNJ Brownie (10mg) held rank 2 with +14.94% MoM, and four of the top ten are Edible SKUs concentrated in brownies and cookies, while Beverage sits at rank 4 with +4.48% MoM and Flower at rank 3 with no prior-month baseline. Snickerdoodle Cookie (10mg) slid -89.80% to rank 6 and Sugar Cookie (10mg) declined -91.34% to rank 7, contrasting with $2,359 in August 2026 sales for Classic Brownie (10mg) that now anchors category momentum. The pattern implies ButACake is pivoting demand toward a hero brownie lineup while pruning or repositioning lagging cookies to simplify the Edible mix and lean into products with clear velocity.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

