

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
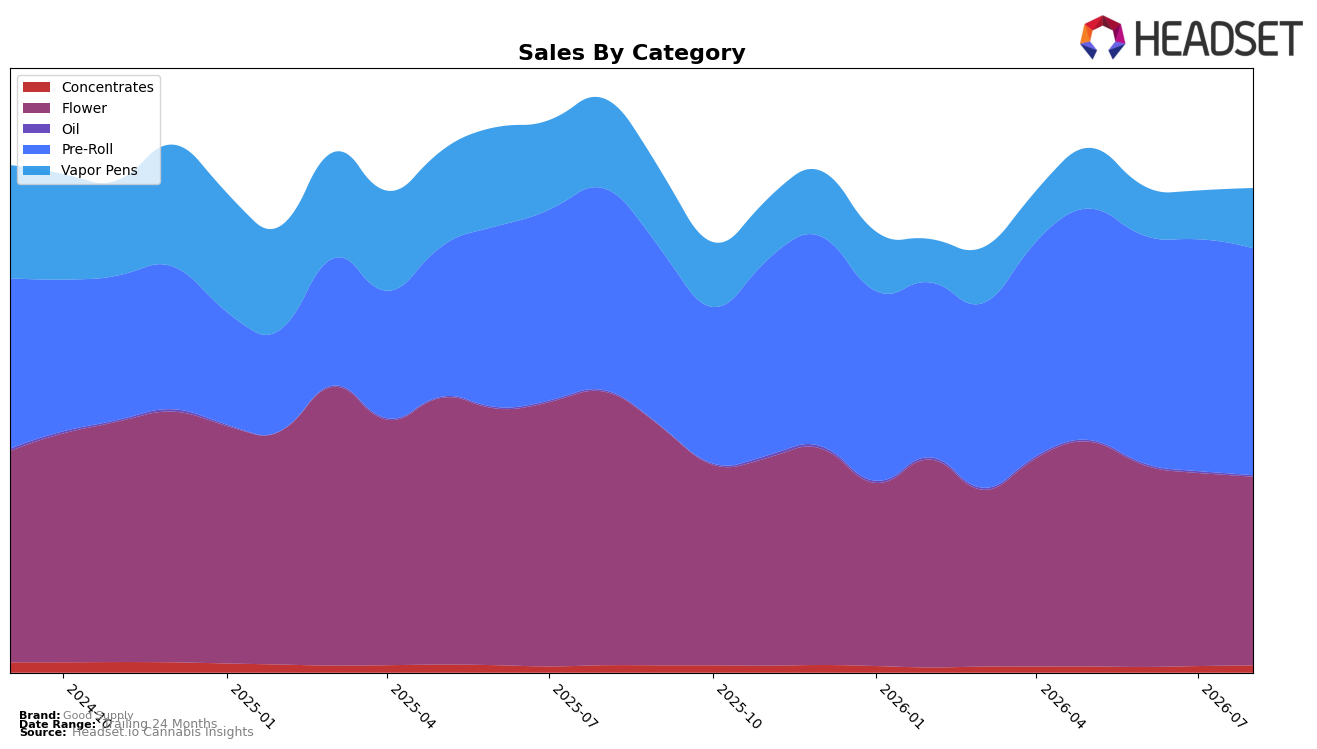
Good Supply’s mix in August 2026 is concentrated in Pre-Roll at 46.34% share (yoy +12.31%, mom -2.18%) and Flower at 38.63% share (yoy -30.81%, mom -2.21%), with Vapor Pens at 12.59% share (yoy -32.19%, mom +22.99%). Concentrates hold 1.81% share (yoy -2.37%, mom +7.29%) and Oil 0.63% share (yoy -0.96%, mom -10.09%). Despite overall brand sales declining 15.36% year over year and average price down 19.00% year over year to $20.62, the category mix shows a pivot toward volume-accretive Pre-Rolls and a tactical rebound in Vapor Pens month over month, implying the brand is trading category exposure to offset Flower contraction.
Holding rank 3 in Flower in British Columbia while Flower share sits at 38.63% suggests reliance on a shrinking anchor, as Flower posted a 30.81% year-over-year decline alongside a 2.21% month-over-month dip. Concurrently, Pre-Roll’s 12.31% year-over-year growth with a 46.34% share and Vapor Pens’ 22.99% month-over-month lift indicate a shift toward categories where price elasticity and promotional depth can capture units as average prices fall 19.00% year over year; the pattern implies Good Supply’s positioning is migrating from a premium-weighted Flower stance toward a value-forward, volume-led portfolio centered on Pre-Rolls with opportunistic re-entry in Vapor Pens.
Competitive Landscape
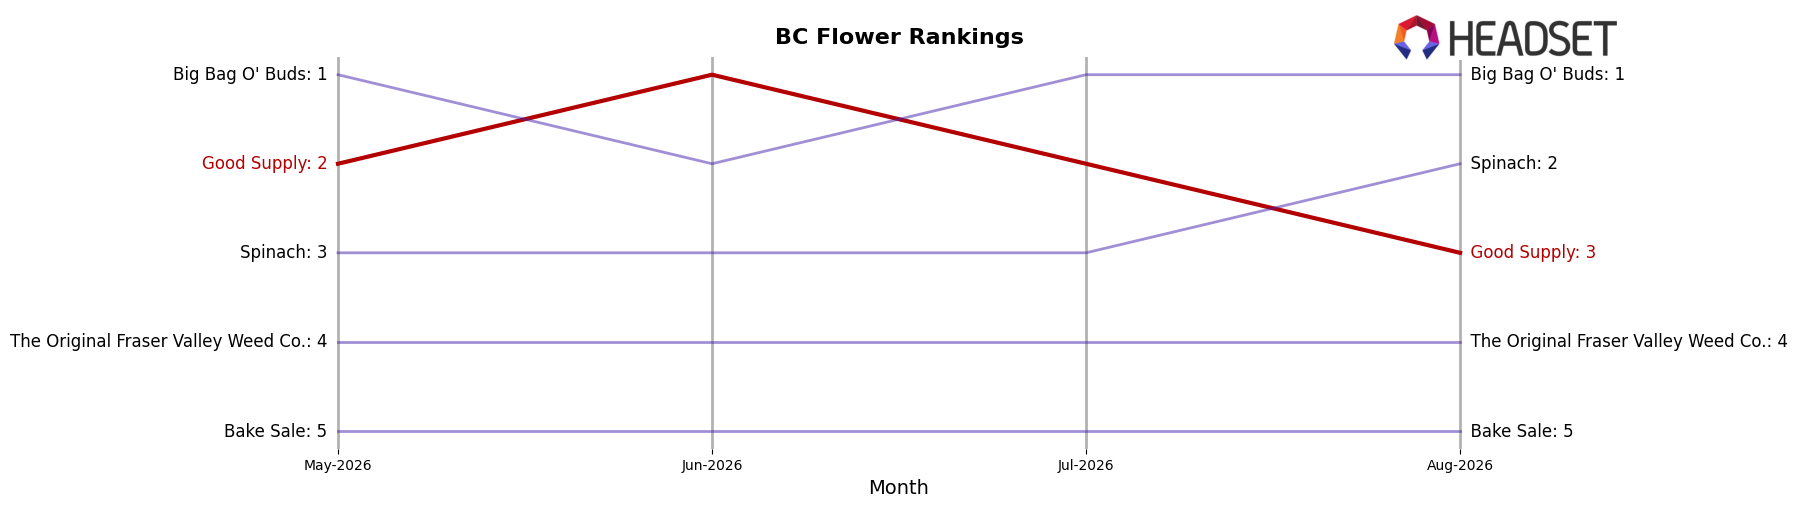
Good Supply sits at rank #3 in BC Flower in August 2026, improving three spots from #6 year over year while slipping one place from #2 in May–July momentum, and it peaked at #1 in June 2026 before easing back; meanwhile, Big Bag O' Buds held #1 year over year and remains #1 now with sales up 33.83%, and Spinach advanced from #4 to #2 with a 54.24% YoY sales lift, outpacing Good Supply’s recent downshift from its June 2026 peak—this pattern implies Good Supply’s trajectory is upward on a 12‑month basis but losing share of the top tier to faster‑rising rivals in the latest months.
Notable Products
The Score Pre-Roll 20-Pack (10g) posted the steepest movement in August 2026 with a -11.6% month-over-month decline while slipping to rank 7, whereas Double Dutchies - Double Up Pre-Roll 2-Pack (2g) held rank 1 despite a -2.5% dip, signaling pressure on larger-count pre-roll formats versus stable 2-packs. Pineapple Express Distillate Cartridge (1g) rose 38.3% MoM to rank 6 as Vapor Pens placed three SKUs in the top 10, while Pre-Rolls occupied six of the top 10 including ranks 1 through 4, concentrating share in two inhalable formats. Double Dutchies - Double Down Pre-Roll 2-Pack (2g) advanced 6.5% MoM at rank 2 alongside a 15.1% lift for Grower's Choice Sativa Pre-Roll (1g) at rank 9, while Ice Cream Rntz (7g) in Flower slid -4.6% at rank 10 with $287,637 in sales. The pattern implies Good Supply is leaning toward smaller-count pre-rolls and accelerating Vapor Pens to sustain leadership while deprioritizing bulk pre-roll and Flower exposure.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

