

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
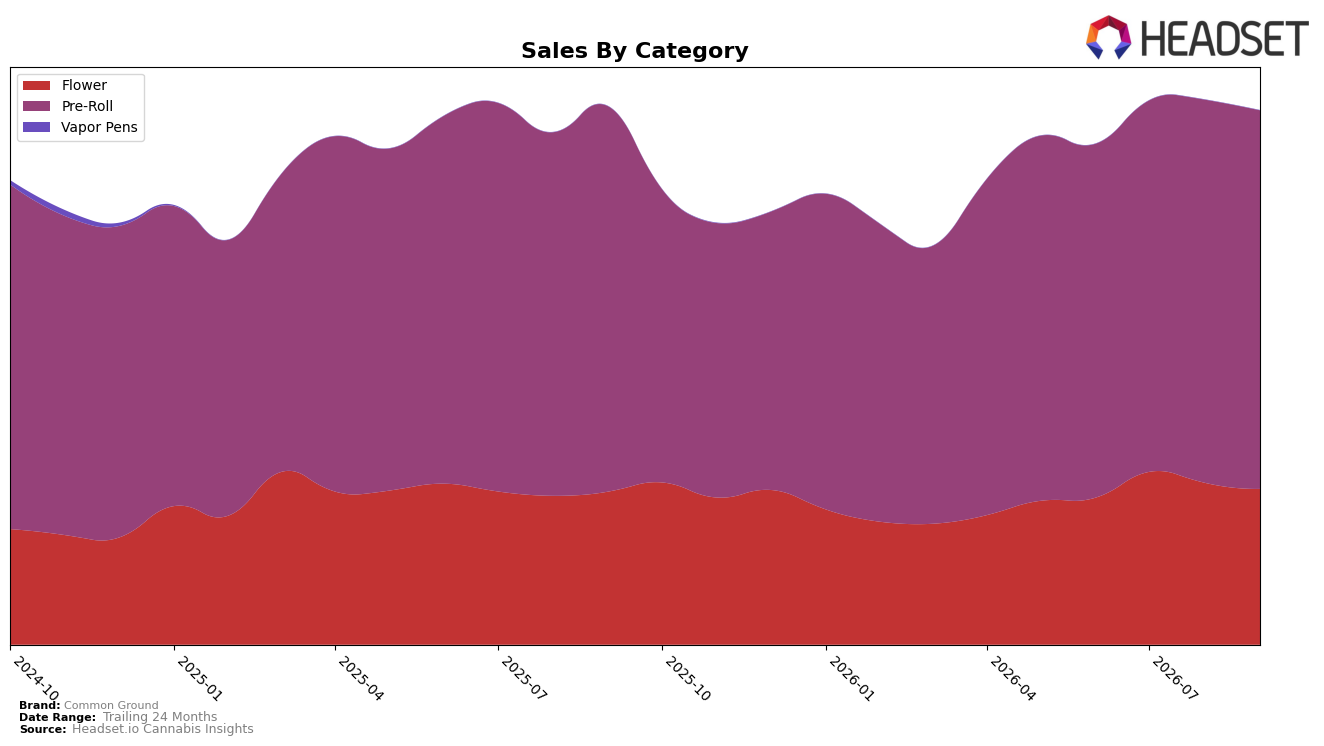
Common Ground’s category mix in September 2026 is concentrated in Pre-Roll at 70.87% share (ranked 26th in Pre-Roll in Saskatchewan) with year-over-year Pre-Roll sales down 1.75% and month-over-month down 1.19%, while Flower holds 29.13% share with year-over-year up 1.77% but month-over-month down 3.80%. Despite a 5.71% decline in average price and a brand-level year-over-year sales contraction of 74.81%, the 24-month sales change of 15.24% suggests the current pullback is cyclical rather than structural; the mix skew toward Pre-Roll alongside a rank of 26 implies scale in the core but limited upward mobility without mix rebalancing or pricing moves.
The slight year-over-year expansion in Flower (+1.77%) versus the contraction in Pre-Roll (−1.75%), combined with sharper month-over-month softness in Flower (−3.80% vs. −1.19% in Pre-Roll), implies that Common Ground’s near-term positioning rests on defending Pre-Roll while using Flower as the lever for incremental share. Being ranked 26th in Saskatchewan Pre-Roll and holding 70.87% of internal sales in that category points to dependence on a segment where marginal gains are harder, so the strategic implication is to shift 2–4 percentage points of mix toward Flower at a measured pace to offset Pre-Roll rank inertia while preserving the price architecture created by the 5.71% average price reduction.
Competitive Landscape
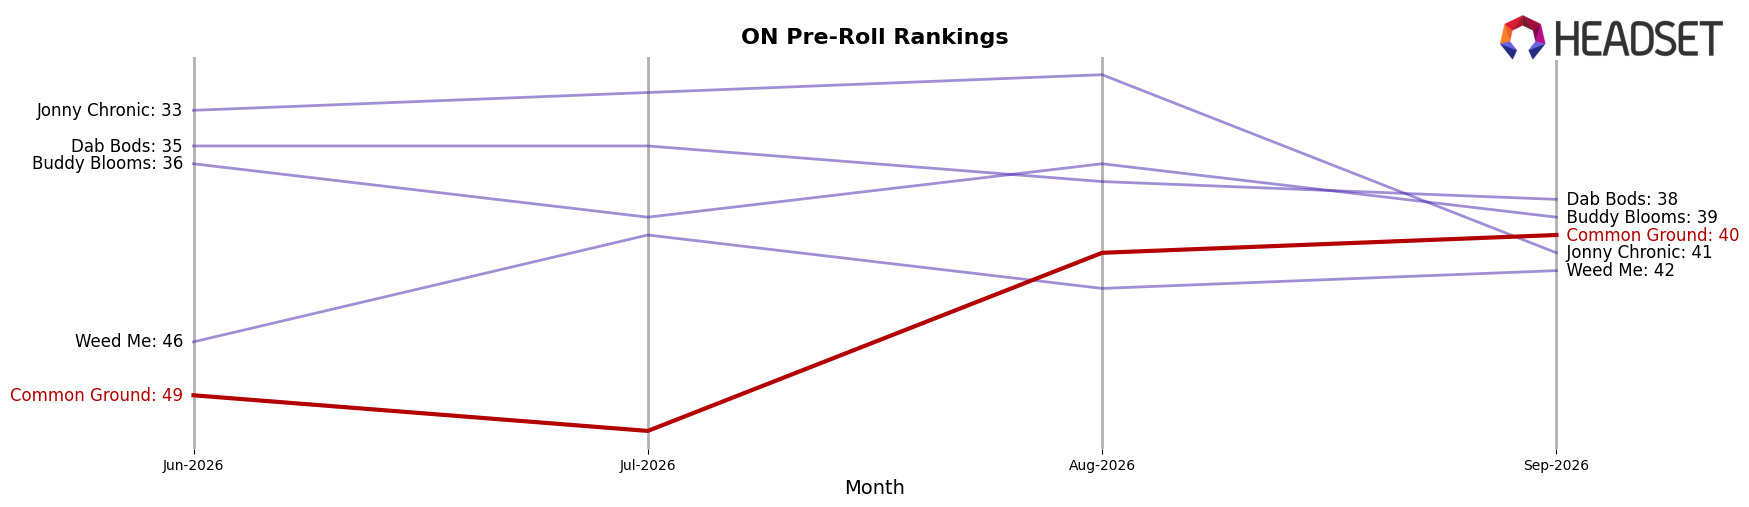
Common Ground sits at rank #40 in ON Pre-Roll in September 2026, down 3 positions year over year from #37, but up 9 spots from June 2026 when it was #49; this current position remains 4 places below its peak of #36 reached in October 2024. Competitive movement at the top tightened the ladder: Back Forty / Back 40 Cannabis climbed from #2 to #1 while growing sales 46.6%, and General Admission slipped from #1 to #2 amid a 38.2% sales decline, creating a spread where Thumbs Up Brand surged from #8 to #3 with 62.1% growth; against this backdrop, Common Ground’s slight YoY rank drop alongside a quarter-on-quarter recovery implies mid-pack share is compressing and that reclaiming the #36–#37 band will require outpacing fast risers rather than merely stabilizing current velocity.
Notable Products
The steepest movement in September 2026 was the Strawberry Pie Pre-Roll 5-Pack (2.5g) dropping 29.9% MoM to rank 8, while Amherst Sour Diesel Pre-Roll 10-Pack (5g) held rank 1 despite a 13.2% MoM decline. Pink Rozay Pre-Roll 2-Pack (2g) rose 26.4% MoM to rank 2 and Cherry Doughnuts Pre-Roll 2-Pack (2g) climbed 23.6% MoM to rank 4, and six of the top ten are Pre-Roll SKUs, signaling a tilt toward multipack convenience even as volatility persists. In contrast, Lemon Pave Milled (7g) slipped 10.2% MoM at rank 10 while Strawberry Pie Milled (7g) gained 12.5% MoM at rank 3, and Guzzlers Milled Flower (7g) added 9.0% MoM at rank 9, implying Flower is steady but ceding spotlight to Pre-Rolls. This mix points to Common Ground consolidating leadership around a flagship large-pack Pre-Roll while pruning underperforming Pre-Roll variants and using a stable Milled Flower base to balance risk.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

