

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
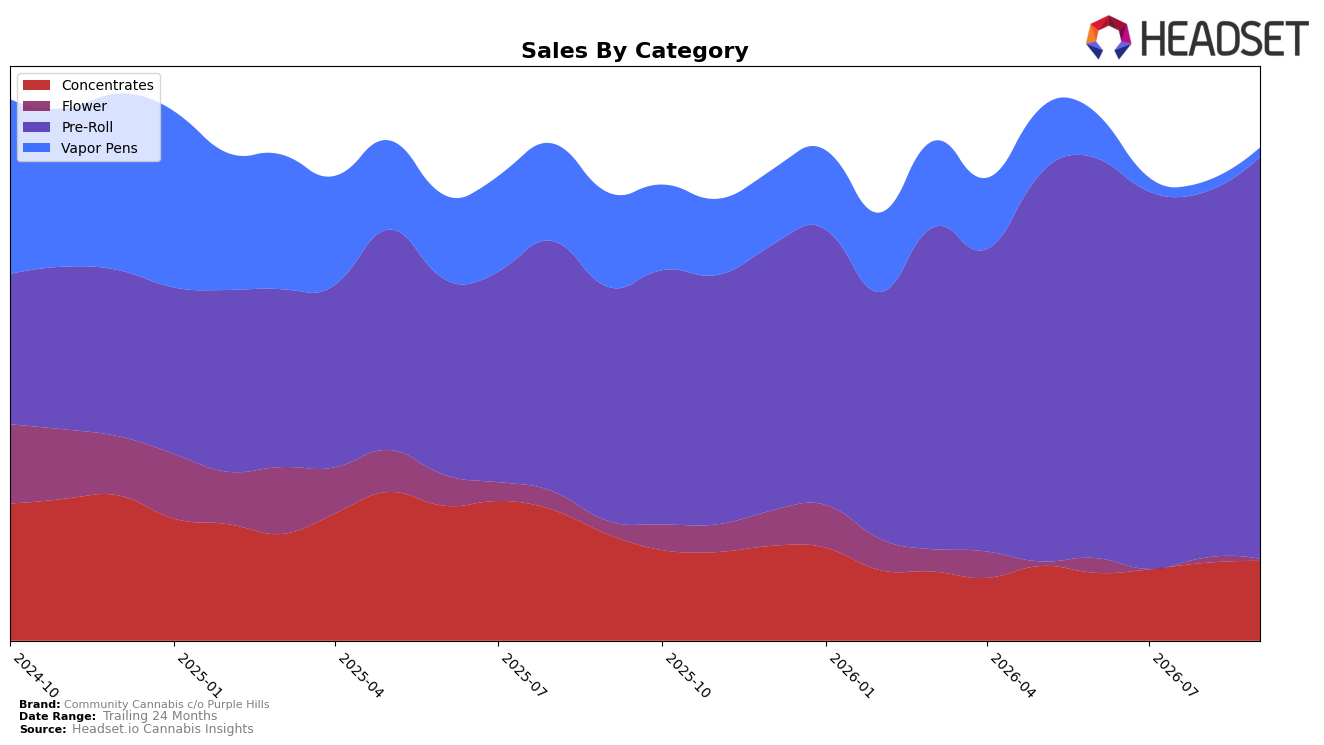
Community Cannabis c/o Purple Hills concentrated 80.62% of September 2026 sales in Pre-Roll, where sales grew 71.15% year over year and 9.88% month over month, while Concentrates held 16.31% share with a 24.45% year-over-year decline but a 2.47% month-over-month uptick. Vapor Pens dwindled to 2.27% share with an 88.19% year-over-year drop and a 9.40% month-over-month decline, and Flower slipped to 0.80% share with a 74.02% year-over-year contraction and a 43.13% month-over-month fall; together these shifts occurred alongside a 23.14% year-over-year decline in average price and a Pre-Roll average price of $12.33. The pattern implies the brand is consolidating around value-priced Pre-Roll while exiting or deprioritizing higher-priced formats, using modest month-over-month stability in Concentrates to buffer mix risk.
With Pre-Roll dominance at 80.62% share and a category rank of 49 in Ontario, the mix suggests a scale-first positioning where volume expansion (71.15% Pre-Roll year-over-year growth) trades off against premium perception implied by the 23.14% average price drop. The steep contractions in Vapor Pens (−88.19% year over year) and Flower (−74.02% year over year), paired with their minimal shares (2.27% and 0.80%), indicate a deliberate narrowing of the portfolio, which likely improves operational focus but concentrates competitive exposure within Pre-Roll; the small month-over-month gain in Concentrates (2.47%) provides an option to re-anchor a secondary platform without diluting the Pre-Roll lead.
Competitive Landscape
Community Cannabis c/o Purple Hills sits at rank #49 in Ontario Pre-Roll for September 2026, a 17-place climb from #66 year over year, and a 7-place rise from #56 in June 2026, marking a new peak rank in September 2026; against the leaders, Back Forty / Back 40 Cannabis moved from #2 to #1 while growing sales 46.6%, and General Admission slipped from #1 to #2 with a 38.2% sales decline, indicating that Community Cannabis c/o Purple Hills is gaining relative footing as share concentrates at the top and volatility opens lanes for mid-pack advancement.

Notable Products
Marrakesh Express Hash (3g) posted the standout move with a 121.3% month-over-month surge and climbed to rank 5, while Indica XL Distillate Cartridge (1.2g) fell 71.9% to rank 7. At the top, TwoFer Pre-Roll 2-Pack (2g) rose 18.2% to rank 1 and Bakery Preroll 14-Pack (7g) in rank 2 edged up 3.2%, meaning two Pre-Rolls occupy the top two ranks and anchor the lineup. Concentrates also accelerated as Sour Lemon OG Shatter (1g) jumped 77.4% to rank 6 and Hybrid Hash (3g) in rank 3 was up 0.7%, indicating a tilt toward value-oriented hash alongside sustained Pre-Roll dominance. The split trend in Vapor Pens—95+ Island Drip Distillate Cartridge (0.95g) up 36.6% at rank 4 versus Purple Stuff Distillate Disposable (0.5g) down 12.8% at rank 8—implies Community Cannabis c/o Purple Hills is prioritizing multi-pack Pre-Rolls and legacy hash formats over disposables as its commercial direction.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

