

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
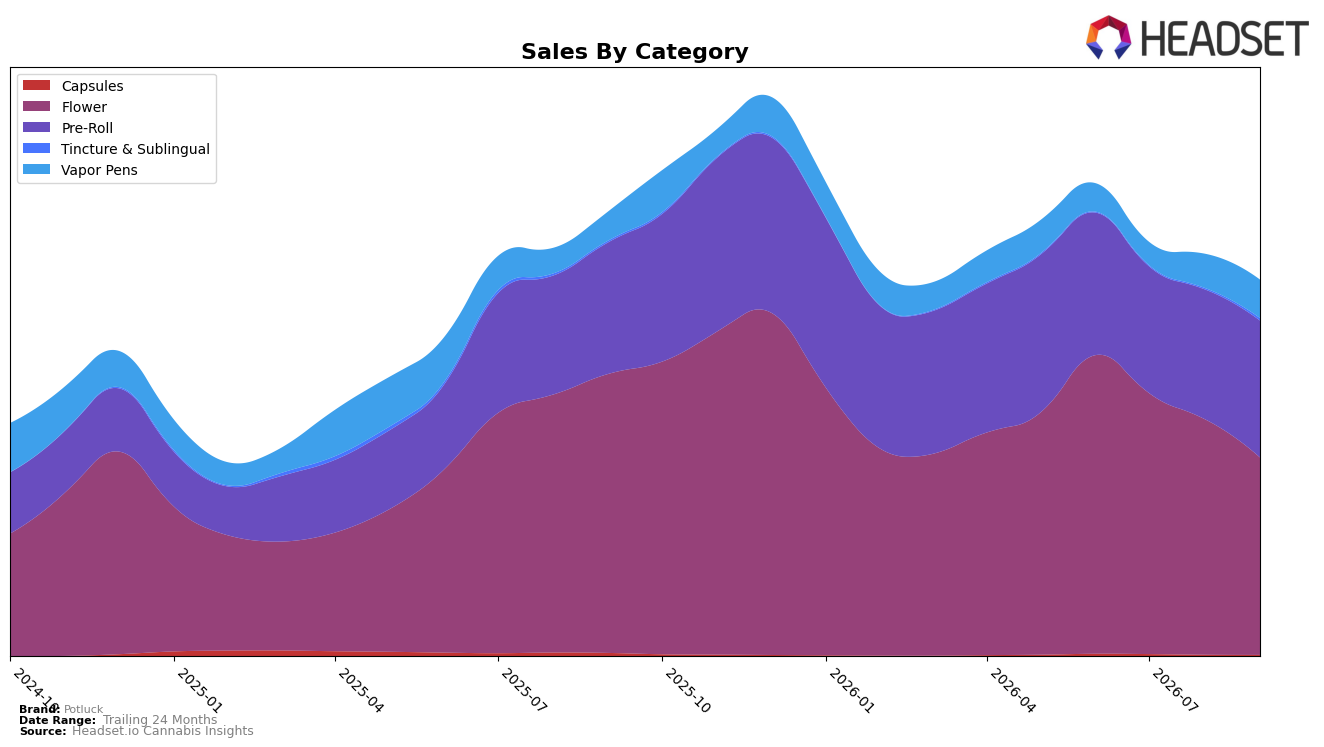
In September 2026, Potluck’s mix skewed toward Flower at 52.57% share, yet Flower contracted by 29.26% year over year and 16.22% month over month, while overall brand sales declined 15.39% YoY and average price fell 10.78%. Pre-Roll expanded 3.996% YoY and 5.45% MoM to 36.41% share, and Vapor Pens rose 32.17% YoY and 12.43% MoM to 10.16% share; Tincture & Sublingual, though only 0.59% share, jumped 55.06% YoY and 104.10% MoM, contrasting with Capsules at 0.27% share dropping 66.07% YoY and 12.88% MoM. With Flower still the largest but shrinking and rank position at 19 in Flower in Ontario, the pattern implies Potluck’s growth engine is shifting away from its historical core toward format-driven segments that are gaining volume despite price compression.
The tilt toward Pre-Roll and Vapor Pens—together accounting for 46.57% share with positive 3.996% and 32.17% YoY growth, respectively—suggests Potluck is repositioning from a Flower-led value proposition toward convenience and inhalable variety, aided by a 10.78% brand-wide price decrease. The surge in Tincture & Sublingual (104.10% MoM, 55.06% YoY) alongside a steep Capsules decline (-66.07% YoY) indicates consumer experimentation consolidating into formats with faster trial velocity; combined with a 16.22% MoM Flower pullback and a 5.45% MoM Pre-Roll uptick, this implies short-term share defense hinges on leaning into ready-to-use and portable offerings while selectively pruning low-traction SKUs.
Competitive Landscape
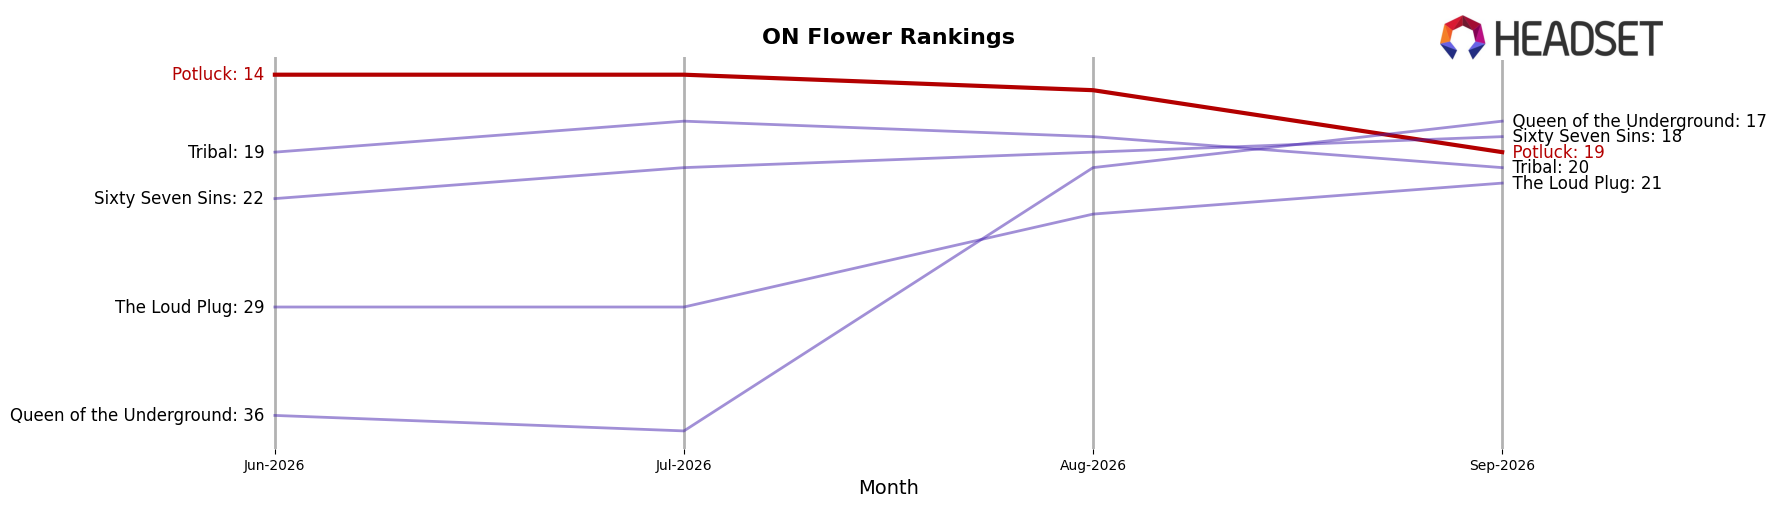
Potluck is ranked #19 in Ontario Flower in September 2026, a 1-position improvement from #20 year over year, but down 5 positions from #14 in June–July 2026 to #19 in September 2026; by contrast, Spinach moved from #3 to #1 and FIGR advanced from #14 to #5 alongside a 51.7% YoY sales increase. With Back Forty / Back 40 Cannabis slipping from #1 to #3 amid a 7.4% YoY sales decline and Shred holding at #2 while growing 13.4% YoY, Potluck’s minor YoY rank lift (+1) coupled with a 5-rank drop since July 2026 implies share is getting redistributed toward faster-moving leaders, and the recent slide from a peak rank of #14 suggests momentum has tilted away from Potluck despite steadier incumbents.
Notable Products
Strawberry Cough Pre-Roll (0.5g) dropped 27.98% month over month to rank 8 while Sugar Shack Pre-Roll (0.5g) fell 10.52% at rank 7, and Berry Cherry Infused Pre-Roll (0.5g) slipped 10.26% but still held rank 1; in contrast, Orange Twist Infused Pre-Roll (0.5g) rose 11.03% at rank 2 and Watermelon Wave Infused Pre-Roll (0.5g) gained 19.90% at rank 3. Four of the top ten SKUs are Infused Pre-Roll variants clustered in ranks 1–3 and 5, while Flower anchors high ticket volume with Beaver Tail (7g) at rank 4 despite a 7.87% decline and Mango Dream (7g) at rank 9 with a 4.99% dip, concentrating dollar exposure in two formats. The mix signals a pivot toward flavor-led Infused Pre-Rolls for traffic and visibility while large-format Flower sustains basket size, implying assortment and promo should prioritize stabilizing volatile non-infused Pre-Rolls and defending flagship Infused positions.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

