

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Curaleaf is stocked at 49 licensed dispensaries across Connecticut, New York, and 8 other states, 21 of them in Connecticut, with the deepest coverage in Norwalk, Bridgeport, Bristol, Cromwell, and East Hartford. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
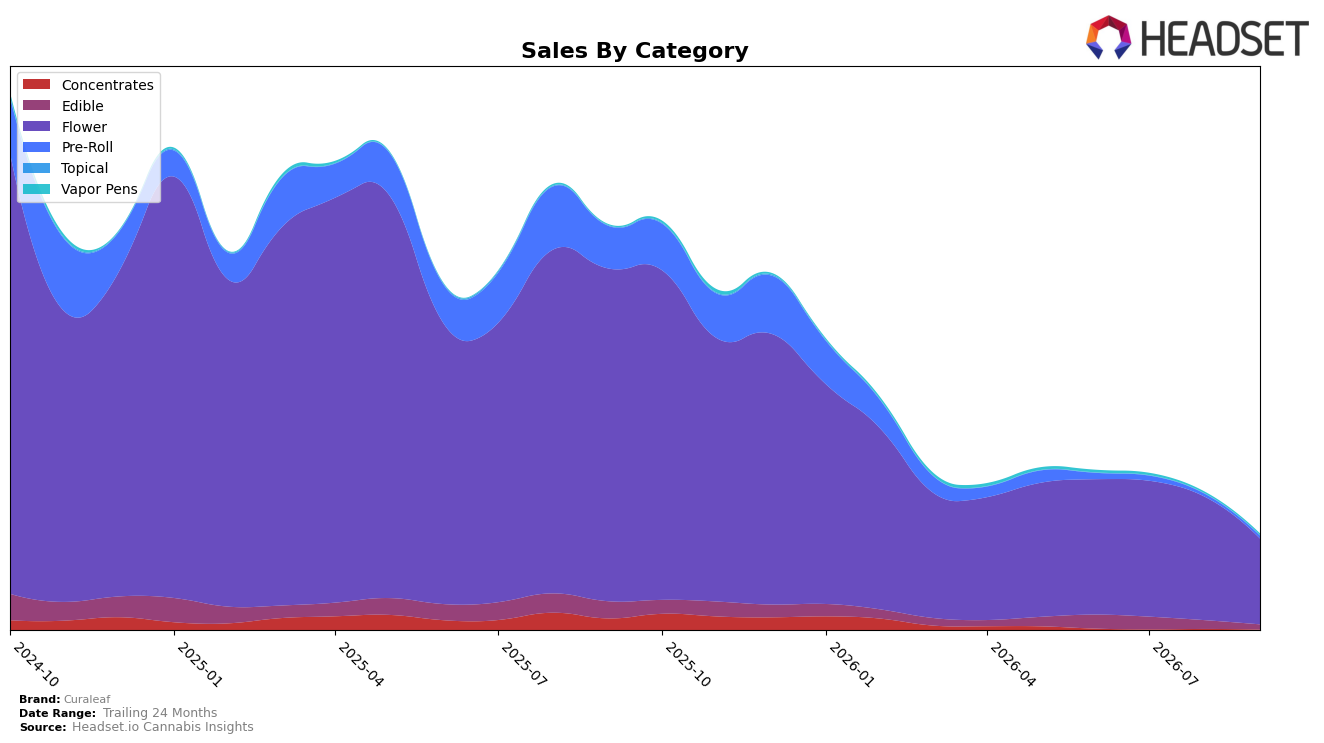
Curaleaf concentrated 90.77% of September 2026 sales in Flower, where sales fell 74.31% year over year and 30.60% month over month, while Edible at 5.07% share declined 71.49% YoY and 43.17% MoM; meanwhile, Pre-Roll at 2.69% share dropped 94.01% YoY but only 1.98% MoM, and Vapor Pens at 1.47% share grew 95.73% YoY and 8.47% MoM. With average price up 3.63% YoY to $28.29 and a state-category rank of 19 in Flower in Arizona, the mix skews toward a contracting flagship segment while a small but expanding Vapor Pens line introduces the only positive volume momentum; the pattern implies the current portfolio is over-indexed to declining formats and underweight in the pocket of growth.
The shift—steep Flower and Edible contractions paired with Vapor Pens expansion—suggests Curaleaf’s positioning is drifting away from value-accessible formats toward a narrower, premium-leaning Flower base (31.21 average price in Flower) and a nascent inhalables rebound, which could trade share for margin if left unchecked. Given a 19th rank in Arizona Flower alongside a 94.01% YoY slide in Pre-Roll and only 2.69% share there, the portfolio signals a need to reallocate toward faster-recovering inhalables while stabilizing Flower price architecture; this implies near-term competitive exposure in Flower and Edible, with Vapor Pens as the attainable wedge for mix-led share recovery.
Competitive Landscape
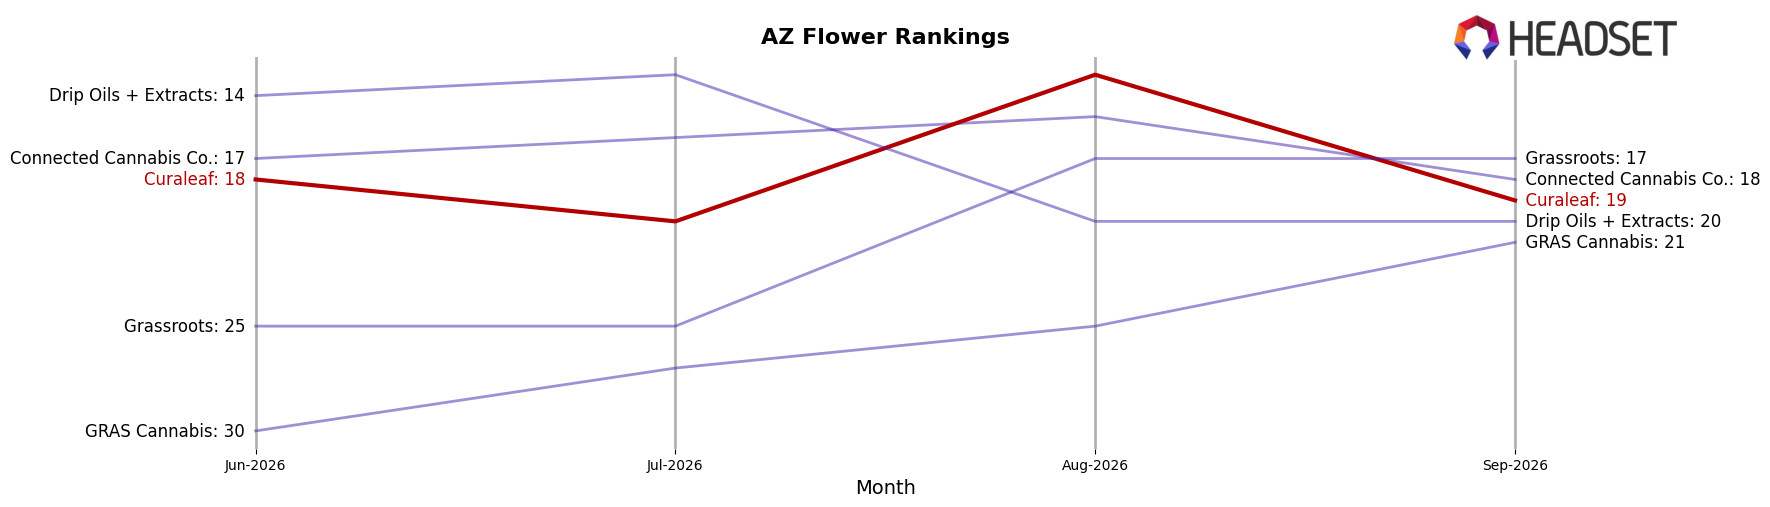
Curaleaf sits at rank #19 in AZ Flower for September 2026, down 5 positions year over year and slipping 1 spot versus June 2026, while its peak at #5 in September 2025 is now 14 places higher than today; in contrast, Just Flower held #1 with a 1-position YoY climb and Loud Pax surged to #5 with a 51-position YoY rise alongside 2,181.5% sales growth, indicating Curaleaf’s relative share of consumer consideration is being compressed by faster-moving rivals and that the downward rank trajectory implies a need to reset assortment or pricing to arrest further slide.
Notable Products
Classic Bites - Lemon Gummies 10-Pack (300mg) posted a -14.9% month-over-month decline and sat at rank 5, while Sweet Baya (14g) fell -27.4% MoM at rank 2, pointing to softness in non-flower and select mid-tier flower. Atomic Breath (14g) rose 37.3% MoM to rank 1 and generated $159,833, and Flower occupied 8 of the top 10 SKUs, indicating a deepening tilt toward larger-format flower over edibles in September 2026. The pattern implies Curaleaf is concentrating demand in flagship flower sizes and accepting volatility in secondary formats to defend share at the top of the menu.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

