

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Shango is stocked at 25 licensed dispensaries across Arizona, Florida, and Oregon, 19 of them in Arizona, with the deepest coverage in Phoenix, Chandler, Glendale, Mesa, and Bullhead City. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
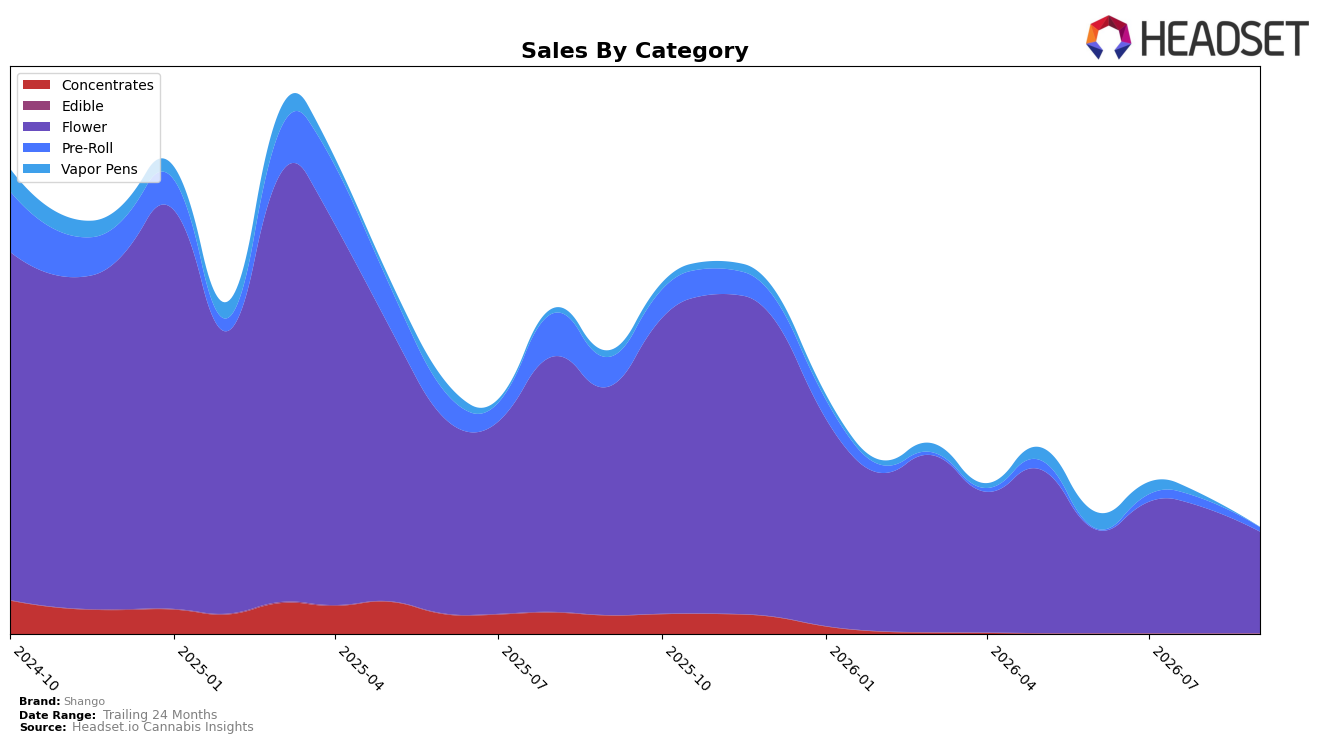
In September 2026, Shango’s mix concentrated 96.15% in Flower with a rank of 22 in Arizona Flower, while Pre-Roll held 3.85% share; Flower declined 55.62% year over year and 19.10% month over month, and Pre-Roll fell 86.18% year over year and 48.26% month over month. Across the portfolio, brand sales were down 62.65% year over year and the average price dropped 28.90% year over year to $19.42, implying a volume mix still tilted to lower-priced Flower even as both categories contracted month over month and year over year.
The concentration in Flower at 96.15% alongside a 19.10% month-over-month slide and a 55.62% year-over-year decline, coupled with a Pre-Roll share of 3.85% and a 48.26% month-over-month drop, positions Shango as a single-category player vulnerable to further rank pressure from 22 in Arizona. The 28.90% year-over-year price decrease and 62.65% brand sales contraction suggest price-led tactics are not offsetting mix risk, implying Shango’s positioning skews toward value Flower where additional assortment breadth or premium tiers may be required to stabilize share and defend ranking.
Competitive Landscape
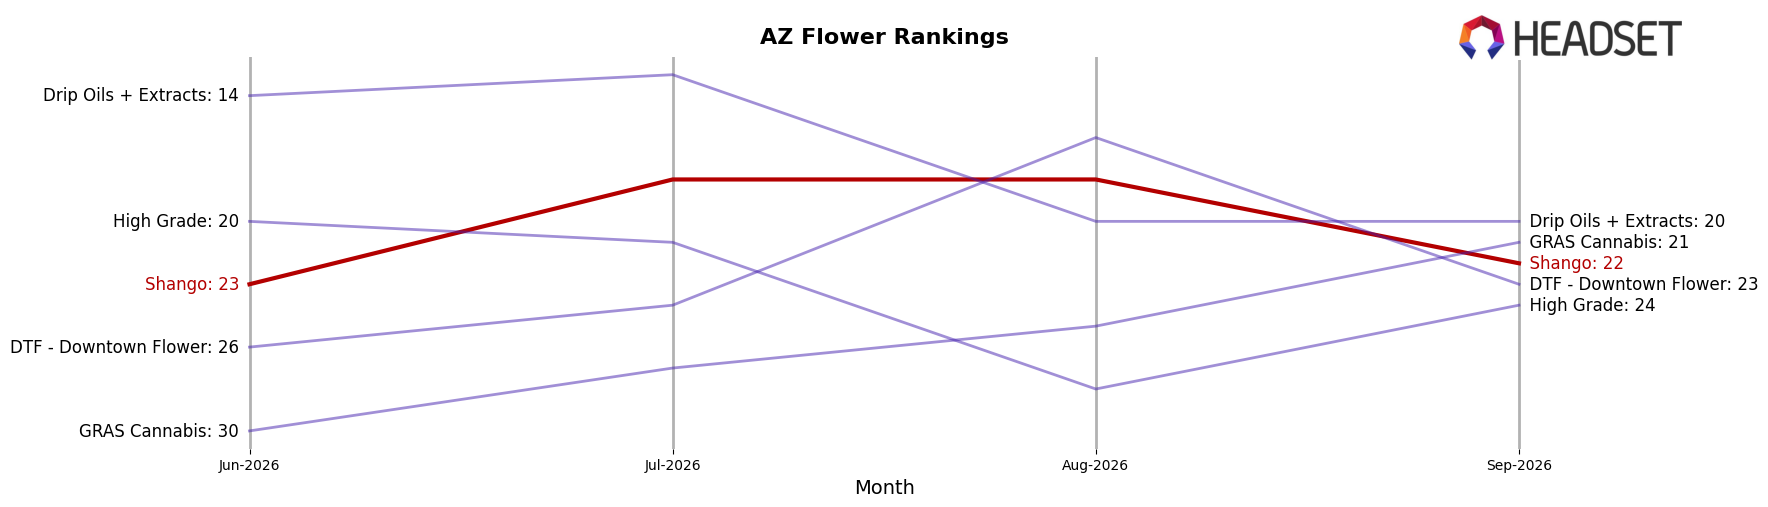
Shango sits at rank #22 in AZ Flower for September 2026, down 13 positions year over year from #9, while improving 1 spot versus June 2026’s #23; the brand’s historical ceiling remains #4 in March 2025. Competitive pressure intensified as Just Flower held #1 with a +1 YoY climb and Loud Pax surged to #5 from #51, a 46-rank leap, contrasting with Shango’s 13-rank YoY decline; additionally, Find. advanced to #2 from #3 while Mohave Cannabis Co. slipped to #3 from #2. This divergence—modest quarter-over-quarter stabilization (+1 rank) alongside double-digit YoY slippage (−13 ranks) amid competitors’ upward mobility—implies Shango is in a defensive posture where reclaiming share will require outpacing faster-rising incumbents rather than relying on reversion to its March 2025 peak.
Notable Products
Blue Zushi (14g) posted the largest month-over-month surge at 106.97% to reach rank 2, while Pink Cherry Infused Shake (14g) rose 36.56% and held rank 1. Caramel Cooks Pre-Roll (1g) fell 42.11% to rank 7, and Frosted Donuts (14g) declined 35.44% at rank 9. With eight of the top ten SKUs in Flower and only two in Pre-Roll, the mix indicates Shango is consolidating around mid-size Flower formats where velocity and rank gains are concentrating.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

