

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
High Grade is stocked at 85 licensed dispensaries across Michigan and Arizona, 55 of them in Michigan, with the deepest coverage in New Buffalo, Detroit, Flint, Grand Rapids, and Lansing. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
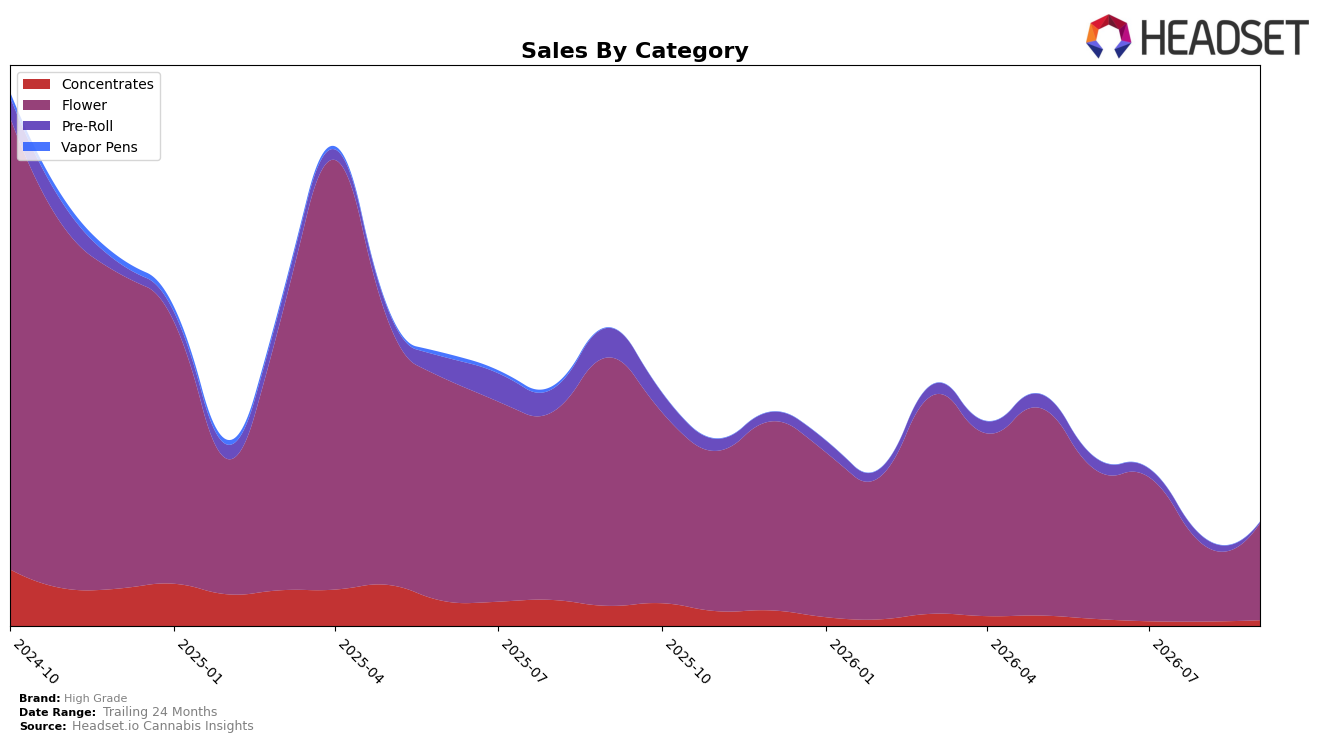
High Grade’s category mix in September 2026 tilted heavily toward Flower at 93.55% share, with year-over-year sales down 61.07% and month-over-month sales up 28.04%, while Concentrates held 5.52% share with a 71.62% YoY decline and a 30.72% MoM gain. Pre-Roll collapsed to 0.93% share with a 96.72% YoY decline and an 86.49% MoM drop, and the average price fell 29.17% YoY to $9.99, implying price-led volume defense. The mix concentration alongside a Flower rank of 24 in Arizona suggests that September 2026 momentum came from tactical pricing in core Flower rather than breadth across formats.
The simultaneous 28.04% MoM lift in Flower and 30.72% MoM lift in Concentrates, alongside a 86.49% MoM contraction in Pre-Roll, indicates a pivot toward fewer, higher-throughput SKUs where price elasticity is working; the 61.07% YoY Flower decline versus a 71.62% YoY drop in Concentrates narrows the relative performance gap. Holding a 93.55% mix in Flower while sitting at rank 24 in Arizona implies that near-term share capture hinges on defending price points and pack sizes in Flower and selectively rebuilding Concentrates, while deprioritizing Pre-Roll until velocity recovers from its 96.72% YoY slide.
Competitive Landscape
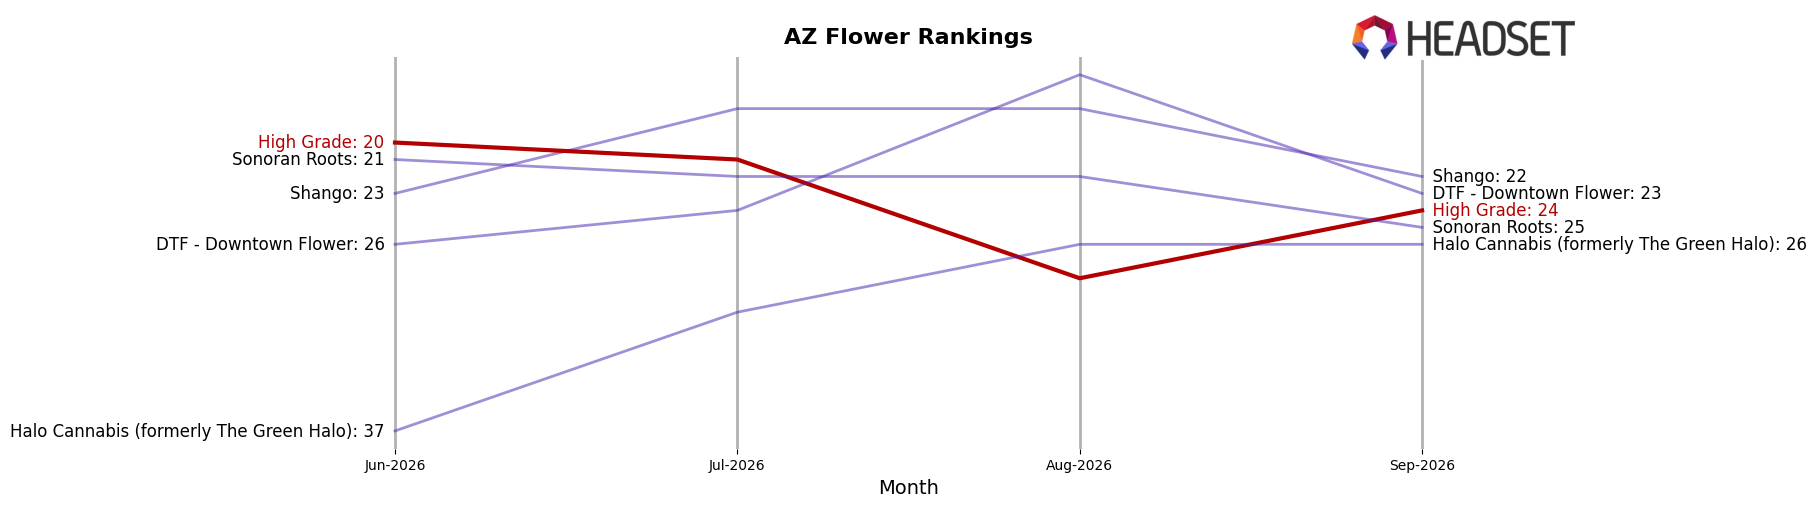
High Grade sits at rank #24 in AZ Flower in September 2026, down 18 positions year over year from #6, and 4 spots below its June 2026 position at #20, while its peak of #4 in April 2025 now sits 20 places higher than today. In contrast, Just Flower held #1 year over year and remains #1 today as its sales grew 29.0%, and Find. advanced from #3 to #2 on 56.6% YoY growth; by comparison, High Grade’s downward rank shift alongside leaders moving up indicates share consolidation at the top and a need to counter momentum loss.
Notable Products
Zkittlez Shake (Bulk) posted the steepest movement in September 2026 with a -64.5% month-over-month drop while sitting at rank 5, a sharper decline than Sticky Buns (Bulk) at rank 8 with -27.5%, implying price-sensitive demand for value formats. GG #4 Smalls (14g) holds rank 1 despite no reported month-over-month rate, whereas Plasma Gas (3.5g) at rank 2 and The Soap (3.5g) at rank 3 suggest premium eighths anchor the leaderboard even as bulk SKUs retrench. With all top 10 SKUs in Flower and at least four of the top ten concentrated in Shake/Bulk or 14g value packs, the mix skews toward high-volume Flower formats despite volatility. This pattern implies High Grade is consolidating around Flower dominance while reassessing bulk-value positioning to protect rank stability and margin mix.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

