

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
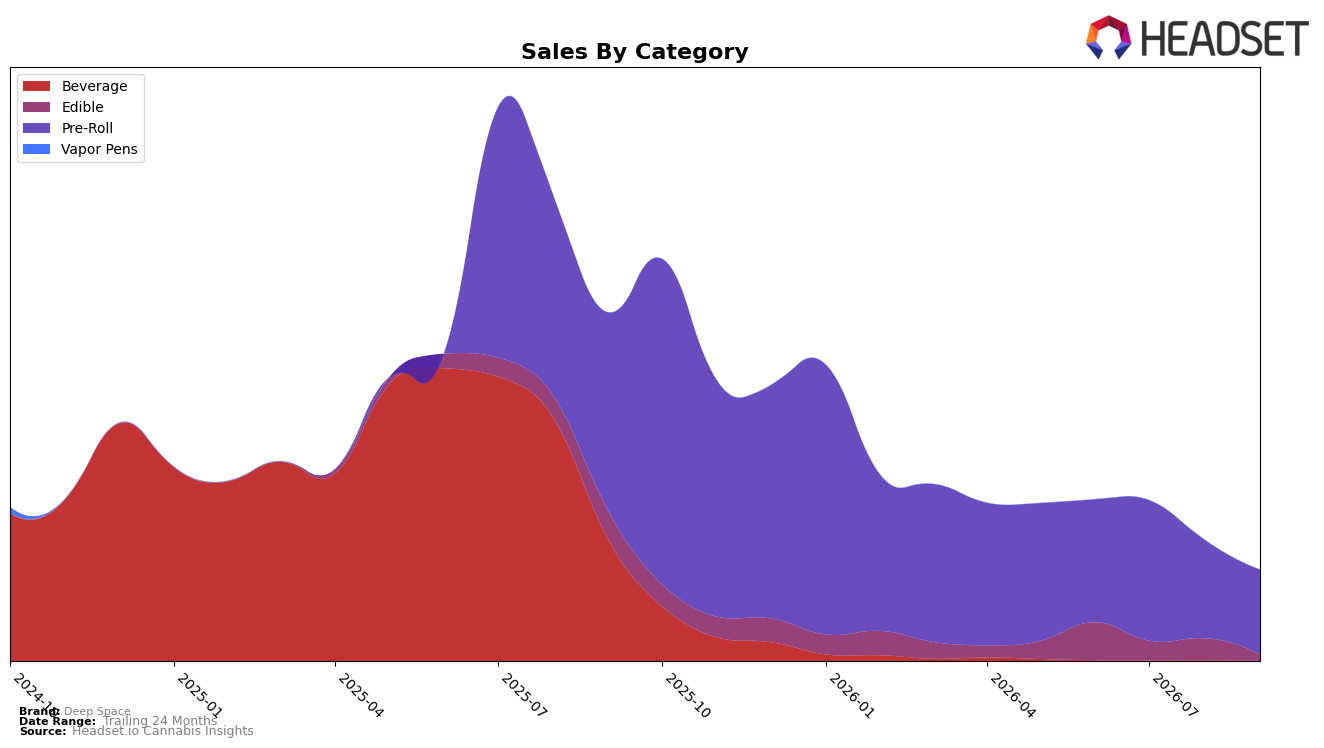
In September 2026, Deep Space concentrated 93.61% of sales in Pre-Roll, with Edible reduced to 6.39% share; versus September 2025, Pre-Roll declined 57.22% YoY and Edible fell 79.48% YoY, while month over month Pre-Roll slipped 13.70% and Edible dropped 73.30%. Despite an average price up 65.58% YoY to $17.94, category-level volume contraction is acute, and the collapse in Edible share alongside Pre-Roll’s smaller but still material retrenchment implies demand is consolidating into a single format with heightened price sensitivity.
The pivot toward Pre-Roll at 93.61% share coupled with a 13.70% MoM decline signals overexposure to a weakening primary format, and the 73.30% MoM decline in Edible suggests limited cross-category cushioning when price or supply shifts occur. With brand sales down 73.97% YoY alongside a 65.58% YoY price rise, the mix shift implies Deep Space is trading fewer units at higher prices, compressing reach and risking further rank slippage in Saskatchewan if assortment breadth and price tiers are not recalibrated.
Competitive Landscape
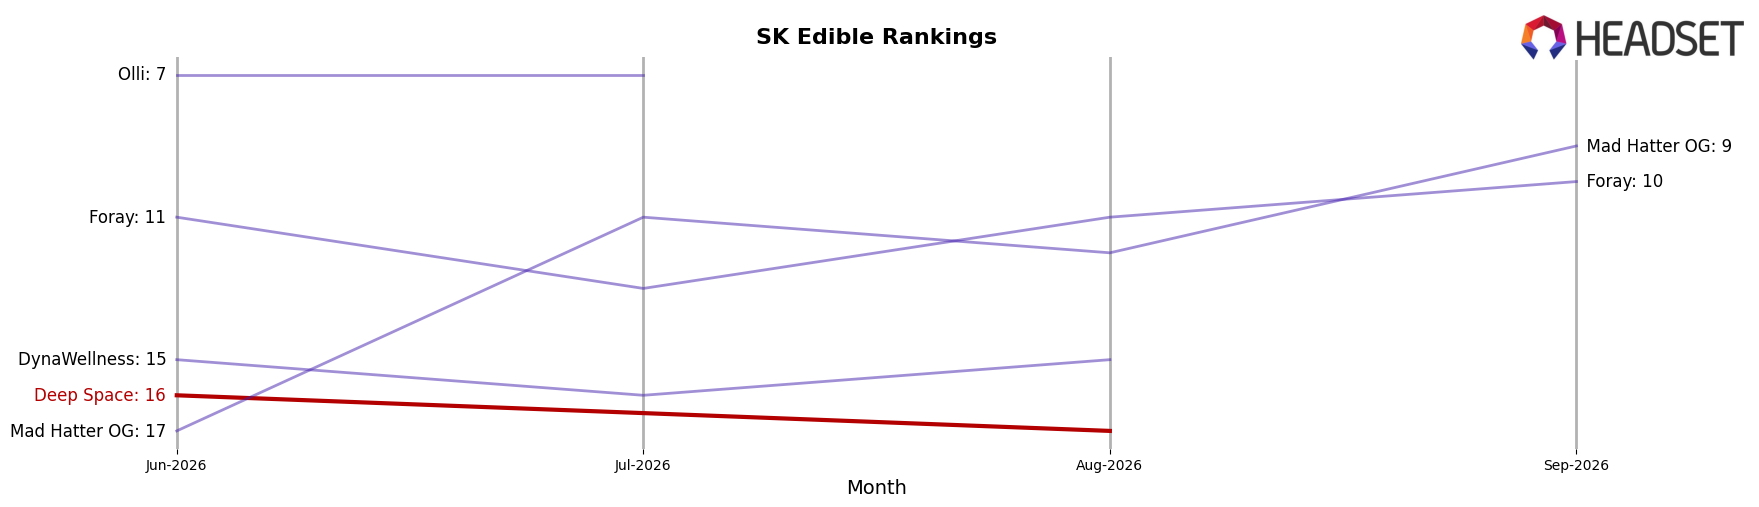
Deep Space ranks #19 in SK Edible in September 2026, down 7 positions year over year from #12, and 3 spots lower than June 2026’s #16; this follows a peak at #12 in September 2025, marking a 7-rank slide from that high. Competitive pressure is directional: Wyld is steady at #1 with a 63.6% YoY sales increase while Wana surged from #19 to #5 alongside a 2,880.7% YoY sales jump, outpacing Deep Space’s rank movement and compressing share opportunities near the teens. With top competitors either maintaining #1 or leaping 14 ranks into the top 5, the pattern implies Deep Space’s downward trajectory toward the high teens is tied to accelerated gains among leaders and constricting mobility around ranks #12–#20.
Notable Products
Space Propulsion - Sour Pulsar Peach Gummy (10mg) posted the largest month-over-month surge at +72.4% and reached rank 4, while Xpress - Limon Splashdown Gummy (10mg) fell -74.3% to rank 2, marking a volatile edible mix that shifts attention to niche SKUs rather than broad volume plays. Milky Way Melon Infused Pre-Roll 3-Pack (1.5g) dropped -21.9% yet held rank 1, and with two Pre-Rolls in the top three, the category concentration suggests stable leadership despite softer momentum. Big Bang Berry Infused Pre-Roll 3-Pack (1.5g) inched up +2.0% at rank 3, and the -68.2% slide for Space Propulsion - Sour Strawberry Void Gummy (10mg) at rank 5 contrasts with the edible outlier’s gain, implying SKU-level cannibalization within Edibles rather than category-wide strength. The mix points to Deep Space leaning on Pre-Roll incumbents for baseline share while probing Edibles with experimental variants to capture opportunistic spikes rather than sustained lift.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

