

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
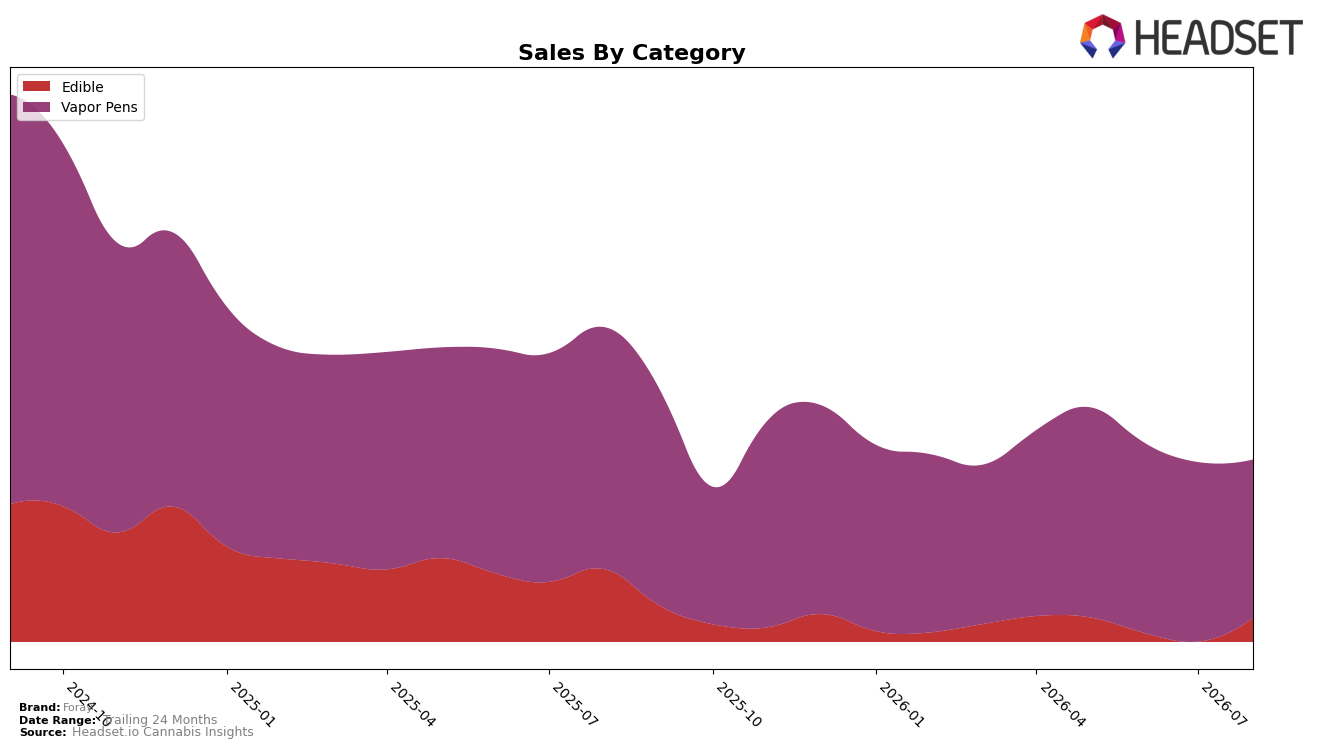
Foray’s mix in August 2026 concentrated 66.27% of sales in Vapor Pens and 33.73% in Edible, with Vapor Pens down 23.61% year over year and 7.30% month over month while Edible fell 25.83% year over year but grew 21.14% month over month; the overall brand sales declined 24.38% year over year alongside a 1.19% drop in average price. In British Columbia Vapor Pens, the brand sat at rank 21, implying that the MoM rebound in Edible is not yet large enough to offset share at the category rank level, and the tilt toward a higher-price Vapor Pen mix (average $20.92 versus $15.39 in Edible) is pressuring unit velocity despite short-term Edible momentum.
The pattern indicates Foray is over-indexed to a declining anchor where Vapor Pens carry two-thirds of sales yet contract faster month over month than Edible expands, and price positioning near $18.66 on average is not catalyzing share gain within rank 21. With Edible expanding 21.14% month over month against a 7.30% month-over-month pullback in Vapor Pens and a 25.83% versus 23.61% year-over-year decline split, the implied path is to reweight mix toward Edible to stabilize volume and use the price gap between $20.92 in Vapor Pens and $15.39 in Edible to shape pack/size strategy that converts MoM interest into sustained share, rather than relying on a category where rank 21 suggests limited upside without a sharper pricing or format pivot.
Competitive Landscape
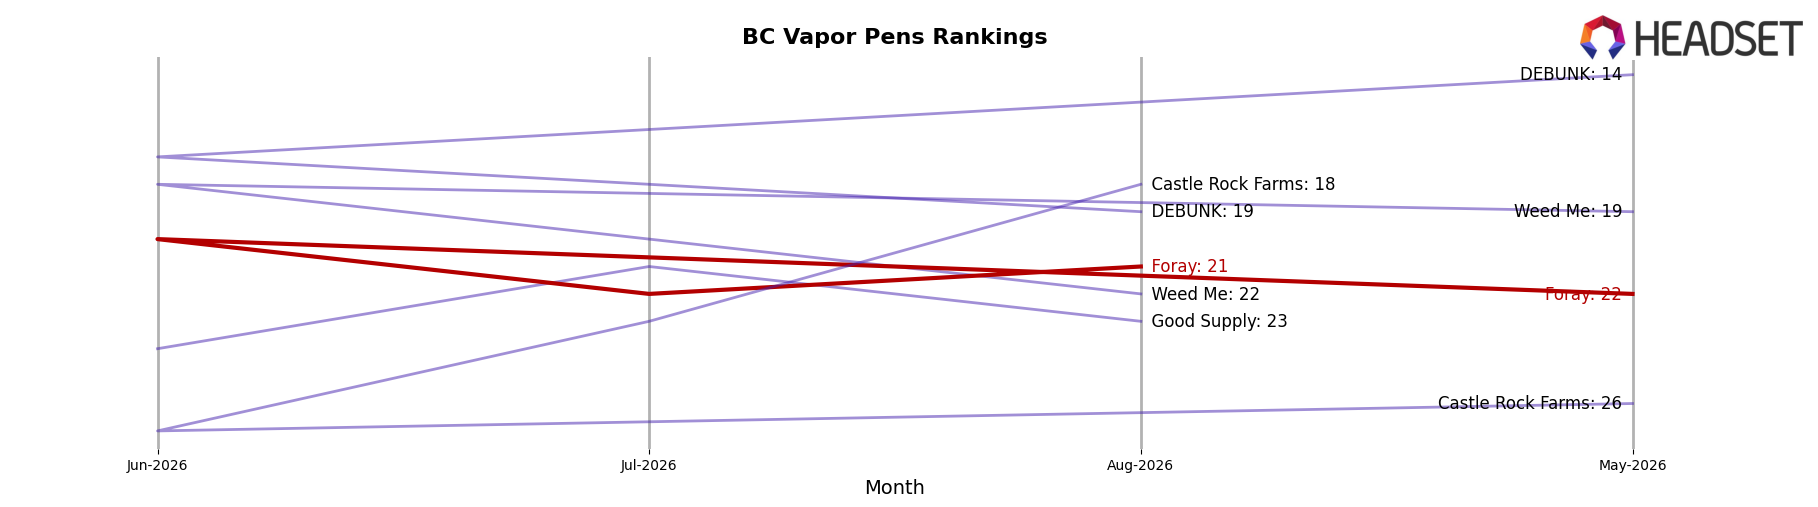
Foray sits at rank #21 in BC Vapor Pens in August 2026, unchanged YoY from #21, while nudging up 1 place from #22 three months ago; in contrast, Spinach climbed from #3 to #1 and BoxHot slipped from #1 to #2, signaling intensified top-tier churn that Foray has not converted into rank gains. Although Foray’s historical peak was #15 in September 2024, the current #21 and flat YoY rank change of 0 positions, alongside a competitive set where Back Forty / Back 40 Cannabis advanced from #7 to #5 and General Admission edged from #2 to #3, indicates share is consolidating above Foray’s tier rather than cycling into the mid-pack; the implication is that without a catalyst to break past the #20 threshold, the brand risks being locked into a narrow #20–#22 band despite prior peak momentum.
Notable Products
Edi's Peppermint Mini Chocolate 20-Pack (10mg) posted the steepest decline in August 2026 at -56.9% MoM and slid to rank 10, while Blackberry Cream Distillate Disposable (0.3g) dipped -7.6% MoM but held rank 1. Indica Distillate Disposable (0.3g) rose 20.8% MoM into rank 7 even as Tangie Crush Distillate Disposable (0.3g) fell -8.9% MoM at rank 5, indicating mix rotation within Vapor Pens rather than category-wide contraction.
Four of the top ten are Vapor Pens while three are Edibles, with the CBD/THC 1:1 Mango Haze Distillate Disposable Pen (0.3g) dropping -11.9% MoM to rank 8 as Edi's - CBD Blood Orange Soft Chews 30-Pack (600mg CBD) advanced 25.2% MoM at rank 2. Fast Edi's- CBD/CBN/THC Blackberry Lavender Soft Chews 30-Pack (300mg CBD, 75mg CBN, 10mg THC) gained 20.6% MoM at rank 3, suggesting August 2026 demand tilted toward functional edibles while Foray maintains a premium position in Vapor Pens anchored by a $176,254 leader.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

