

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
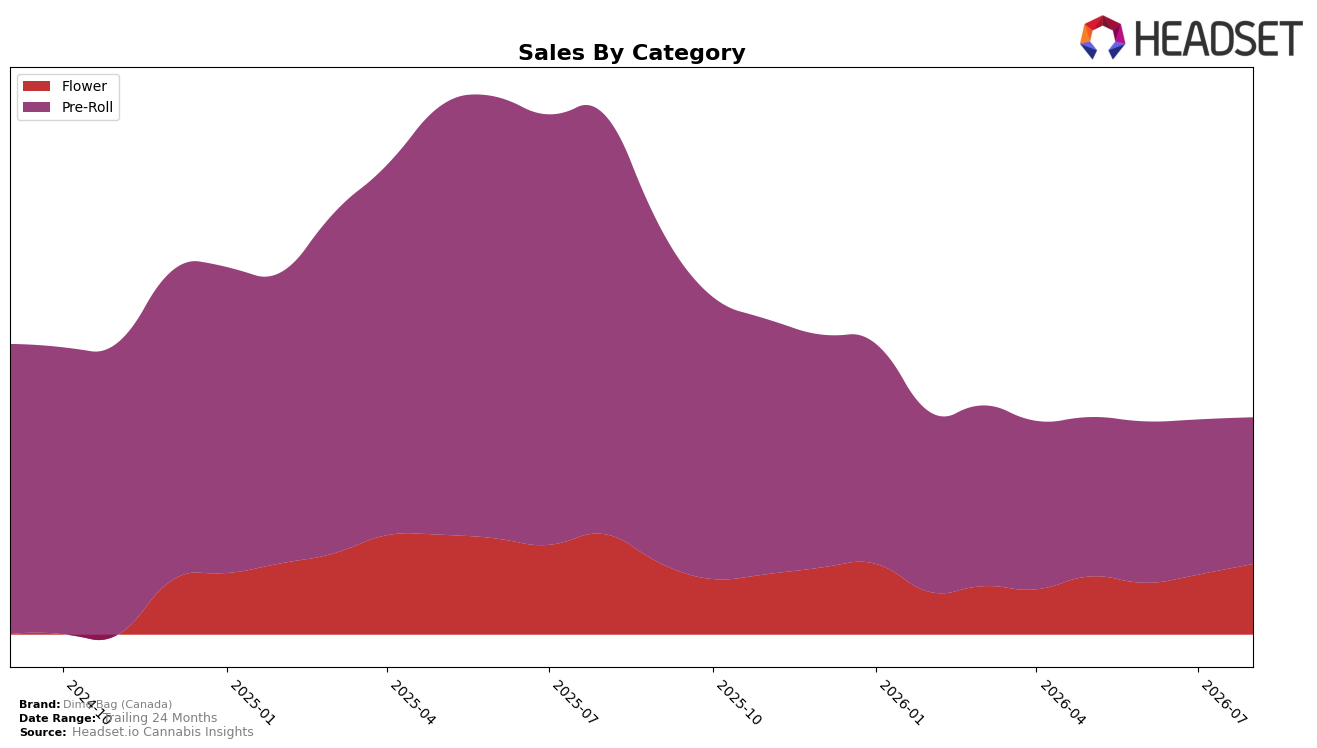
In August 2026, Dime Bag (Canada) derived 67.56% of sales from Pre-Roll and 32.44% from Flower, with Pre-Roll down 65.11% year over year and down 5.49% month over month, while Flower declined 29.84% year over year but rose 17.83% month over month. The average price rose 31.77% year over year to $14.23, contrasting with category-level prices where Pre-Roll averaged $10.07 and Flower averaged $101.46, and the brand held rank 26 in Pre-Roll in Ontario. The pattern implies a pivot away from volume-led Pre-Roll toward margin-accretive Flower as MoM momentum concentrates in the smaller category amid broad YoY contraction.
With total brand sales down 58.32% year over year and Pre-Roll still at 67.56% share despite a 5.49% month-over-month decline, the 17.83% month-over-month gain in Flower at 32.44% share suggests mix rebalancing that can cushion further rank erosion from position 26 in Ontario. The juxtaposition of a 31.77% year-over-year price increase alongside a 65.11% year-over-year Pre-Roll decline indicates price elasticity pressure in the primary category, implying that near-term positioning should emphasize differentiated Flower offerings while stabilizing Pre-Roll price-pack architecture to prevent additional share leakage.
Competitive Landscape
Dime Bag (Canada) sits at rank #26 in ON Pre-Roll in August 2026, down 20 positions from its peak of #6 in August 2025 but just 1 spot lower than its May–July average at #25, indicating a short-term stall against a longer-term slide. Competitive pressure is acute: Back Forty / Back 40 Cannabis climbed from #2 to #1 with 56.6% YoY sales growth while Spinach jumped from #14 to #5 with 81.8% YoY growth; by contrast, Jeeter slipped from #3 to #4 amid a 44.5% YoY sales decline. The mixed competitive shifts—leaders advancing (ranks #2→#1 and #14→#5) while others retrench (#3→#4)—imply that Dime Bag (Canada)’s descent from #6 to #26 is more about losing share to fast-rising value players than a broad market contraction, signaling the need to reposition formats or price tiers to regain rank.

Notable Products
Doozies Tropical Pocket Puffs Pre-Roll 20-Pack (10g) delivered the standout move in August 2026 with +93% month over month, jumping into rank 8 while Diesel Pocket Puffs Pre-Roll 4-Pack (2g) fell -14% but held rank 2; with eight of the top ten SKUs in Pre-Roll, the mix tilts toward multi-pack inhalables at varying price tiers. Funky Pocket Puffs Pre-Roll 4-Pack (2g) dropped -35% and slid to rank 5, whereas Tropical Pocket Puffs Pre-Roll 4-Pack (2g) edged +3% to defend rank 1, indicating fragmentation inside the Pocket Puffs line even as the family anchors share. Purple Poison (28g) climbed +23% to rank 6 and Kush Dreams (28g) rose +34% to rank 7, and together these Flower entries add a counterweight to Pre-Roll reliance despite a single Pre-Roll SKU generating $284,672. The pattern implies Dime Bag (Canada) is leaning into Pre-Roll scale via multi-pack innovation while selectively elevating 28g Flower to diversify basket drivers.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

