


Market Insights Snapshot
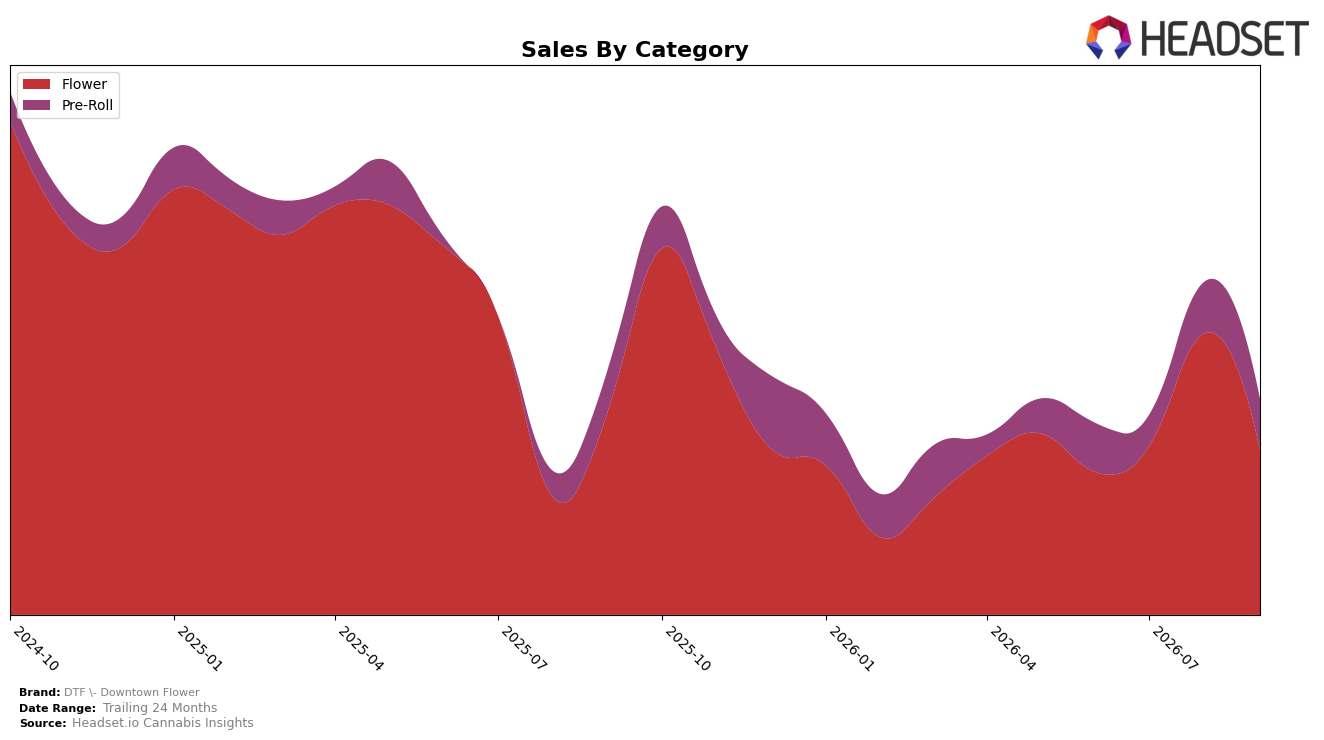
DTF - Downtown Flower concentrated 63.20% of September 2026 sales in Flower (rank 23 in Flower within Arizona), while Pre-Roll accounted for 36.80%. Year over year, Flower contracted 13.03% as Pre-Roll expanded 6.26%, and month over month Flower declined 30.26% while Pre-Roll was effectively flat at -0.19%. With overall brand sales down 6.80% year over year and average price down 14.94%, the mix tilted toward lower-priced Pre-Rolls at 36.80% share, implying unit-led volume protection that did not offset the 30.26% monthly pullback in Flower.
The shift toward Pre-Roll (+6.26% YoY and -0.19% MoM) alongside a 14.94% average price reduction suggests a trade-down dynamic that pressures premium Flower, where rank sits at 23 in Arizona and category sales fell 13.03% YoY. With Flower still 63.20% of mix but down 30.26% MoM, the brand’s reliance on a shrinking, higher-price category elevates risk, implying that maintaining or improving rank will require either mix rebalancing toward stable Pre-Roll or price-pack architecture that narrows the gap without deepening the 24-month sales decline of 35.66%.
Competitive Landscape
DTF - Downtown Flower sits at #23 in September 2026, up 2 spots YoY from #25 and 3 spots better than its three-month mark at #26, while remaining well below its #10 peak from October 2024; meanwhile, Just Flower held at #1 with a 29.0% YoY sales increase as Find. climbed from #3 to #2 on 56.6% YoY growth, and Loud Pax surged from #51 to #5 with 2181.5% YoY sales growth, indicating DTF - Downtown Flower’s modest rank improvement is occurring amid rapid upward mobility at the top and suggests its current trajectory points to incremental share defense rather than a return to peak positioning.

Notable Products
Premium - Fresh Fritter Pre-Roll (1g) posted the steepest decline in September 2026, down 7.6% month over month while holding rank 2, and Kona Berries Pre-Roll (1g) slipped 5.6% MoM at rank 8. Kosher Kush Pre-Roll (1g) led the chart at rank 1 with no reported MoM change, and Wingsuit (3.5g) was the only Flower SKU in the top 10 at rank 7 despite generating $29,250. With nine of the top ten products in Pre-Roll, the assortment is concentrated in a single format and the modest declines at ranks 2 and 8 suggest price-pack or strain rotation tuning rather than a shift away from Pre-Rolls.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

