

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Eden Solventless is stocked at 17 licensed dispensaries across Maryland and Oklahoma, 16 of them in Maryland, with the deepest coverage in Annapolis, Bethesda, Cumberland, Ellicott City, and Federalsburg. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
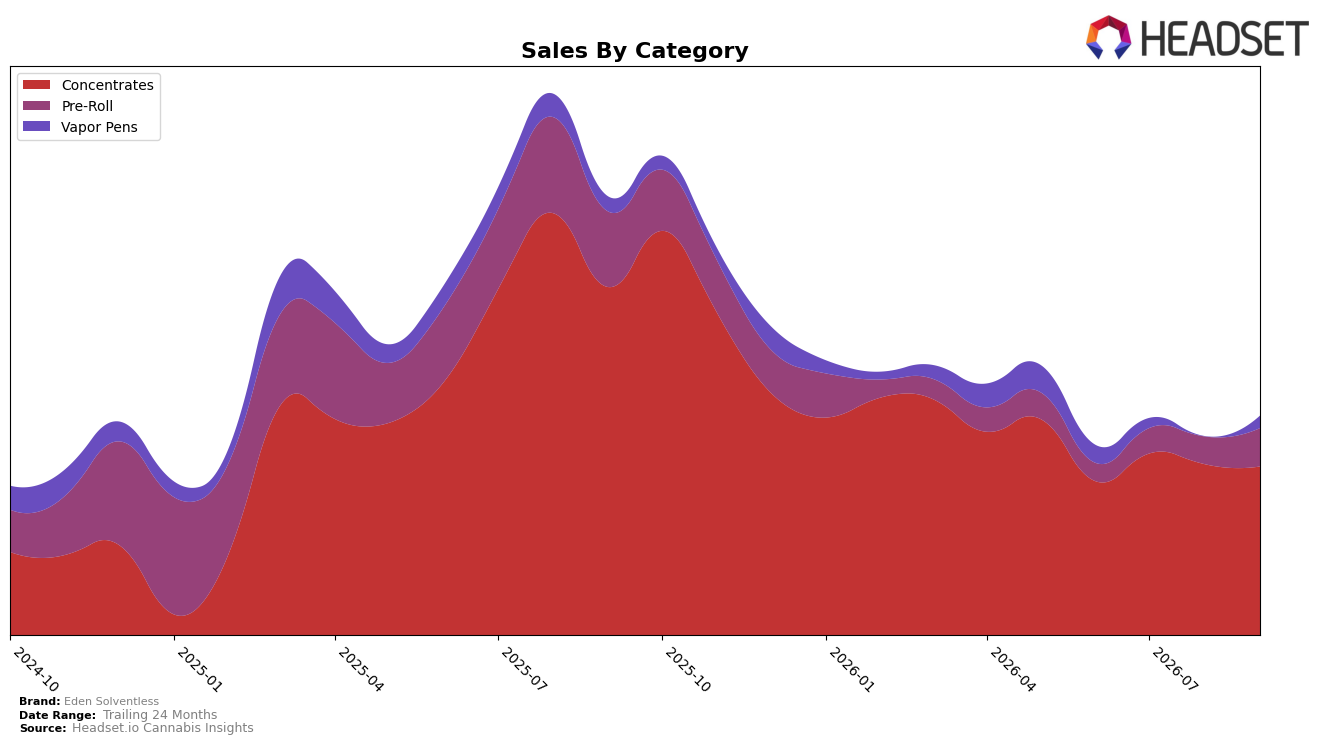
Eden Solventless concentrated its September 2026 revenue in Concentrates at 75.9% share while sitting at rank 12 in Maryland Concentrates, even as that category fell 51.3% year over year and slipped 1.4% month over month. The Pre-Roll slice held 17.8% share with a 48.2% year-over-year decline but a 36.4% month-over-month lift, and Vapor Pens reached 6.3% share with a 15.5% year-over-year decline alongside a 614.9% month-over-month jump. With brand-level sales down 49.4% year over year and average price down 15.7%, the mix signals a pivot away from a contracting core toward faster-moving peripheral formats, implying near-term risk to category depth but opportunity to rebalance volatility across segments.
The mix shift implies Eden Solventless is trading some depth in Concentrates for incremental reach in Pre-Roll and Vapor Pens, where sequential gains of 36.4% and 614.9% indicate elasticity to promotional or distribution changes at a time when average price sits at $33.79. Holding a 75.9% anchor in Concentrates while ranked 12 in Maryland suggests headroom to climb if month-over-month softness reverses, but the year-over-year drag of 51.3% in that core versus a milder 15.5% year-over-year decline in Vapor Pens points to a positioning path that de-emphasizes premium concentrates toward accessible inhalables, aiming to stabilize volume even as overall sales fell 49.4% year over year.
Competitive Landscape
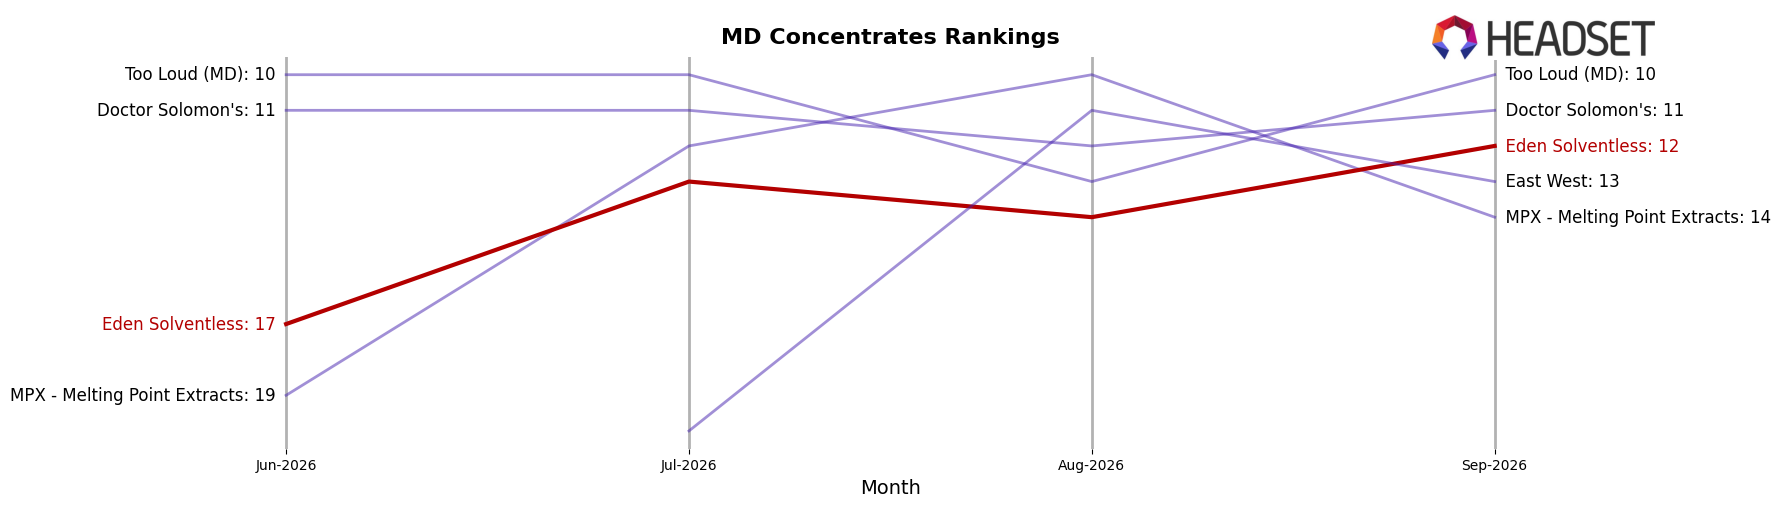
Eden Solventless sits at rank #12 in MD Concentrates in September 2026, down 3 spots year over year from #9 and up 5 spots from June 2026’s #17, while the brand’s historical peak was #7 in October 2025; in contrast, District Cannabis held #1 both this year and last with a 46.4% YoY sales increase, and Grassroots improved from #4 to #2 alongside 41.6% YoY growth, indicating that Eden Solventless is losing relative share at the top even as it recovers quarter-over-quarter. The converging signals—slipping YoY rank from #9 to #12 and mid-pack gains from #17 to #12 over three months, alongside competitors rising into the top 3—imply Eden Solventless must convert recent sequential momentum into sustained share capture or risk settling into a lower-tier position as category leaders widen their gap.
Notable Products
PB&J Hash Infused Pre-Roll (1g) posted the standout move in September 2026 with a +125.98% month-over-month surge to rank 1, while Grape Gushers Hash Infused Pre-Roll (1g) also jumped +102.90% to rank 3. With four of the top ten in Pre-Roll and five in Concentrates, the mix points to a two-pole portfolio where infused Pre-Rolls are accelerating faster than hash and live rosin lines, implying near-term merchandising should emphasize Pre-Rolls to capitalize on velocity while Concentrates sustain base volume.
Creamsicle Moroccan Hash (1g) advanced +65.76% month-over-month to rank 5, contrasting with the Vapor Pens entry Bravado Live Rosin Cartridge (0.5g) at rank 10 with no evident MoM lift and a single-month sell-in of $4,776. The rank clustering from 4 to 7 in Concentrates alongside ranks 1 to 3 in Pre-Roll indicates demand concentration at the category extremes, implying Eden Solventless can lean into infused formats for acquisition while using Concentrates to maintain premium positioning.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

