

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
SunMed is stocked at 104 licensed dispensaries across Maryland and Alaska, 103 of them in Maryland, with the deepest coverage in Baltimore, Silver Spring, Rockville, Annapolis, and Hagerstown. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
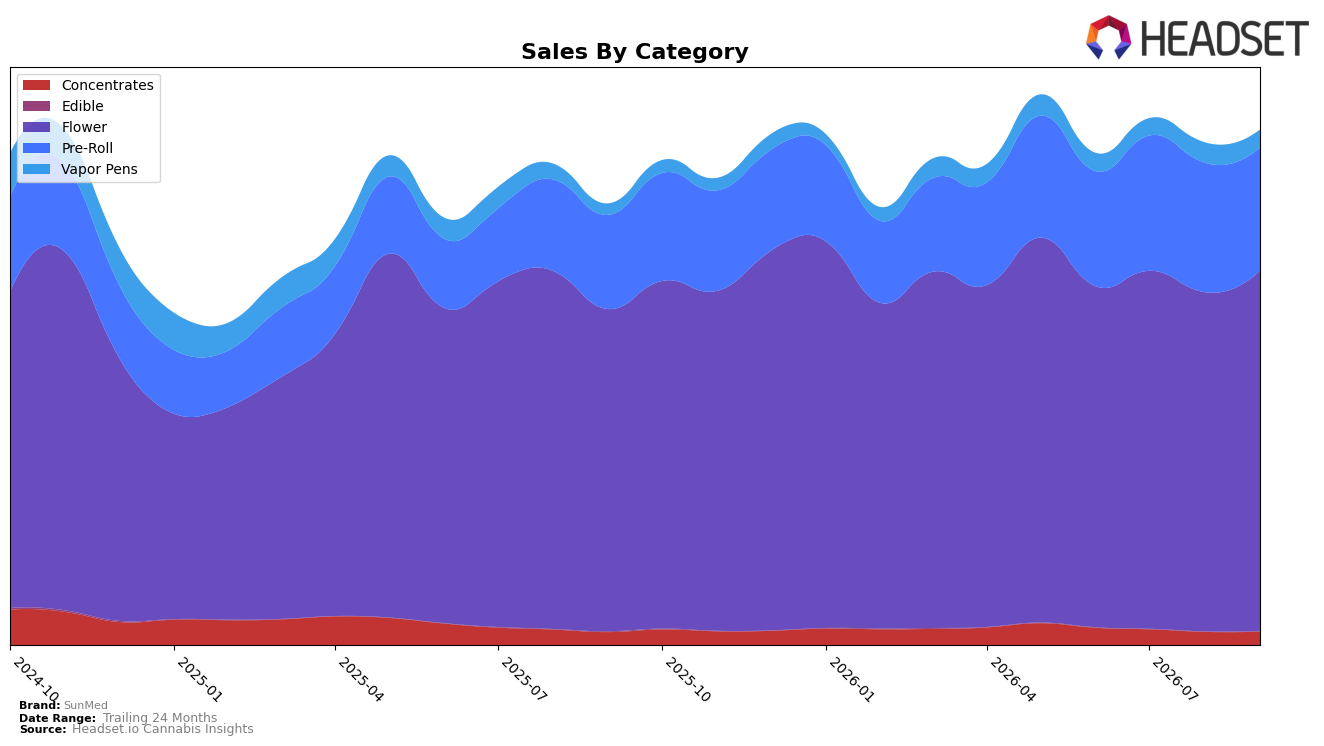
In September 2026, SunMed’s mix leaned heavily into Flower at 69.99% share with year-over-year growth of 11.80% and month-over-month growth of 6.17%, while Pre-Roll held 23.92% share with 30.99% YoY but a 4.79% MoM decline. Vapor Pens remained a small 3.42% share despite a 57.32% YoY increase and a 12.35% MoM pullback, and Concentrates at 2.60% share posted 4.34% YoY and 2.46% MoM growth. Edible was negligible at 0.06% share with a 37.35% YoY drop but a 116.66% MoM jump, and the brand’s average price fell 4.61% YoY alongside total brand sales growth of 16.78% YoY. The pattern implies SunMed is doubling down on Flower to defend a rank of 1 in Flower in Maryland while using tactical price compression to widen unit throughput across core inhalable formats.
The MoM divergence—Flower +6.17% versus Pre-Roll −4.79% and Vapor Pens −12.35%—paired with YoY gains of 11.80%, 30.99%, and 57.32% respectively, indicates near-term execution favors Flower velocity over multi-format expansion, even as annual momentum builds in Pre-Roll and Vapor Pens. Concentrates’ 2.46% MoM with 4.34% YoY suggests a stable niche, while Edible’s 116.66% MoM spike off a 0.06% share and a 37.35% YoY decline signals trial rather than a scalable pillar. With average price down 4.61% YoY and total sales up 16.78% YoY, the positioning implication is price-led share defense anchored in Flower with selective investment in Pre-Roll and Vapor Pens to capture incremental occasions without diluting the core.
Competitive Landscape
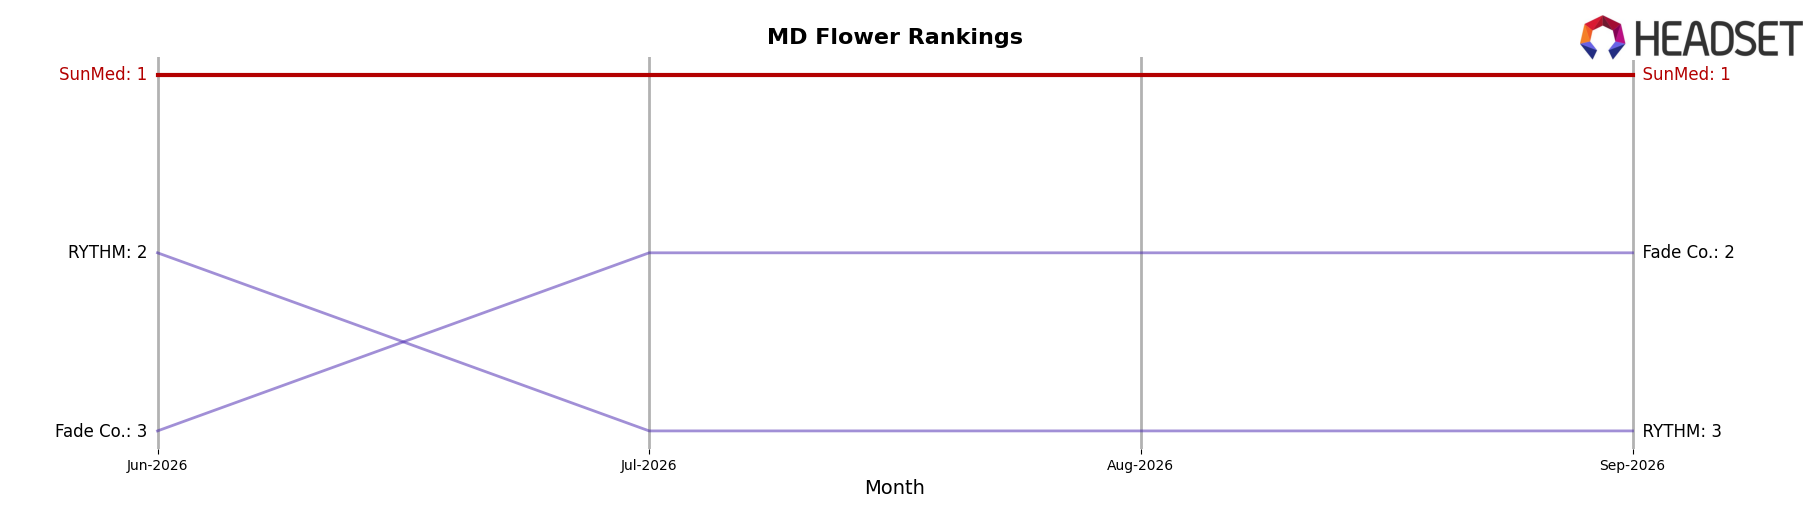
SunMed sits at rank #1 in MD Flower in September 2026 and is flat year over year at #1, while Fade Co. holds #2 after improving from #3 and growing sales by 8.9%, and RYTHM is at #3 after slipping from #4 with a 3.6% sales decline; meanwhile, District Cannabis fell from #2 to #4 with a 29.4% sales drop, contrasted by Strane rising from #10 to #5 on 46.0% sales growth, indicating SunMed’s unchanged #1 rank alongside mixed competitor momentum implies the brand’s leadership is stable but faces emerging pressure from faster climbers directly below.
Notable Products
Golden Pineapple Pre-Roll 2-Pack (1g) posted the steepest decline at -21.3% MoM while falling to rank 3, and Chem De La Chem Pre-Roll 2-Pack (1g) slid -26.9% MoM to rank 8, indicating softness concentrated in flavored pre-rolls even as the category still holds six of the top ten SKUs. In contrast, Sour Diesel (3.5g) rose 12.2% MoM at rank 4 and Sour Diesel Pre-Roll 2-Pack (1g) gained 9.1% MoM at rank 1, signaling that the Sour Diesel strain is pulling share across both Flower and Pre-Roll. Snoop Dogg (3.5g) declined -12.6% MoM at rank 5 while Golden Pineapple (3.5g) dipped -3.4% at rank 9, and the only new entrant Sunshine #4 Pre-Roll 2-Pack (1g) opened at rank 7 with $52,759, implying rotation toward evergreen strains and away from novelty SKUs within pre-rolls. The product mix points to a September 2026 pivot toward strain-led depth around Sour Diesel and a culling of underperforming pre-roll variants, concentrating commercial bets on crossover strains that move in both Flower and Pre-Roll.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

