
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
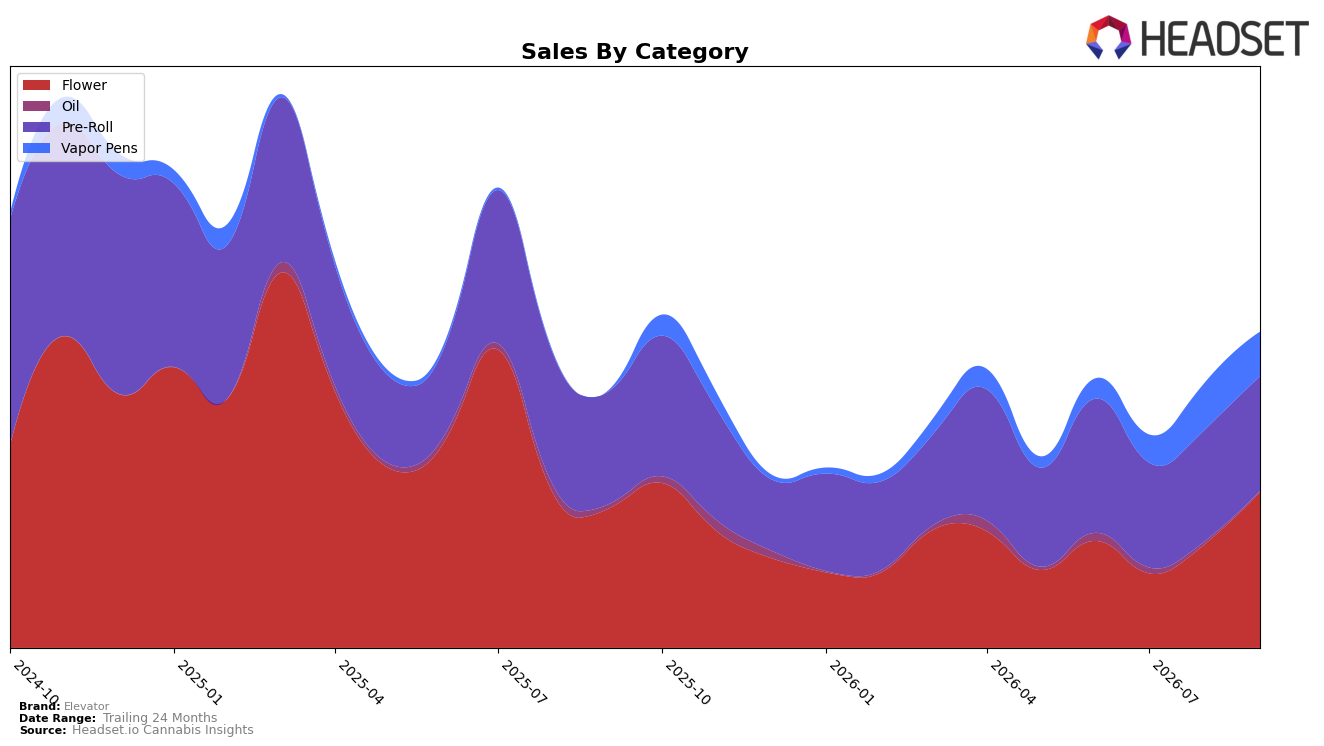
Elevator’s category mix in September 2026 pivoted toward Flower at 49.33% share with 11.95% year-over-year growth and a 50.51% month-over-month surge, while Pre-Roll held 36.40% share with 2.04% year-over-year and 3.06% month-over-month growth. Vapor Pens expanded to 14.01% share on a 4,692.41% year-over-year jump but slipped 5.78% month over month, and Oil compressed to 0.26% share with an 80.28% year-over-year decline and a 68.65% month-over-month drop. With average price up 9.12% year over year and brand sales up 22.95% year over year, the combination of a Flower-led rebound and a newly material Vapor Pens line implies that September 2026 momentum is being driven by higher-priced inhalables offsetting ongoing attrition in Oil.
Positioning-wise, Elevator’s rank of 9 in Flower in Saskatchewan alongside a 50.51% month-over-month Flower lift and a 14.01% share footprint in Vapor Pens indicates a shift toward mainstream inhalables where price tolerance supports mix-driven gains. The 3.06% month-over-month rise in Pre-Roll paired with a 5.78% month-over-month dip in Vapor Pens suggests near-term trade-down risk within inhalables, but the 22.95% brand sales year-over-year increase and 9.12% average price inflation point to elasticity headroom; together, these metrics imply Elevator is consolidating around Flower and selective Vapor Pen offerings to maintain rank while deprecating Oil.
Competitive Landscape
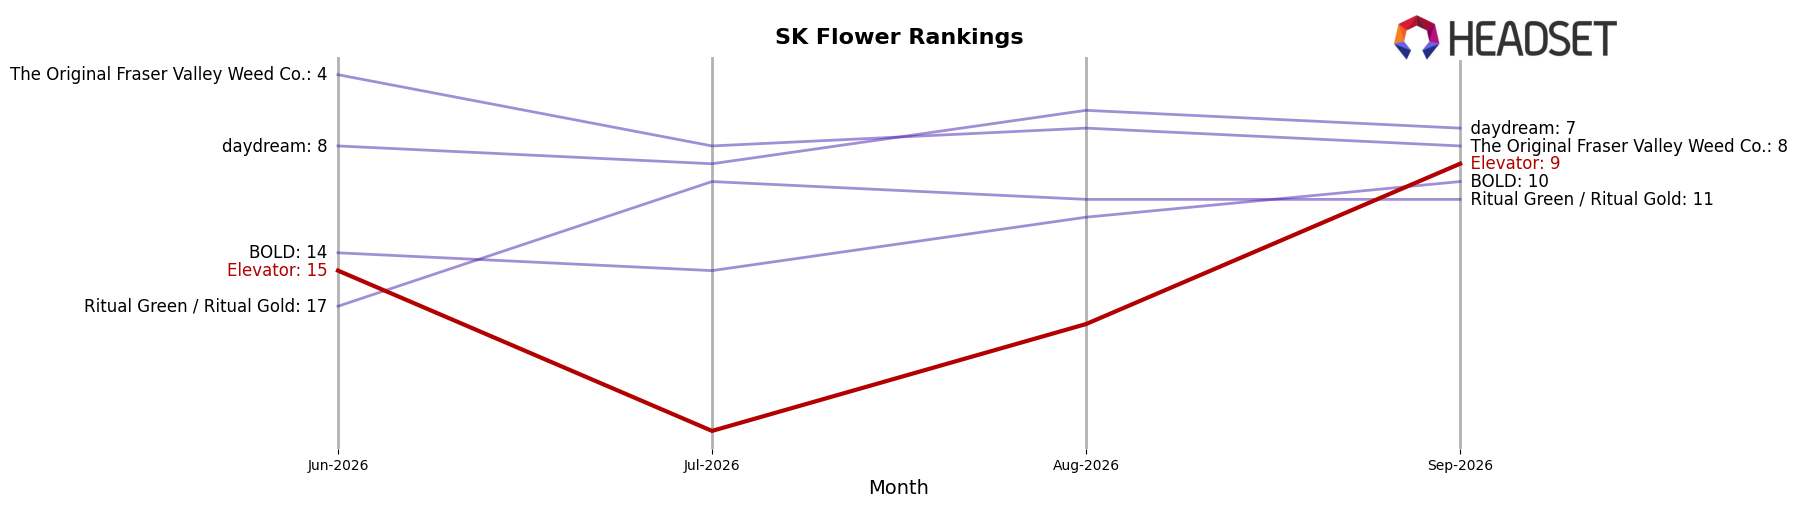
Elevator is #9 in SK Flower in September 2026, unchanged year over year at #9, but up 6 positions from June 2026 when it was #15; this stability follows a prior peak at #1 in November 2024 and contrasts with a market where Back Forty / Back 40 Cannabis held #1 both year over year and currently while growing sales by 22.8%, and Spinach climbed from #5 to #2 alongside a 60.2% sales increase. Meanwhile, Zippy (Canada) surged from #32 to #5 with 364.7% sales growth, outpacing Elevator’s flat YoY rank and compressing headroom at the top; the pattern implies Elevator is stabilizing mid‑tier after a retreat from its November 2024 peak, and absent a share-accretive move it risks being boxed in by faster-rising incumbents and challengers.
Notable Products
Sativa Pre-Roll 5-Pack (2.5g) posted the standout move in September 2026 with +90.5% MoM and a rank at 2, while Grape Kush (3.5g) fell -26.0% MoM to rank 3. Four of the top ten are Pre-Roll SKUs, concentrated across packs from 3 to 7 units, with Hybrid Pre-Roll 7-Pack (3.5g) sliding -14.2% MoM at rank 6 and Ultra Sour Pre-Roll 3-Pack (1.5g) rising +34.2% MoM at rank 9. This pattern implies Elevator is tilting toward multi-pack Pre-Rolls for volume resilience while Flower volatility reallocates share to inhalable convenience formats.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

