

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
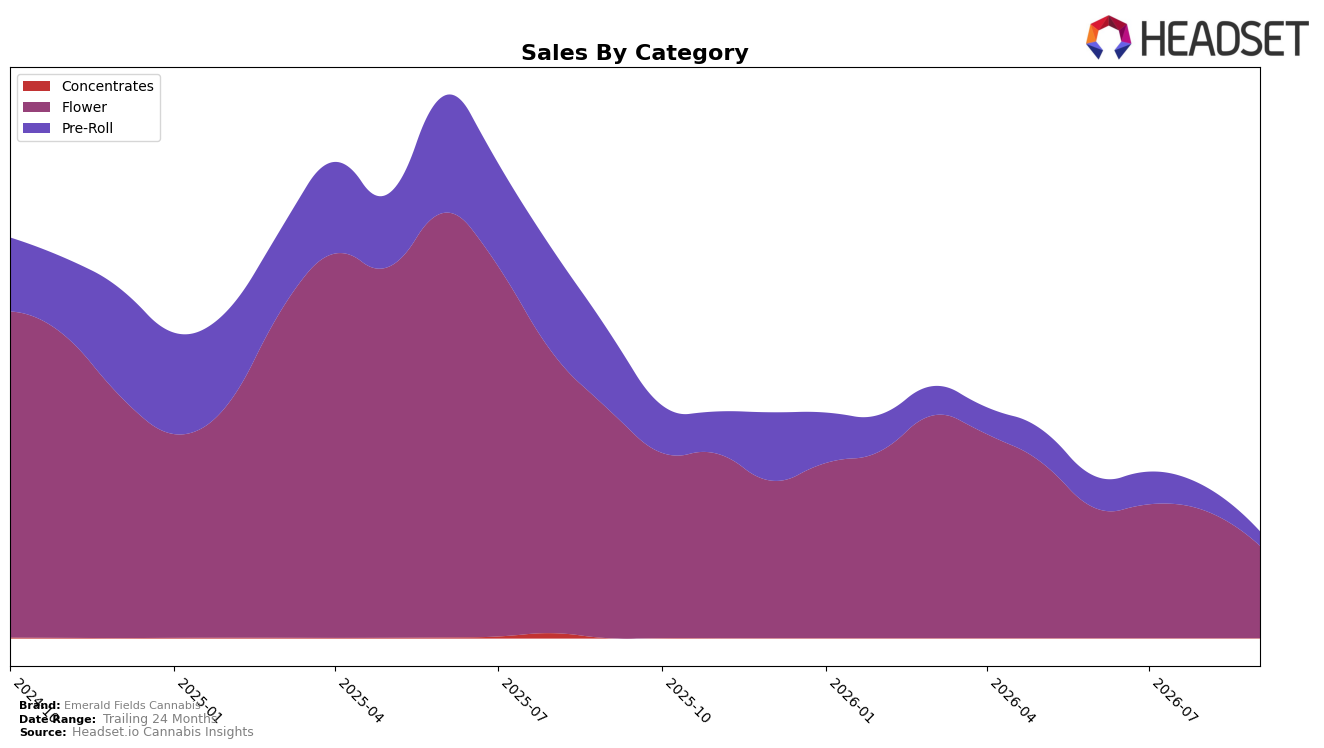
In September 2026, Emerald Fields Cannabis concentrated 86.68% of sales in Flower with a year-over-year decline of 59.76% and a month-over-month drop of 27.70%, while Pre-Roll held 13.32% share with a steeper year-over-year decline of 81.93% and a month-over-month drop of 41.05%. The brand’s average price rose 42.03% year over year to $15.88 even as total brand sales fell 65.42% year over year, implying elasticity pressure concentrated in Flower where average price sits at 20.03 versus 6.77 in Pre-Roll. The pattern indicates a heavier reliance on Flower is coinciding with sharper volume erosion than price can offset, suggesting the current mix is amplifying declines rather than balancing them.
The accelerating month-over-month contraction in Pre-Roll at 41.05% versus 27.70% in Flower, paired with a 70.85% two-year sales decline and a 39th rank in Oregon Flower, points to reduced breadth in value-entry formats where average price is 66% lower than Flower. With Flower at 86.68% share and Pre-Roll prices at 6.77, the widening price gap and category imbalance limit defense against down-trading and penalize rank stability in Oregon; the implication is that without reweighting toward lower-price-per-unit formats or recalibrating Flower price-pack architectures, the brand’s positioning will continue to drift toward a higher-price, lower-share niche with constrained velocity.
Competitive Landscape
Emerald Fields Cannabis sits at rank #39 in OR Flower in September 2026 after a YoY slide of 30 positions from #9, and a 12-rank drop versus June 2026’s #27, while the brand’s historical peak of #2 in June 2025 underscores the scale of retracement. In contrast, Grown Rogue advanced to #1 with a 3-rank YoY climb and 63.8% YoY sales growth, and Oregrown moved to #3 with a 16-rank YoY leap alongside 169.7% YoY sales growth; meanwhile, PRUF Cultivar / PRŪF Cultivar holds #5 despite a 49.3% YoY sales decline. The pattern—falling from #27 three months ago to #39 now while top rivals gained rank—implies Emerald Fields Cannabis is losing share of shelf and consumer rotation to faster-advancing competitors unless assortment, pricing, or distribution strategy is reset.

Notable Products
Critical Plus (28g) posted the steepest movement in September 2026 with a -50.1% month-over-month drop and slid to rank 7, indicating large-format Flower volatility even as other sizes held higher positions. Blue Cookies Pre-Roll 10-Pack (5g) led the lineup at rank 1 while Tropic Thunder Pre-Roll 2-Pack (1.52g) followed at rank 2, and with Pre-Rolls occupying 3 of the top 4 ranks the mix tilted toward multi-pack inhalables over bulk Flower. The concentration of five Flower SKUs in the top ten alongside a Pre-Roll-dominant top tier suggests Emerald Fields Cannabis is shifting demand away from large-ounce Flower toward convenient pack formats, pointing to margin and inventory strategies favoring smaller, faster-rotating units.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

