

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
PRUF Cultivar / PRŪF Cultivar is stocked at 48 licensed dispensaries across Oregon, with the deepest coverage in Portland, Medford, Coos Bay, Corvallis, and Eugene. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
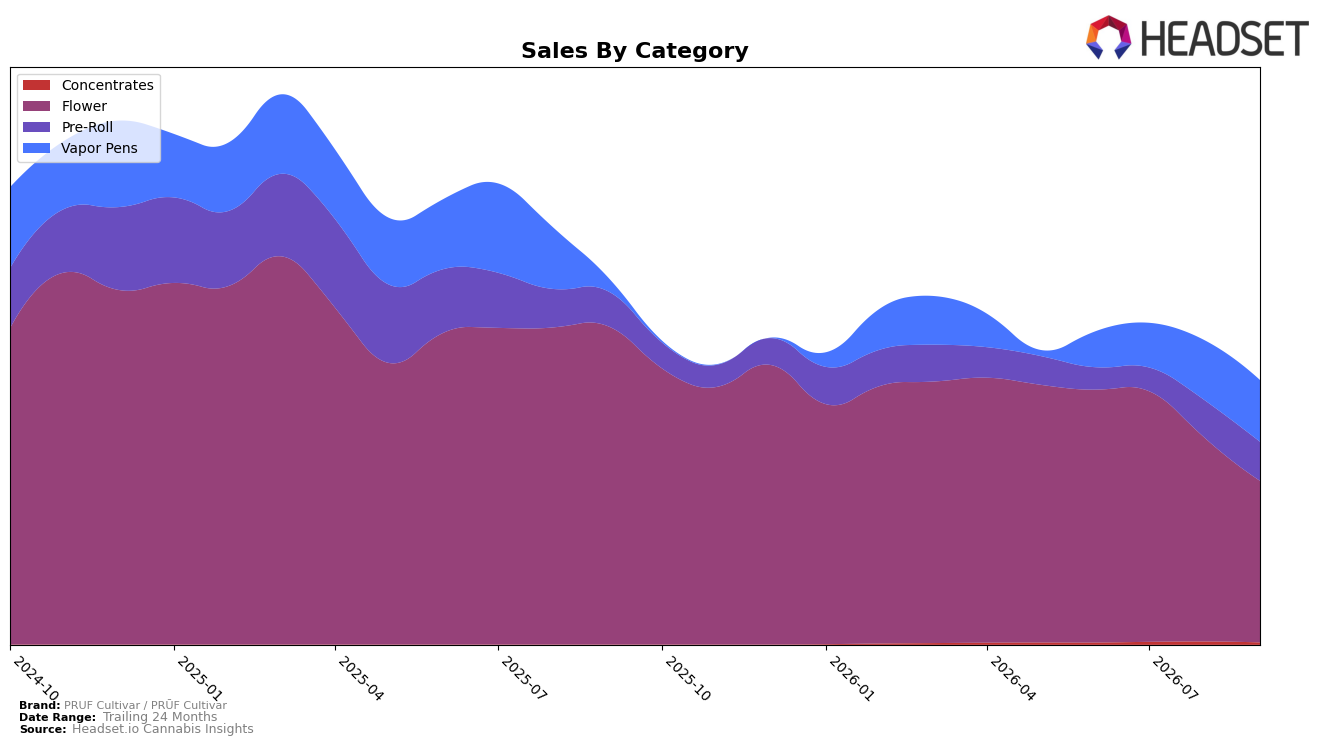
In September 2026, PRUF Cultivar / PRŪF Cultivar’s mix tilted heavily to Flower at 61.2% share while that category fell 49.3% year over year and 20.7% month over month, versus brand-level sales down 28.0% YoY and an average price up 0.6%. Vapor Pens expanded to 23.3% share with 356.2% YoY growth and a 3.0% MoM increase, while Pre-Roll reached 14.7% share with 12.0% YoY growth and 4.0% MoM growth; Concentrates remained marginal at 0.8% share with a 31.0% MoM decline. In Oregon Flower the brand held rank 5 even as Flower contracted, indicating reliance on a shrinking anchor while momentum accrues in Vapor Pens and Pre-Roll; the pattern implies a deliberate reweighting away from a -49.3% YoY Flower drag toward formats posting triple-digit and low-double-digit gains.
The acceleration in Vapor Pens at 356.2% YoY alongside Pre-Roll’s 12.0% YoY growth, paired with only a 3.0% and 4.0% MoM lift respectively, implies the step-change happened earlier in the year and is now stabilizing, while Flower’s 20.7% MoM drop suggests ongoing share erosion at current price points. With average Flower price at 5.36 and brand average price at 6.29, the mix shift toward a 17.29 average price Vapor Pen raises revenue per unit but increases exposure to a category where MoM growth is now modest; holding rank 5 in Oregon Flower amid a 49.3% YoY decline signals brand equity that can be leveraged to migrate users across categories, implying positioning should pivot to defend a reduced Flower base while converting that traffic into higher-priced Vapor Pens and sustaining Pre-Roll’s steady MoM gains.
Competitive Landscape
PRUF Cultivar / PRŪF Cultivar sits at rank #5 in Oregon Flower in September 2026, down 4 positions from its #1 peak in May 2026 and 3 spots below its #2 position from June 2026, while year over year it is 1 rank higher than September 2025. Competitors advanced faster: Grown Rogue climbed to #1 with a 63.8% year-over-year sales increase and moved 3 ranks YoY, and Oregrown rose to #3 with a 169.7% YoY sales gain and a 16-rank jump; in contrast, PRUF Cultivar / PRŪF Cultivar slipped from #2 to #5 across the last three months and now trails Kaprikorn at #4 after its 6-rank YoY improvement. The pattern implies PRUF Cultivar / PRŪF Cultivar is losing relative momentum to faster-ascending rivals and must either recapture its May 2026 peak drivers or concede share to brands compounding multi-rank gains.

Notable Products
Pure Kush (1g) posted the steepest decline in September 2026 at -47.2% MoM while dropping to rank 10, and Hashzilla (1g) fell -40.1% MoM to rank 6, signaling pressure on smaller pack Flower SKUs. In contrast, Too Much Maple (1g) grew 10.1% MoM and held rank 2, while Papaya Sorbet (Bulk) slid -37.6% MoM to rank 3, indicating divergence between single-gram and bulk formats. Eight of the top ten are Flower SKUs, and Jack Herer (Bulk) led at rank 1 with $71,986, implying a portfolio tilted toward Flower with bulk leaders anchoring share even as select 1g items retrench.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

