

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Fig Farms is stocked at 373 licensed dispensaries across California and Illinois, 320 of them in California, with the deepest coverage in Los Angeles, Sacramento, San Francisco, San Diego, and Costa Mesa. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
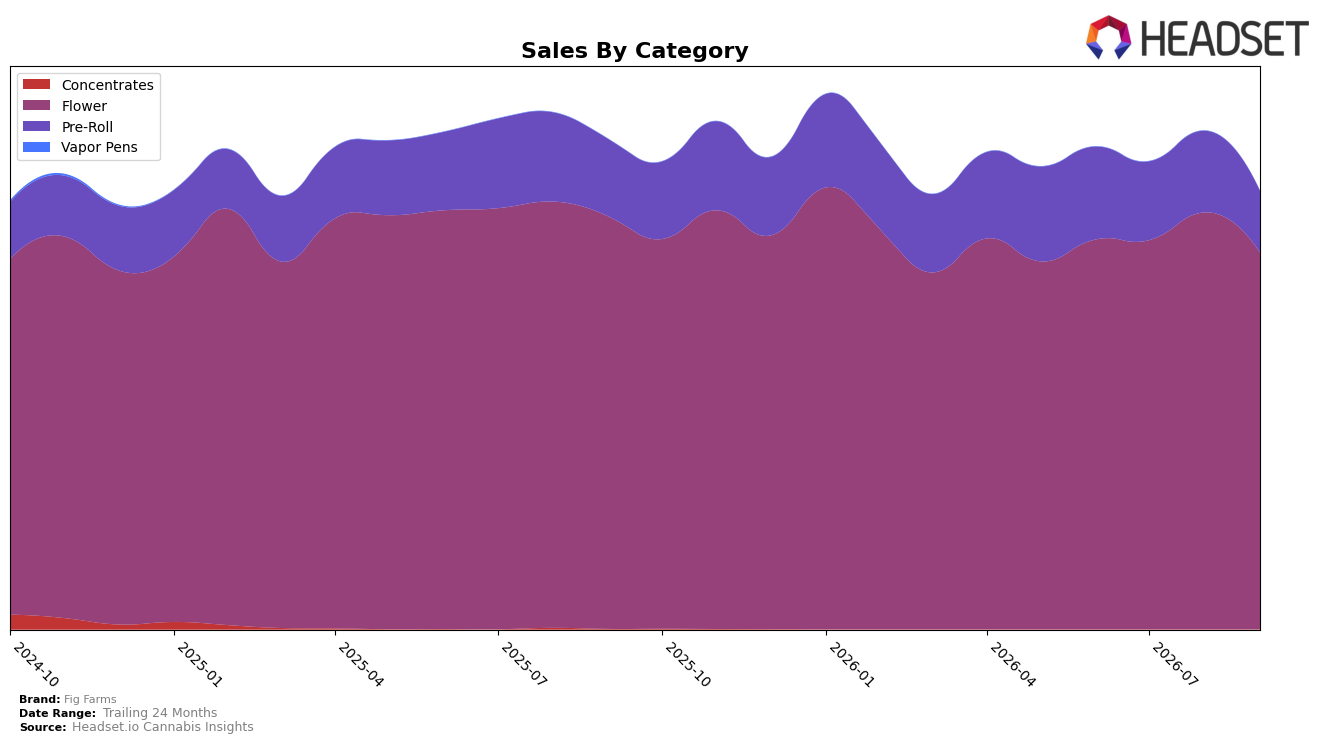
Fig Farms concentrated 85.99% of September 2026 sales in Flower, while Pre-Roll held 14.01%, and both categories contracted at the same time: Flower declined 8.68% year over year and 9.63% month over month, and Pre-Roll fell 20.39% year over year and 24.53% month over month. With average price down 1.06% year over year to $29.36 and Flower’s average price at $34.50, the heavier 85.99% mix in a category posting a 9.63% month-over-month drop compounded the brand’s total sales decline of 10.59% year over year; this pattern implies the current category allocation is amplifying downside during monthly soft patches.
Holding the Flower category at 85.99% share while ranking 10 in Flower in California concentrates exposure to a segment with sharper month-over-month volatility than the 14.01% Pre-Roll contribution, which fell even faster at 24.53% month over month and 20.39% year over year. Given 24-month sales are up 3.14% alongside a current-month Flower mix that skews to higher average pricing ($34.50 vs. the brand’s $29.36 overall), the mix suggests a premium-leaning Flower position that benefits multi-year, but drags month-to-month; this implies Fig Farms’ near-term positioning would reduce variability by moderating Flower from 85.99% toward formats with less severe month-over-month swings while preserving the rank-10 Flower presence in California.
Competitive Landscape
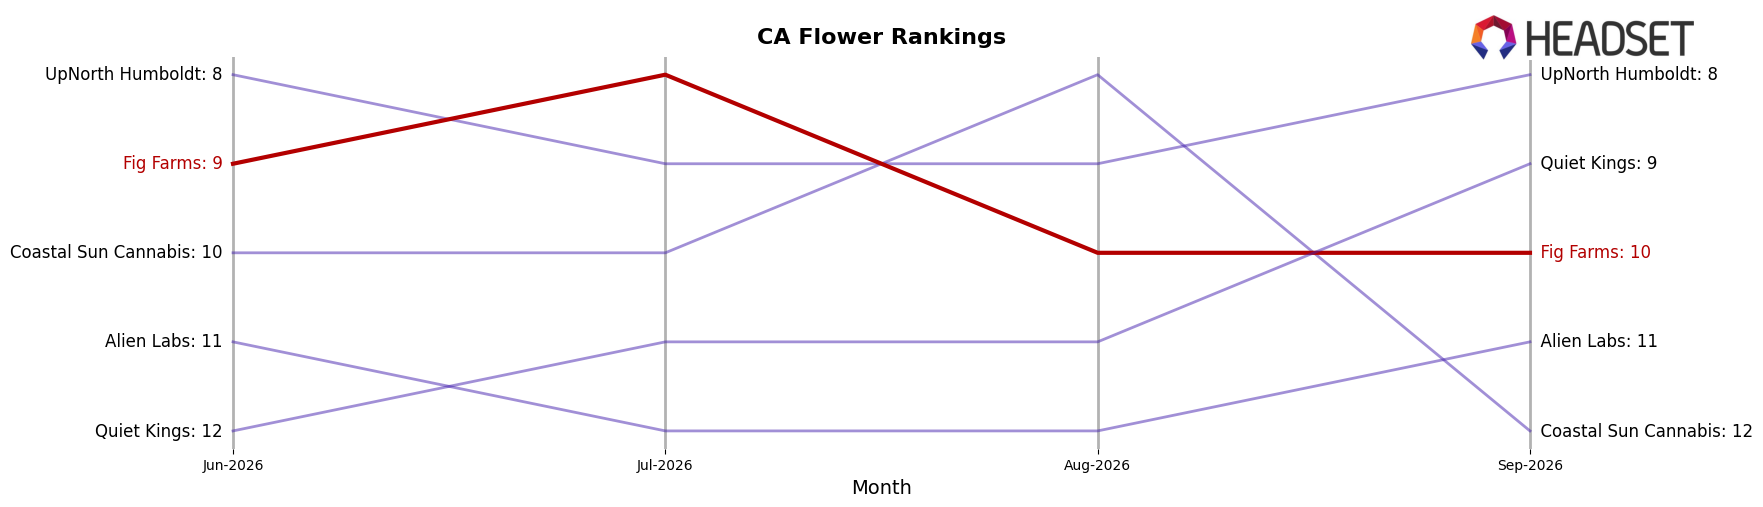
Fig Farms sits at rank #10 in CA Flower in September 2026, down 1 position year over year from #9, and off its July 2026 peak of #8 by 2 spots, while holding flat versus June–August with a 0-position change from #9 to #9 before slipping. Competitors are moving more decisively: STIIIZY advanced from #2 to #1 with 47.8% YoY sales growth, and Oakfruitland climbed from #11 to #5 on 73.5% YoY growth, whereas CannaBiotix (CBX) fell from #1 to #3 amid a 21.1% YoY sales decline. The juxtaposition of a 1-rank YoY slip and a 2-spot retreat from the July 2026 peak, while rivals either surge upward or reset downward, implies Fig Farms is consolidating in the lower top 10 and must outpace double-digit growers to avoid further share erosion.
Notable Products
Blue Face Pre-Roll (1g) led September 2026 with a 66% month-over-month surge to rank 2, while Krypto Chronic #1 (3.5g) fell 36% to rank 3, indicating a sharp reallocation of demand between formats. Blue Face (3.5g) held rank 1 with an 11% MoM gain, and Holy Cow! (3.5g) slipped 16% at rank 4, as five of the top ten are Flower SKUs clustering between ranks 1 and 10. Koala Crack (3.5g) declined 12% at rank 5, while Guavascotti (3.5g) posted a 5% lift at rank 10, pointing to stabilized tail performance amid mid-pack softness. The pattern implies Fig Farms is pivoting toward Pre-Rolls for incremental velocity while legacy Flower leads sustain share but face intra-flower cannibalization risk.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

