

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Oakfruitland is stocked at 212 licensed dispensaries across California, with the deepest coverage in Los Angeles, San Diego, Sacramento, Fresno, and San Bernardino. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
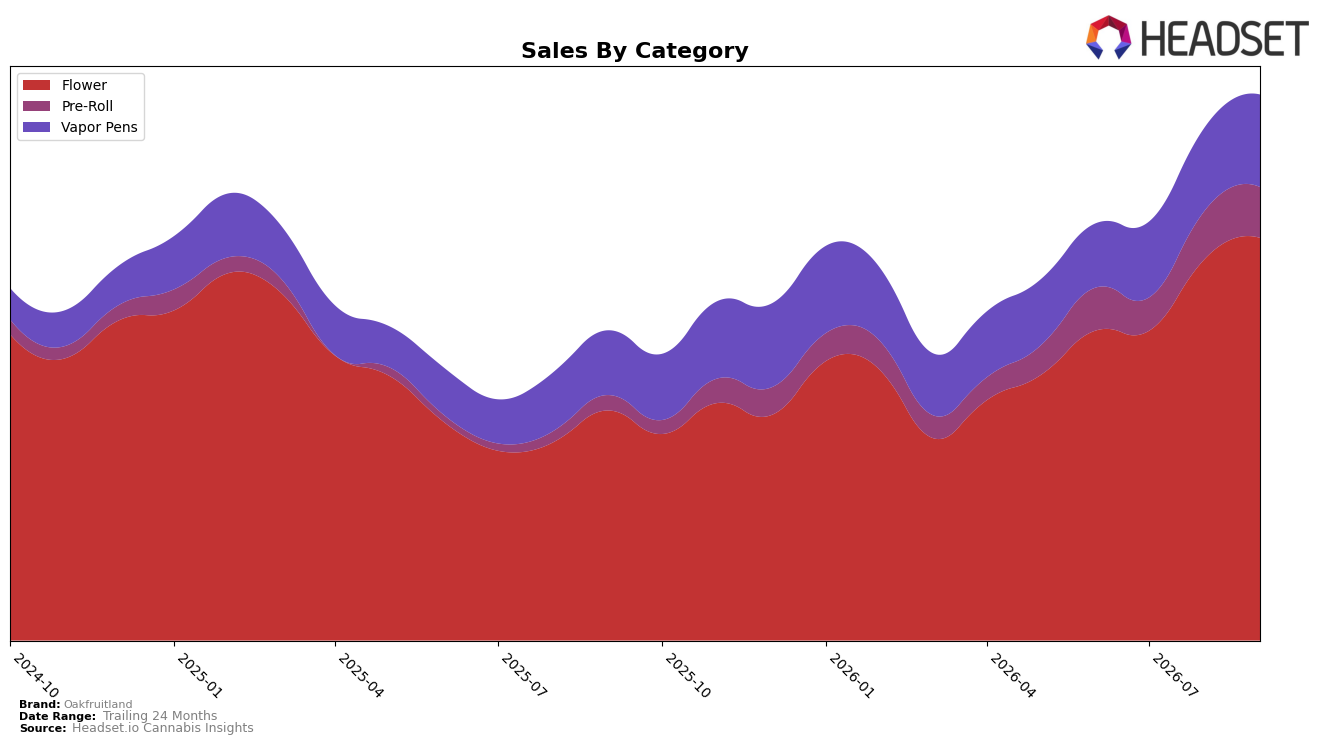
Oakfruitland concentrated 72.69% of September 2026 sales in Flower with year-over-year growth of 73.48% and month-over-month growth of 5.49%, while Vapor Pens held 17.37% share with 39.82% YoY and 10.38% MoM, and Pre-Roll reached 9.94% share on 174.32% YoY and 4.68% MoM. Despite a 5.99% YoY rise in average price portfolio-wide and a category-average Flower price of $36.72, the portfolio tilt still favors higher-ticket Flower, but the faster MoM in Vapor Pens versus Flower implies mix risk if pen momentum sustains; the thesis is that Oakfruitland’s growth headline of 72.57% YoY is currently powered by Flower volume, yet the incremental growth delta is shifting toward Vapor Pens and Pre-Roll.
Holding 72.69% share in Flower while ranking 5 in California Flower positions Oakfruitland as a Flower-led brand, but the 10.38% MoM in Vapor Pens and 174.32% YoY in Pre-Roll suggest a hedging move into faster-turn, lower-price formats that can broaden access and reduce reliance on premium pricing. The implication is that maintaining a top-5 Flower rank in California while allowing Vapor Pens to take a greater share from 17.37% could re-balance revenue toward categories with higher sequential velocity, improving resilience against Flower price elasticity even as the average price rose 5.99% YoY.
Competitive Landscape
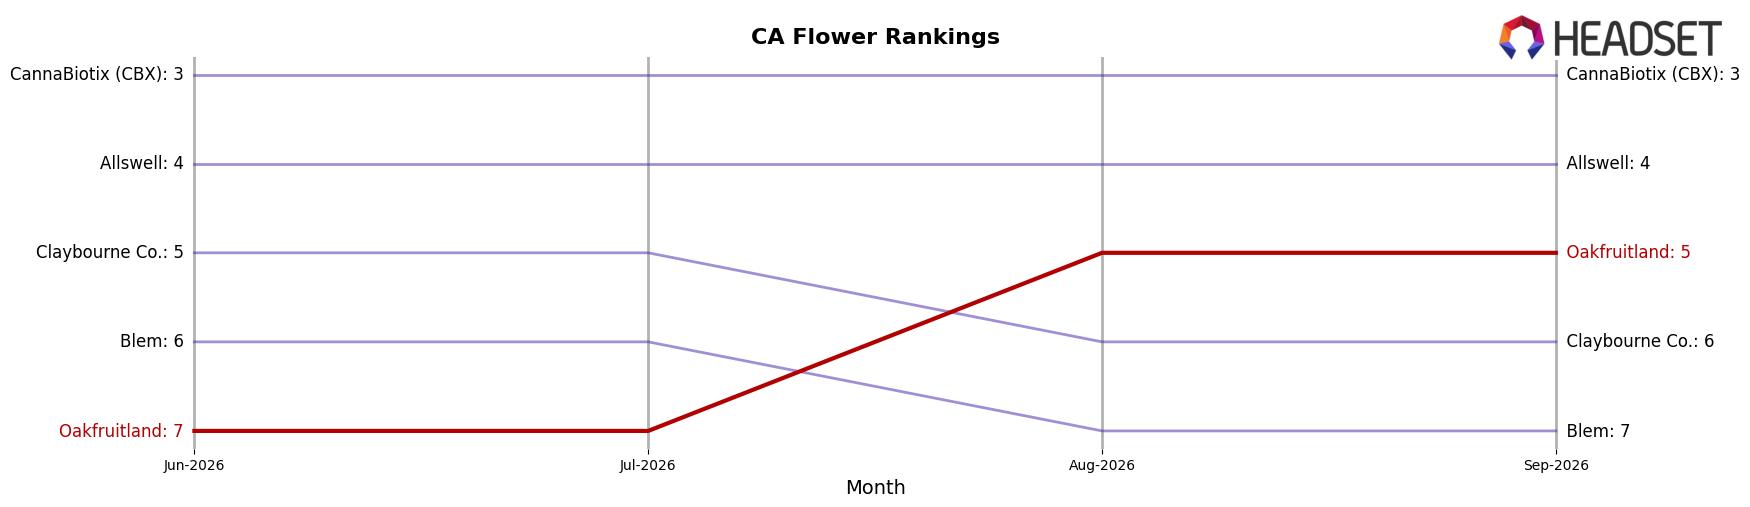
Oakfruitland sits at rank #5 in California Flower in September 2026, improving 6 positions from #11 year over year, and tightening further versus June 2026 when it was #7; this trajectory moved it within two spots of its peak at #3 from March 2025 while still trailing STIIIZY which rose from #2 to #1 and CAM which climbed from #3 to #2, and it outpaced CannaBiotix (CBX) that declined from #1 to #3; against Allswell holding steady at #4 year over year, Oakfruitland’s two-rank improvement versus three months ago and six-rank YoY gain indicate share is consolidating among the top five and that its upward rank momentum is durable but will require displacing a static #4 or a rising #2 to re-enter the top three.
Notable Products
Pandora's Box (3.5g) delivered the standout move in September 2026 with a 42.97% month-over-month gain into rank 2, while Pandora's Box (7g) held rank 1 with a smaller 5.94% increase, indicating depth across sizes rather than a single-SKU spike. Pre-Roll momentum cooled as Oak Lato Pre-Roll 2-Pack (2g) slipped 7.78% to rank 3 and Pandoras Box Pre-Roll 2-Pack (2g) fell 5.12% at rank 6, whereas Cereal Milk (7g) advanced 15.47% at rank 9; the contrast points to demand consolidating in Flower even as ready-to-smoke formats pause. With five of the top ten SKUs in Flower and only one explicit dollar figure at $421,115 for Pandora's Box (7g), the mix implies Oakfruitland is tilting assortment and consumer pull toward multi-size Flower franchises that can ladder shoppers up in size and price.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

