

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeWhere to Buy
Glacier Cannabis is stocked at 178 licensed dispensaries across Michigan, with the deepest coverage in Detroit, New Buffalo, Ann Arbor, Coldwater, and Grand Rapids. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
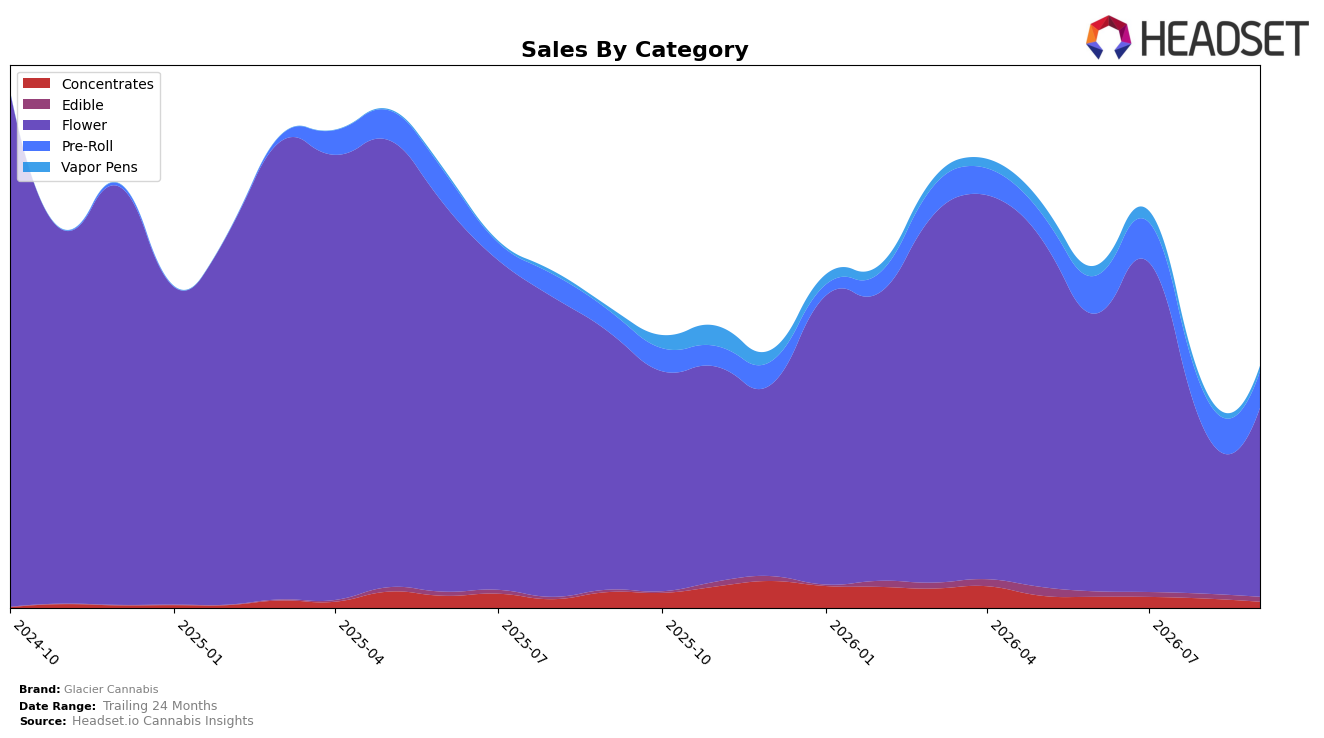
In September 2026, Glacier Cannabis leaned even harder into Flower, with the category holding 78.58% share as Flower sales rose 15.91% month over month but declined 26.84% year over year; meanwhile, Pre-Roll expanded to 14.97% share on 0.52% MoM growth and a 69.66% YoY increase. Smaller lines were mixed: Edible held 1.87% share with 3.11% MoM and 136.60% YoY growth, while Vapor Pens at 2.17% share fell 13.84% MoM despite 65.91% YoY growth, and Concentrates shrank to 2.42% share with a 35.81% MoM drop and a 62.58% YoY decline. With brand sales down 19.86% YoY and average price down 25.81% YoY to $11.69, the pattern implies a volume-seeking pivot anchored in Flower and value-oriented formats, using Edible and Pre-Roll growth to offset Concentrates erosion.
The mix shift implies Glacier Cannabis is prioritizing basket traffic and entry pricing over premium margin, as evidenced by Flower’s 78.58% share alongside a 26.84% YoY Flower decline and concurrent 69.66% YoY rise in Pre-Roll. The brand’s position in Michigan Flower at rank 41, paired with a 13.84% MoM contraction in Vapor Pens and a 35.81% MoM pullback in Concentrates, suggests a deliberate narrowing toward high-velocity value lanes while ceding higher-ticket niches; this trade-off likely stabilizes near-term volume but risks ceiling on price recovery and limits differentiation versus premium cartridges and extracts.
Competitive Landscape
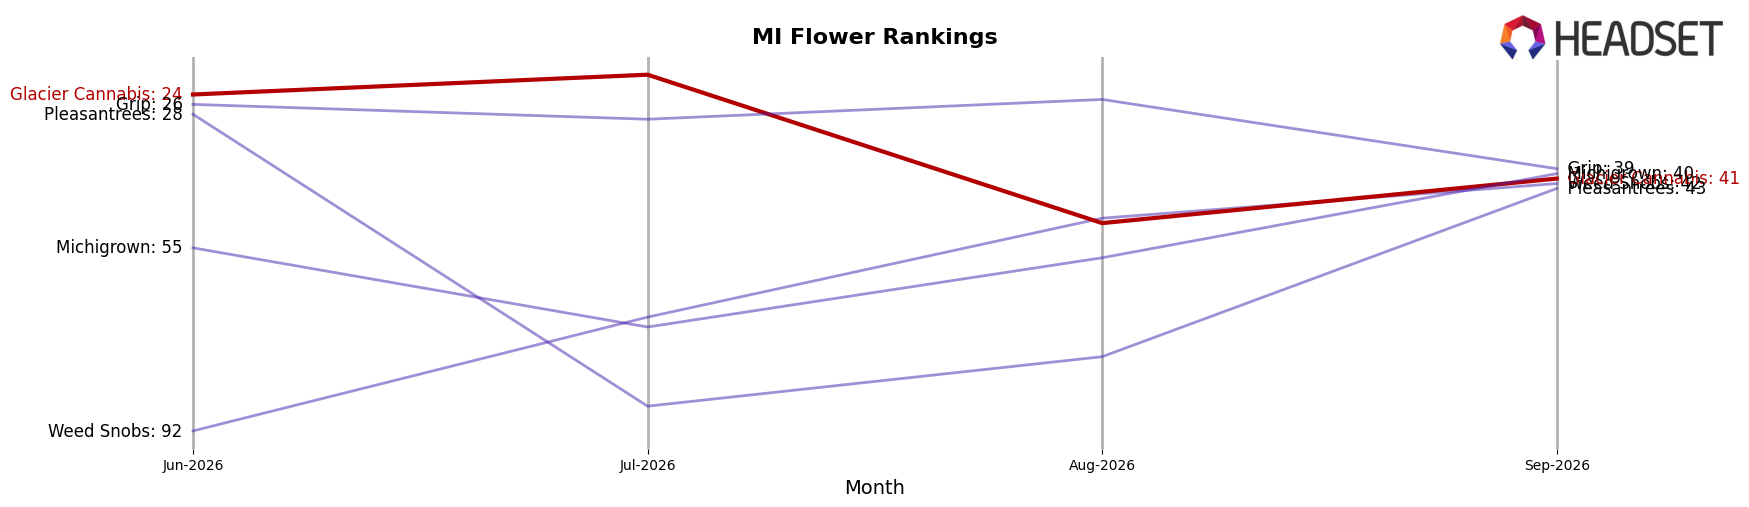
Glacier Cannabis sits at rank 41 in September 2026 in MI Flower, down 10 positions year over year from rank 31 and sliding 17 spots since June 2026 when it was rank 24; this contrasts with High Minded holding rank 1 both year over year and currently while posting a 3.3% decline in sales YoY, and Play Cannabis rising from rank 7 year over year to rank 2 alongside a 33.3% sales YoY increase. Despite a historical peak at rank 11 in October 2024, Glacier Cannabis’s present positioning behind Pro Gro at rank 3 after a 6-place YoY climb and behind NOBO at rank 4 after a 19-place YoY leap with 188.3% sales growth indicates that the brand’s downward rank trajectory signals share ceding to faster-climbing peers in 2026.
Notable Products
Black Ice Pre-Roll (1g) delivered the standout movement in September 2026 with a +58.7% month-over-month gain to reach rank 2, while Blueberry Muffin Pre-Roll (1g) slipped -11.2% at rank 8, and Freezer Jam Pre-Roll (1g) fell -25.5% also sitting at rank 8 in a tie. Pre-Rolls occupy six of the top ten positions, concentrating velocity in a single format even as Flower anchors rank 1 with Berry Junky (Bulk) and places two more SKUs in the top five. The mix implies Glacier Cannabis is tilting toward Pre-Roll-led trial and basket adds while relying on a few Flower leaders for baseline volume, signaling a portfolio that uses rapid Pre-Roll rotations to capture incremental share without ceding premium shelf ranks in Flower.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

