


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeWhere to Buy
gLeaf (Green Leaf Medical) is stocked at 26 licensed dispensaries across Maryland, Virginia, and 3 other states, 12 of them in Maryland, with the deepest coverage in Baltimore, Bethesda, Elkton, Germantown, and Hagerstown. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
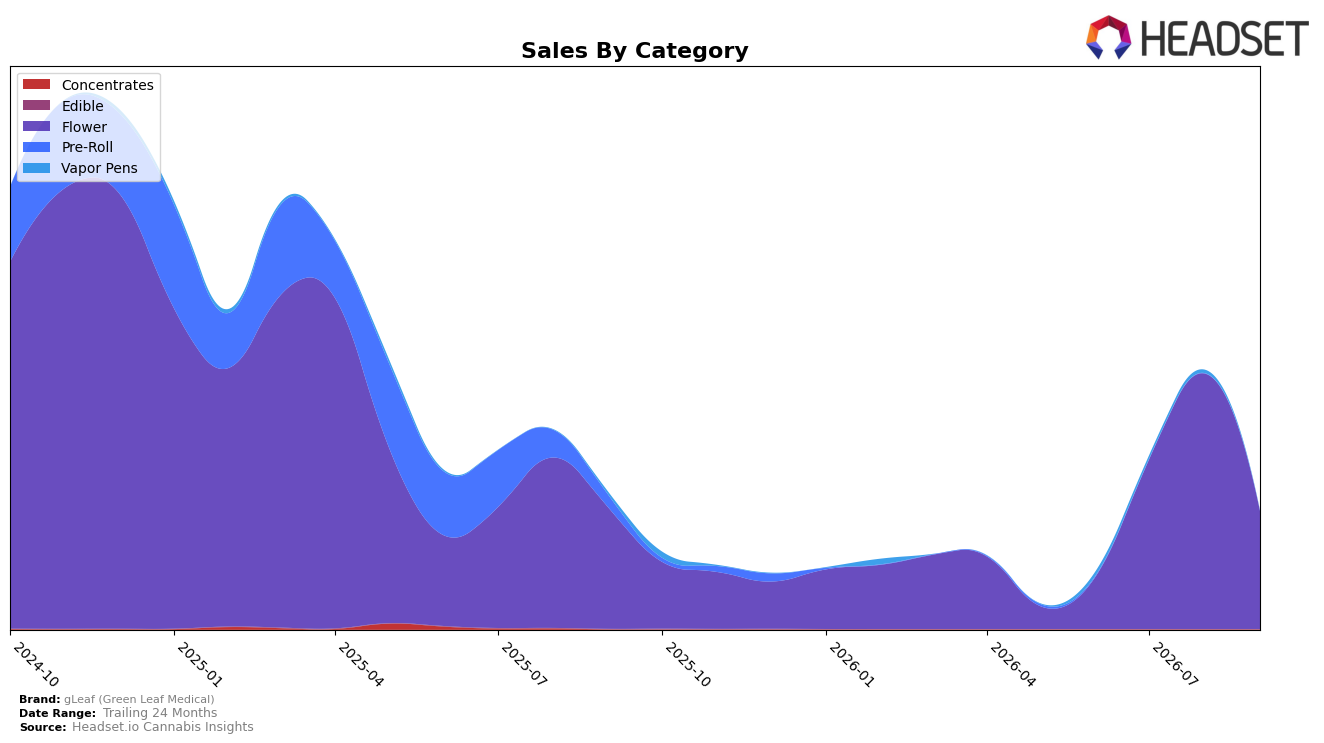
In September 2026, gLeaf (Green Leaf Medical) concentrated 100.0% of sales in Flower, with Flower down 2.82% year over year and down 53.89% month over month, while total brand sales declined 13.51% year over year. Average price rose 204.84% year over year to $86.21 alongside a 66.96% decline over 24 months in total sales, indicating a sharp mix shift toward higher-priced Flower and away from volume-driven SKUs. The pattern implies that a single-category footprint amplified volatility, as the MoM drop of 53.89% and a state-category rank of 38 signal that pricing strategy and assortment breadth are constraining near-term demand.
With Flower as the sole contributor, a 100.0% mix paired with a 204.84% price increase and a 53.89% MoM volume contraction suggests elastic demand is eroding unit throughput despite premium positioning in Maryland. The 38 rank within Maryland Flower, combined with a 13.51% YoY brand sales decline and a 66.96% 24‑month slide, indicates the current price-to-value equation is misaligned for repeat purchasing. The thesis is that sustaining a single-category, high-price stance raises rank risk and seasonality exposure, so rebalancing entry-price Flower or reintroducing adjacent formats would likely stabilize share and improve rank resilience.
Competitive Landscape
gLeaf (Green Leaf Medical) holds rank #38 in MD Flower in September 2026, a 1-position improvement from #39 year over year, and a 12-position climb from #50 in June 2026, while still tracking below its peak at #22 from December 2024; meanwhile, SunMed remained steady at #1 year over year and Fade Co. advanced from #3 to #2 as District Cannabis moved down from #2 to #4 with a -29.36% YoY sales change. Against this leaderboard shift, RYTHM edged from #4 to #3 with a -3.59% YoY sales change, and Strane surged from #10 to #5 with +45.97% YoY sales, indicating that gLeaf’s modest rank gain is tied more to mid-tier churn than to top-tier displacement; the trajectory implies stabilization off a mid-2026 trough with headroom to recapture share only if it converts recent 3-month momentum into sustained placement gains.

Notable Products
Permanent Marker (28g) posted the steepest decline in September 2026 at -58.4% MoM, slipping to rank 3, while Honey Banana (28g) fell -47.4% MoM to rank 5. Falcon 9 Smalls (28g) led the lineup at rank 1 and Falcon 9 (28g) held rank 6, and eight of the top ten are Flower SKUs, concentrating revenue in a single category. Sherbanger (28g) reached rank 2 as the mid-tier shifted, and the spread from rank 1 to rank 6 Flower formats indicates reliance on large-format buds over smaller sizes despite a -58.4% shock in one headliner. The pattern implies gLeaf (Green Leaf Medical) is leaning into Flower variety with emphasis on 28g formats, but portfolio risk is elevated if a few flagship strains swing by over -50% MoM.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

