

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Old Pal is stocked at 560 licensed dispensaries across New York, Massachusetts, and 16 other states, 101 of them in New York, with the deepest coverage in New York, Queens, Brooklyn, The Bronx, and Albany. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
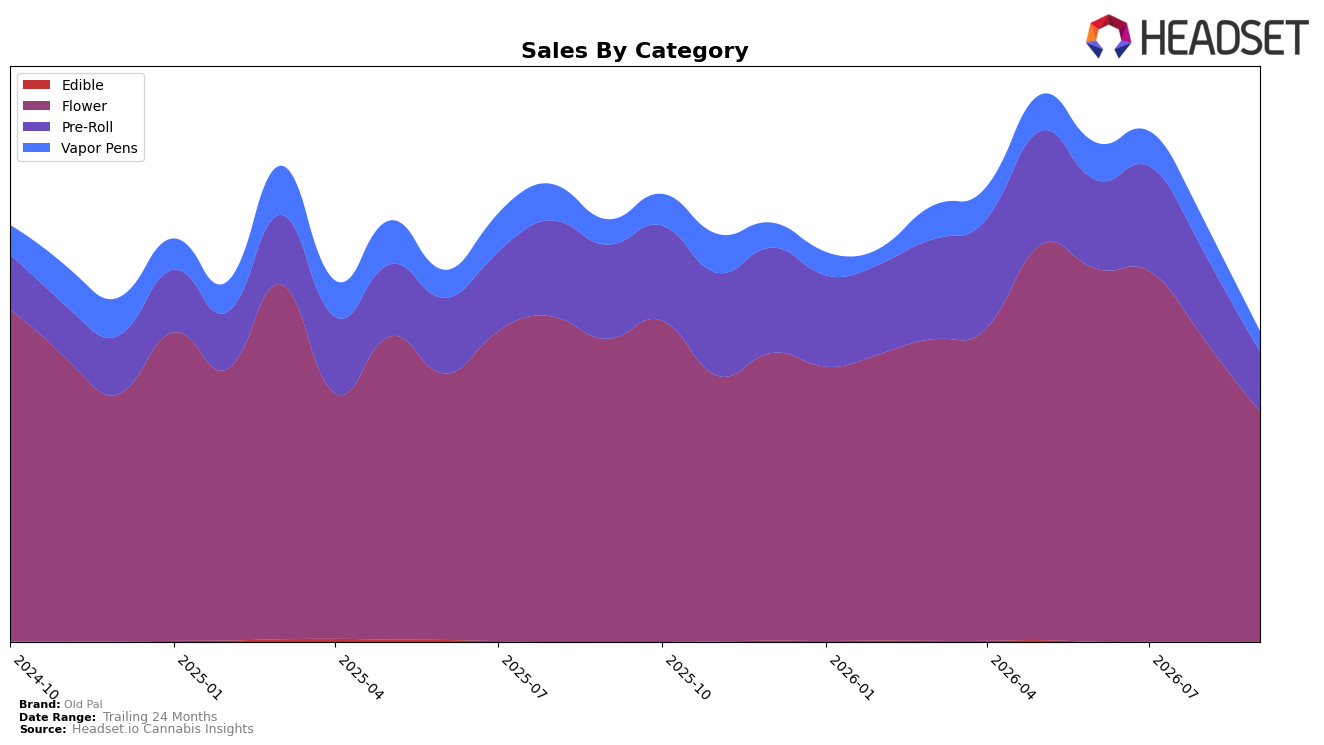
Old Pal concentrated 74.14% of September 2026 sales in Flower, with Pre-Roll at 19.28% and Vapor Pens at 6.53%, while Edible was a negligible 0.05% of mix. Within the month, Flower declined 23.70% MoM and 23.76% YoY, Pre-Roll slid 30.92% MoM and 36.26% YoY, and Vapor Pens fell 35.16% MoM and 19.25% YoY, with Edible contracting 34.80% MoM and 85.81% YoY. Average price rose 6.45% YoY to $28.06 even as brand sales fell 26.44% YoY and 15.83% over 24 months, and Old Pal held rank 15 in Flower in Massachusetts. The pattern implies outsized exposure to Flower concentration amplified volume sensitivity, and price increases did not offset unit losses across all categories.
The shift toward a heavier Flower mix amid double‑digit MoM and YoY declines in every category implies reliance on a price‑sensitive core that is ceding units faster than the brand is defending with pricing, particularly as Pre-Roll’s 36.26% YoY drop compounds a 30.92% MoM setback. With Vapor Pens contracting 35.16% MoM while holding only 6.53% share, category diversification is not currently absorbing volatility, and Edible’s 85.81% YoY collapse to 0.05% share removes a potential entry-price ladder. For positioning, this mix and the rank 15 standing in Massachusetts Flower suggest the brand must either deepen differentiation within Flower where 74.14% of sales reside or rebalance toward Pre-Roll and Vapor Pens to stabilize seasonality and promo-driven swings.
Competitive Landscape
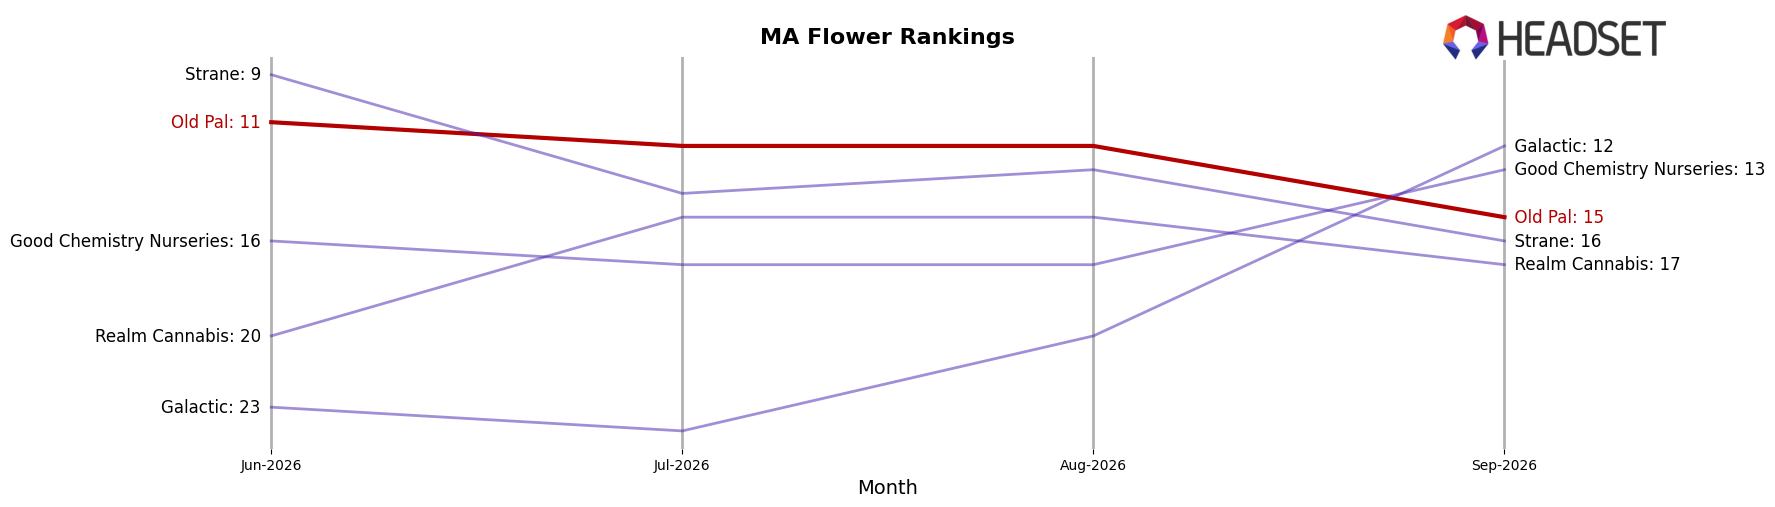
Old Pal is ranked #15 in Massachusetts Flower in September 2026, improving 21 spots from #36 year over year, but slipping 4 positions from #11 in June 2026 to #15 in September 2026. In contrast, Perpetual Harvest moved from #4 to #1 with 124.1% year-over-year sales growth, while Simply Herb slid from #1 to #3 alongside a 16.6% sales decline; this places Old Pal’s YoY climb against a market where leaders are either accelerating or contracting. The combination of a 21-rank YoY rise and a 4-rank quarter-over-quarter dip implies Old Pal converted long-cycle distribution or pricing gains but lost recent momentum to faster-moving leaders, signaling a need to shore up near-term velocity to sustain its higher tier.
Notable Products
Purple Octane Pre-Roll 2-Pack (1g) posted the steepest decline at -71.3% month over month while falling to rank 2, and Lemon Berry Burst Pre-Roll 2-Pack (1g) also contracted by -51.6% yet held rank 1; this divergence implies price-sensitive volume in Pre-Rolls where leadership is maintained by breadth rather than momentum. Durban Skunk Shake (14g) slid -21.7% MoM at rank 3, and four of the top ten are Flower SKUs concentrated between ranks 3 and 10, pointing to category ballast offsetting volatility in Pre-Rolls even as Vapor Pens appear at rank 9 with a single entry anchoring mix diversity. Despite a $37,223 anchor from Lemon Cyclone RTR (14g) at rank 7 and stable Flower presence across ranks 3, 4, 5, 6, and 10, the double-digit Pre-Roll retrenchment signals a pivot toward higher-weight Flower for dependable throughput. Net effect: Old Pal’s September 2026 product mix tilts commercial focus toward Flower-led stability while Pre-Rolls require repositioning to recover MoM velocity.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

