

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Heavy Hitters is stocked at 807 licensed dispensaries across California, New York, and 2 other states, 506 of them in California, with the deepest coverage in Los Angeles, Sacramento, San Diego, San Francisco, and San Jose. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
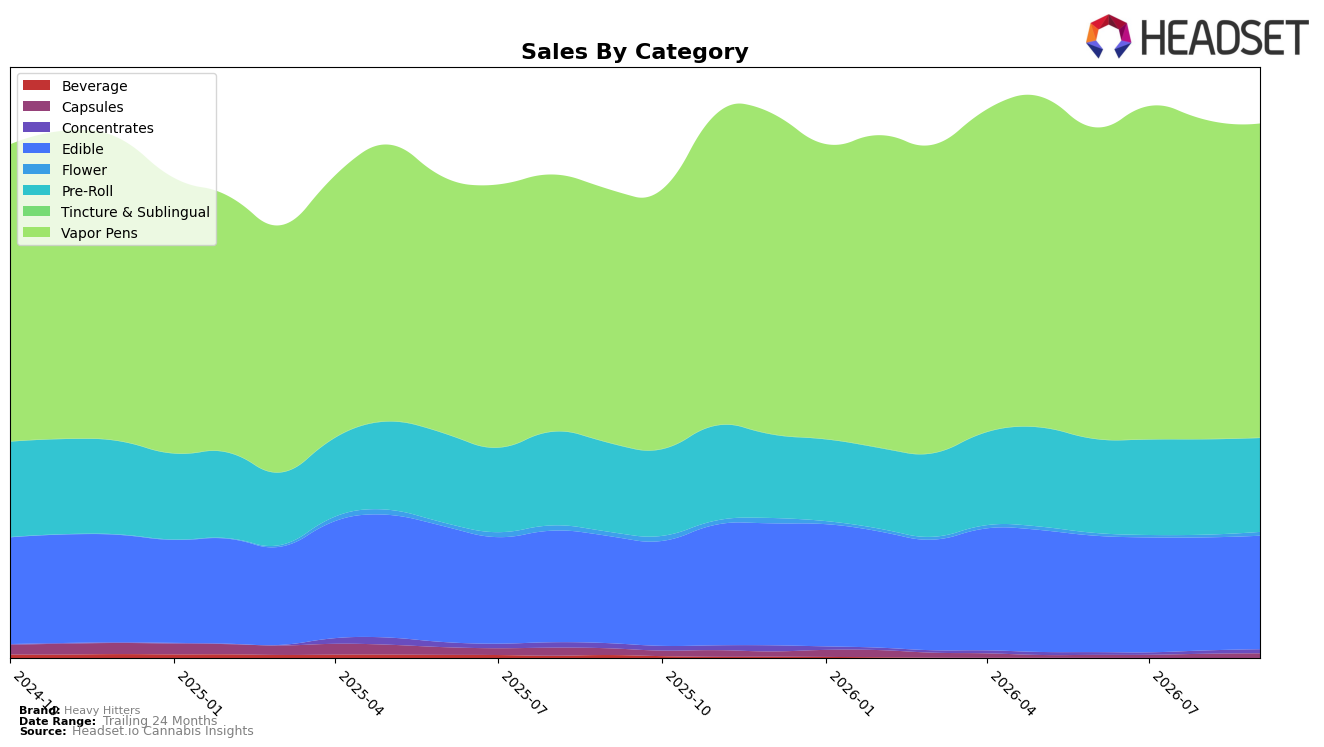
In September 2026, Heavy Hitters leaned further into Vapor Pens at 58.95% share with 24.03% YoY growth but a -1.68% MoM dip, while Edible held 21.26% share with 5.92% YoY and 0.40% MoM gains; together, these two accounted for 80.21% of mix, implying concentration risk if Vapor Pens softness extends. Pre-Roll at 17.58% share grew 5.57% YoY but slid -1.52% MoM, whereas smaller lines swung sharply: Concentrates fell -21.68% YoY but jumped 26.17% MoM, and Flower declined -11.22% YoY yet surged 46.04% MoM; this contrast with Tincture & Sublingual’s 48.90% YoY and 203.00% MoM spikes suggests tactical trials rather than durable scale, implying the brand is testing into niches to buffer a slight month-over-month cooling in its core.
With a 7 rank in Vapor Pens in California alongside a 3.02% YoY average price lift to $32.77 and brand-level 14.05% YoY sales growth, the path forward hinges on turning Pre-Roll’s 17.58% mix into a second engine to reduce reliance on a category with a -1.68% MoM dip. The combination of Concentrates’ 26.17% MoM and Flower’s 46.04% MoM rebounds against negligible shares (0.71% and 0.66%) contrasts with Beverage’s -97.99% YoY collapse and 127.76% MoM bounce at 0.01% share, implying that micro-categories are currently volatility absorbers rather than growth drivers, and that positioning should prioritize depth in two categories while keeping small-format experiments tightly scoped.
Competitive Landscape
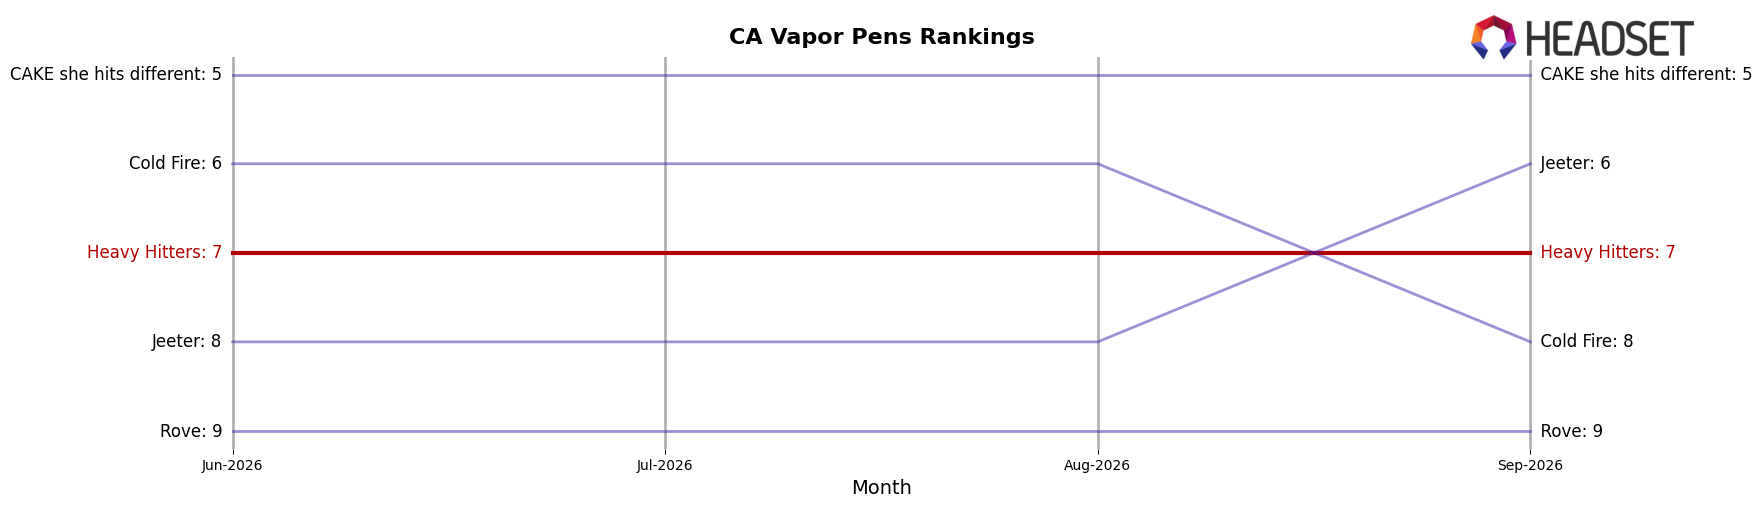
Heavy Hitters sits at rank #7 in California Vapor Pens in September 2026, improving 1 position from #8 year over year while holding flat versus three months ago at #7, and this stability contrasts with Jetty Extracts climbing from #4 to #3 on 45.2% YoY sales growth and Plug Play slipping from #3 to #4 on a 13.5% YoY decline; meanwhile, STIIIZY remains #1 despite a 16.7% YoY sales contraction and Raw Garden stays #2 with a 0.6% YoY uptick, indicating Heavy Hitters’ modest rank gain and plateau at #7 amid divergent competitor momentum implies share defense rather than a move back toward its peak of #5 from September 2024.
Notable Products
Light On - THC/THC-V 2:1 Green Crack Gummies 5-Pack (100mg THC, 50mg THCV) recorded the steepest decline at -257.4% month over month while sitting at rank 2, far outpacing the -18.1% drop of Lights Out - THC/CBN 1:1 Midnight Cherry Gummies 5-Pack (100mg THC, 100mg CBN) at rank 1. Blue Dream Distillate Cartridge (1g) fell -8.1% at rank 9 as Pineapple Express Distillate Cartridge (1g) slid -6.8% at rank 10, and eight of the top ten SKUs were Edibles, concentrating mix into a single category even as Vapor Pens held two lower top-10 slots. With Lights Out still the top seller at $297,096 amid broad declines, the pattern implies Heavy Hitters is leaning into an Edibles-led lineup while volatility in a flagship functional gummy raises risk concentration in September 2026.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

